
Hot US inflation drives Fed repricing
Ahead Today
G3: US MBA Mortgage Applications
Asia: -
Market Highlights
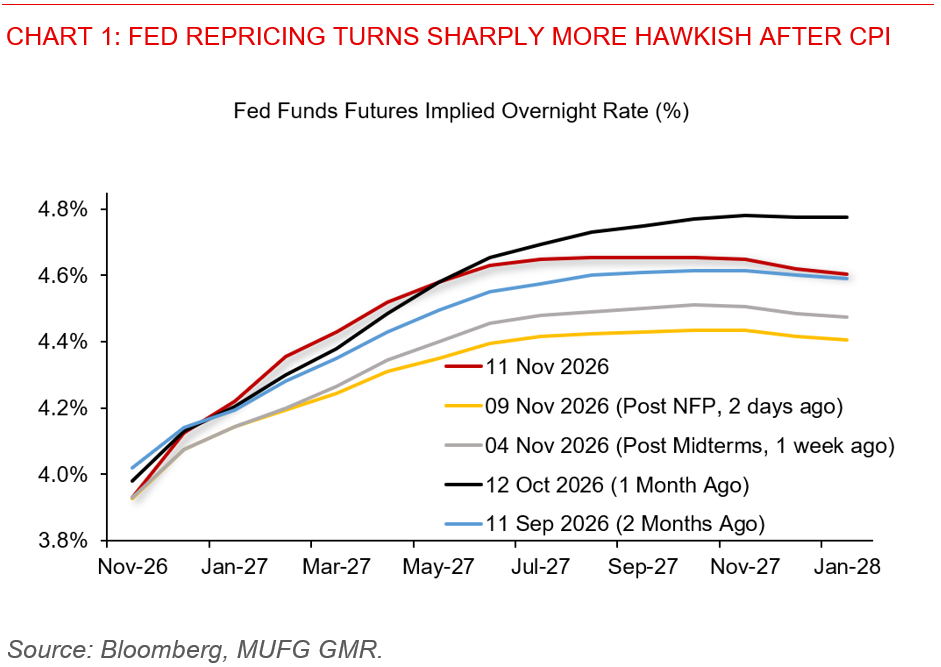
US delivered a set of higher-than-expected CPI inflations in October, reinforcing expectations for December Fed hike following last week’s strong payrolls report. Headline CPI rose 0.4%mom, while core inflation increased 0.3%mom. Due to the government shutdown in October last year, no year-on-year data was released. This is the last CPI report before the meeting on December 8-9. Following the data release, a December 25bps rate hike was fully priced in, with the probability of a 50bps hike rising to 13.6% at one point. After the release, US 2-year Treasury yields rose 18bps to 4.74%, and the Dollar Index strengthened back above 102.
Fed Governor Waller struck a more hawkish tone yesterday before the CPI release, stating that inflation is too high and further monetary tightening is needed and he explicitly laid out a threshold: a December 50bps rate hike should be considered, if October core CPI rose 0.3%mom or more.
For Asia FX, renewed higher US rate and stronger dollar pressure is being partly offset by the sharp decline in oil prices. Brent continues trading lower, as Middle East peace talks continued, with Brent crude briefly falling below $90, the first time since August – This provides meaningful relief to the region’s energy importers, but overall, higher US yield and stronger US dollar still likely generate pressure on Asian currencies in today’s trading session in Asia
China’s October trade data underscored the economy’s continued dependence on the external demand including demand incurred by global technology cycle. Exports rose 35.2%yoy, led by a 66.6% surge in high-tech shipments, while imports accelerated to 41.6%yoy as integrated-circuit imports jumped 78%. The data contrast with this week’s softer domestic inflation readings, highlighting strong external demand against still-subdued domestic consumption. For CNY, robust export receipts and corporate FX conversion remain supportive.
In Japan, the BoJ’s latest Summary of Opinions reinforced expectations of another rate hike in December. Several board members argued that rates should move closer towards neutral as underlying inflation reaches 2%, while financial conditions remain accommodative. Markets are pricing an 82% probability of a December hike, providing some underlying support for the yen.
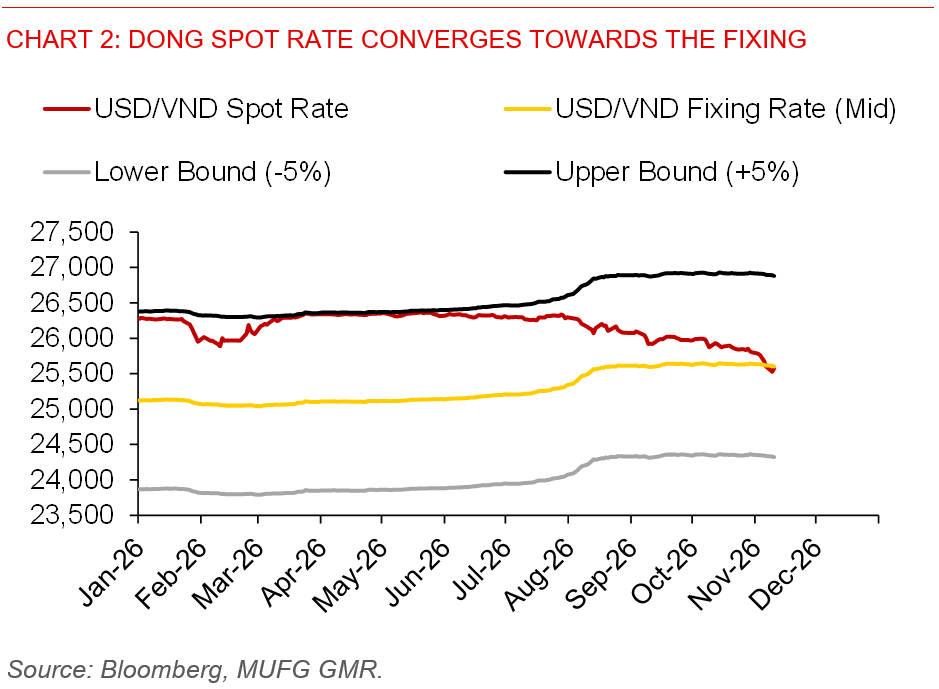
The VND has strengthened notably in recent weeks as improved FX supply, supported by trade surpluses, FDI inflows and an earlier softer USD, has reversed earlier depreciation pressure. In response, the State Bank of Vietnam has shifted toward absorbing excess FX liquidity, first introducing a USD2bn, 182-day USD/VND swap on 6 November and then offering to buy spot USD at VND25,500 twice each week from 11 November. The measures indicate that the SBV is increasingly focused on rebuilding FX reserves, preventing excessive VND appreciation and injecting VND liquidity to ease domestic funding conditions. Near term, supportive external flows should support VND, but the VND25,500 purchase rate should act as a soft floor for USD/VND, limiting the scope for further substantial VND appreciation.