
APEC Summit in focus
Ahead Today
G3: US Initial Jobless Claims
Asia: APEC Summit 2026, Malaysia CPI
Market Highlights
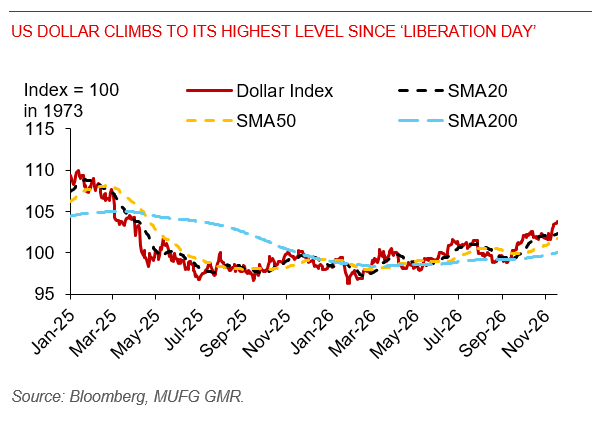
Asia FX enters today’s Xi–Trump–Putin meeting in Shenzhen on a defensive footing, with DXY above 103.70 and the October FOMC minutes reinforcing expectations for further tightening. Geopolitical issues such as the Russia-Ukraine war, the Iran conflict, and arms control are expected to be discussed. Markets will also watch for signs of how tech tensions evolve following the latest US chip restrictions.
Separately, almost all Fed officials have judged that additional rate hikes would likely be appropriate in the months ahead to bring inflation back to the 2% target. Markets continue to fully price in a 25bps hike in December, three 25bps hikes by June next year, leaving elevated US rates and a resilient dollar as major headwinds for Asia FX. That said, the recent decline in oil prices should provide some offset.
Meanwhile, markets will watch the much-awaited Anthropic’s IPO debut later today. Anthropic’s IPO matters because it will help reflect market sentiment towards the tech sector following recent selloffs.
Bank Indonesia raised its policy rate by 25bps to 6.00% yesterday, in line with our expectation given persistent rupiah depreciation pressures. BI has also announced further reductions in hedging premiums on some DNDF tenors and plans to introduce cross-currency repo transactions to improve banks’ access to liquidity by March at the latest. The rate hike is likely to help slow the pace of depreciation but not reverse it. A firm US dollar, MSCI risks, and fragile investor confidence remain key headwinds for the rupiah.
Malaysia’s final Q3 GDP growth was revised up to 5.5%yoy from the 5.3% advance estimates. Growth was supported by domestic demand and AI-related activity. Despite the Q3 GDP growth upgrade, MYR was a regional underperformer yesterday, with USD/MYR breaking above the 4.10 level.