
US yields retreat, but higher Brent remains a key headwind
Ahead Today
G3: US PMI, University of Michigan sentiment
Asia: Taiwan industrial production, Singapore CPI
Market Highlights
Lower US yields will provide some temporary reprieve for selective Asia FX, but persistently high oil prices remain an important headwind. The US 10-year yield fell around 16bps to below 5%, softening DXY by 0.2%. But Brent crude prices rose by another 4% to around USD113/bbl following fresh attacks in Saudi Arabia, keeping oil-sensitive currencies such as IDR, PHP, and THB under downward pressure despite the lower Treasury yields.
The yen was a key beneficiary of the Treasury rally, with USD/JPY falling 0.9%. The 160 resistance level for USDJPY will likely remain intact in the near term. Domestic developments are also reinforcing expectations for gradual BOJ policy normalisation. Japan’s core inflation, excluding fresh food and energy, accelerated to 2.4%yoy in September from 1.9% in August, while Rengo is targeting wage increases of around 6% in 2027. Markets are pricing one to two BOJ rate hikes over the next 12 months.
US PMI and University of Michigan sentiment will be the key macro releases later today, providing the latest read on activity and consumer confidence.
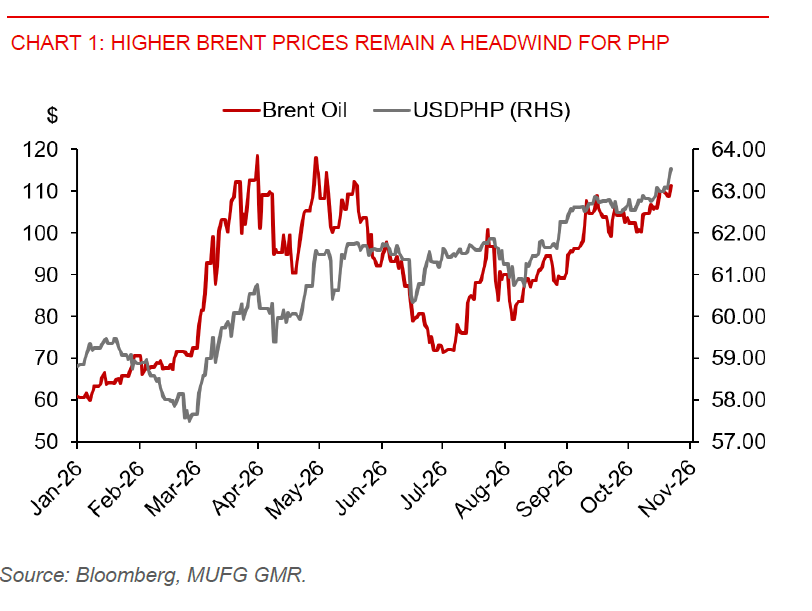
Meanwhile, monetary policy is providing varying degrees of support. The BOK kept rates at 3.00% after back-to-back hikes but maintained a tightening bias amid stronger growth and firm underlying inflation. The BSP was more aggressive, delivering a surprise jumbo 50bp hike to 5.50% yesterday as inflation reached 7.2%yoy. Nonetheless, tighter policy could put more pressure on economic growth, and we stay cautious on PHP, given a challenging external backdrop.
We also maintain a cautious view on IDR. Further increases in oil prices add to an already challenging external backdrop, while MSCI-related portfolio-flow risks remain an important downside risk. Indonesia's planned CNY10bn panda bond issuance later this year should help diversify sovereign funding but does not materially change the broader FX picture.
On the other hand, CNY and SGD should remain relatively defensive in the region. Singapore inflation due today will be important. A headline inflation reading above 2.5% could reinforce expectations of MAS tightening bias in the January 2027 policy meeting.
Overall, lower US yields provide some breathing room for Asia FX, but oil is also increasingly driving regional FX differentiation.