
Ahead Today
G3: US initial jobless claims, housing starts; eurozone CPI
Asia: CBC interest rate decision
Market Highlights
The Federal Reserve raised the policy rate by 25bp to 3.75%-4.00% in a unanimous decision. Policymakers signalled that growth is still resilient, but inflation remains a key concern. Importantly, the updated median dot plot points to one additional hike this year, while the longer-run neutral policy rate was revised up to 3.25% from 3.06% in June. The Fed also upgraded its growth and inflation outlook. Markets have priced in about 1.3 hikes by year-end and 2.5 hikes by Q1 2027. The Middle East conflict still persists, with Brent and US retail gasoline prices staying elevated, keeping inflation risks alive.
US 2-year Treasury yields rose another 7bp to 4.73%, while the 10-year yield has broken above 5%. More broadly, global bond markets remain under pressure. A hawkish Fed and elevated oil prices suggest that front-end US rates could remain biased higher and should therefore continue to offer support for the US dollar. The DXY dollar index gained 0.7% yesterday, recapturing the 100 level.
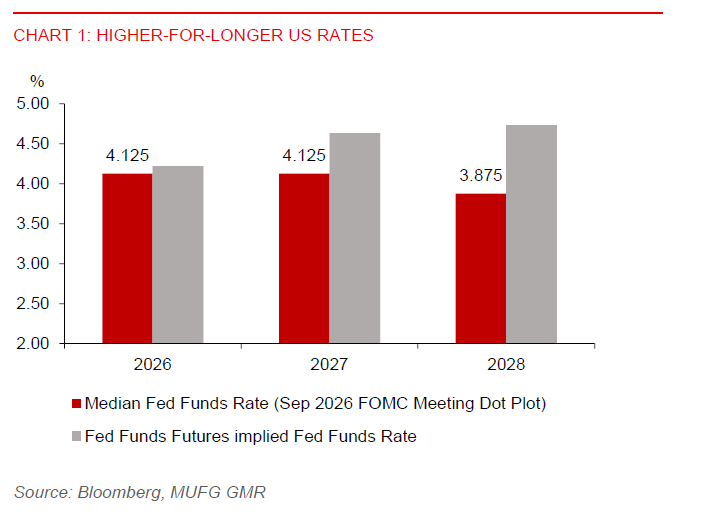
Higher US yields and a higher-for-longer Fed policy rate backdrop could weigh on Asian currencies.
Within ASEAN FX, we have stayed cautious on THB and IDR. Thailand's economy continues to face a deteriorating terms-of-trade backdrop as rising oil import costs outweigh the gains from stronger electronics exports. The electronics sector’s high imported content also limits the net positive effect on the trade balance. As a result, higher energy costs continue to erode external balances, leaving THB vulnerable as Fed tightening expectations rise.
We also retain a cautious view on IDR. Indonesia has historically benefited from stronger commodity prices, but there are limits to the buffer offered by coal, palm oil and base metal exports when Brent remains above US$100/bbl. The oil shock increasingly offsets gains elsewhere in the commodity complex, while rising US yields narrow the attractiveness of local assets. In our view, both THB and IDR remain vulnerable to further depreciation as markets price more Fed tightening into early 2027.
While MYR has been underpinned by stronger domestic fundamentals and continued support from the electronics upcycle, fed tightening still present headwinds. The 4.15 level in USDMYR remains an important threshold to monitor closely. Should depreciation pressures intensify beyond that point, markets may increasingly focus on the possibility of additional policy or FX-support measures. While we remain medium-term constructive on MYR, the near-term environment argues for continued volatility as global markets adjust to a more hawkish Fed and higher US rates.