
Focus on Bank Indonesia meeting
Ahead Today
G3: US S&P PMI, Eurozone PMIs
Asia: Bank Indonesia policy rate, Singapore CPI, India PMI
Market Highlights
Risk sentiment was mixed, the Dollar was somewhat stronger, while oil hovered around the US$100/bbl mark, as markets weighed uncertainty of prospects for a US-Iran deal but offset by signs that Saudi Arabia is restarting its East-West pipeline. In particular, Saudi Arabia is in the early stages of starting up its key oil pipeline that has enabled Riyadh to bypass the Strait of Hormuz after the conduit was halted earlier this month, with news reports suggesting that the kingdom is aiming for a meaningful restart of flows by Saturday. Multiple oil traders said there were already signs of tankers arriving at the port of Yanbu, from where the piped supply is exported. Nonetheless, this was juxtaposed by President Trump’s speech at the UN, where he justified his decision to go to war with Iran as the action of a leader who refuses to let problems fester, while he is also using American power to confront longstanding challenges in contrast with other leaders who he said only talk about doing so. Trump also said he thought Iran was holding out to make a deal until after the US mid-terms, and that he believes a deal will be made with Iran right after the election.
For Asia in particular, the good news is that oil prices have moderated somewhat from the highs but the path forward remains unclear given the lack of clarity around a possible resolution of the conflict.
Nonetheless, what continues to help and more than offset oil prices as we have mentioned is the strong AI demand and infrastructure build-out, coupled with positive signals from the Trump-Xi summit so far. On this front we had absolute blowout export orders data from Taiwan at 71%yoy for August, while South Korea’s 20 days export growth also accelerated from 56%yoy to 78%yoy. We continue to like both KRW and TWD as plays on the AI story.
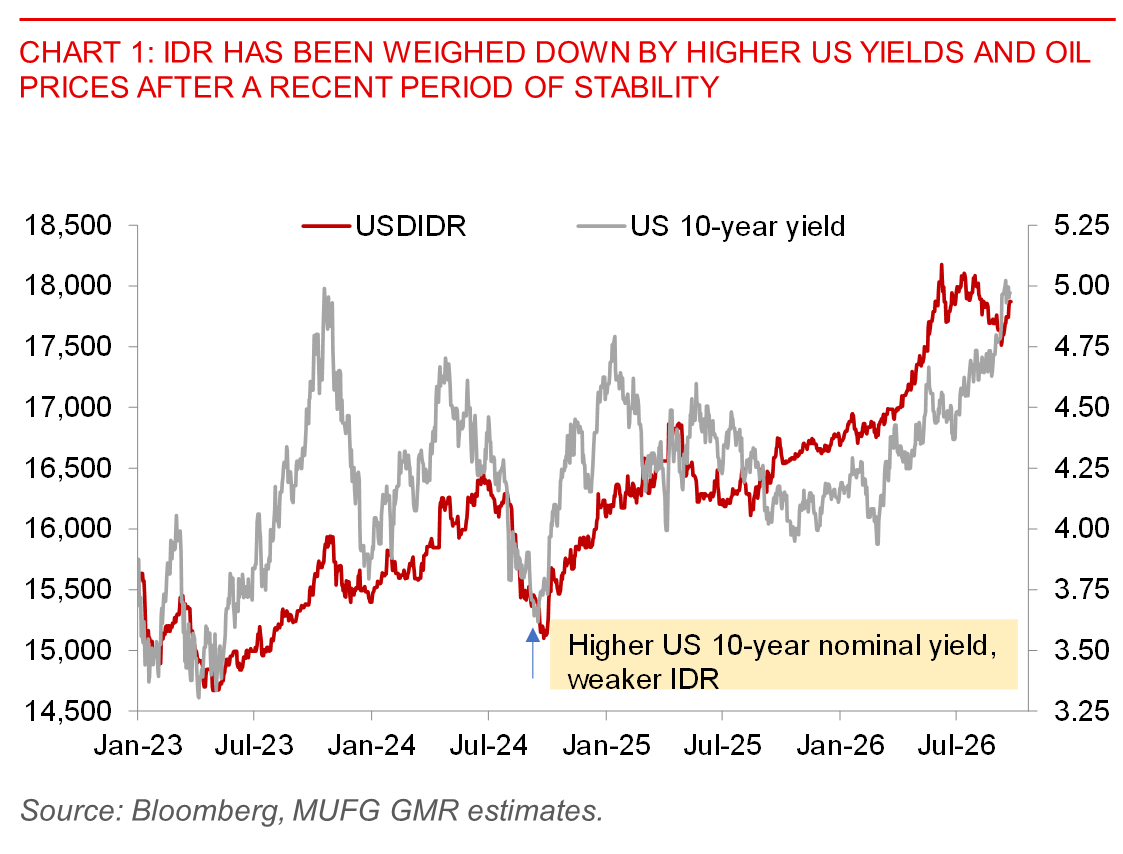
The key event in Asia today will be Bank Indonesia’s policy meeting. Markets are expecting BI to remain on hold, in part because of a more stable IDR so far notwithstanding greater volatility driven by US rates. Beyond the rate decision, there will also be a focus on whether BI’s measures to attract foreign capital including FX hedging subsidies will be further expanded and how meaningful they could be in stabilising IDR. We remain cautious on IDR given continued risks from domestic policy uncertainty coupled with external risks driven by higher US rates and oil prices.