
RBI – to hike or not to hike?
Week Ahead FX outlook:
Asia takes centre stage in the week ahead, even as key global themes of rising DM government bond yields and volatile oil prices remain crucial drivers for the currencies and markets in our region.
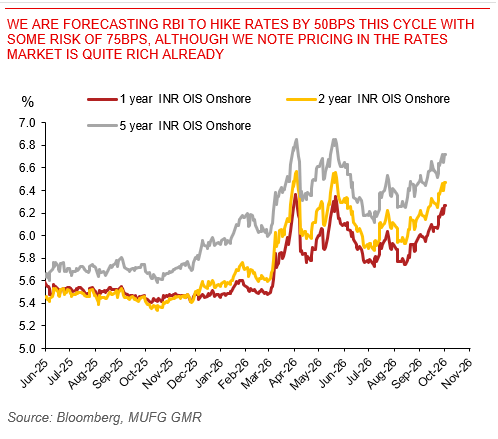
The focus in Asia will be led in particular by a finely balanced Reserve Bank of India decision on 7 October. The consensus points to a 25bp hike by RBI, but we note that expectations are very split. We are officially forecasting RBI to keep rates on hold, but more importantly we have already been calling for the central bank to start its hiking cycle from December so ultimately we think it’s just a matter of time before policy rates move higher. We see a good chance RBI will also move its stance away from neutral to signal a tightening bias. We have 50bps of rate hikes in our forecast profile, and have mentioned that there could be a risk of 75bps in total this cycle, given that growth is strong, liquidity is abundant, credit growth is picking up, fiscal policy is supportive, while higher commodity prices and adverse weather conditions lend inflation risk to the upside in India.
Elsewhere, we will get inflation data points out of several Asian markets such as the Philippines, Thailand, Vietnam and Taiwan. For Philippines we are forecasting the BSP to keep a hawkish stance for now although depending on how oil prices and El Nino pan out some space to cut rates could eventually emerge in 2H2027. Meanwhile, Vietnam releases a broad set of activity, inflation and trade indicators and Malaysia reports industrial production.
In Japan, BOJ Governor Ueda’s speech and wage data will be important for assessing the timing of the BOJ’s next move. Headline labour cash earnings growth is expected to slow to 3.7% from 4.3% as summer bonuses normalise, although underlying base-pay momentum is likely to remain firm, keeping the prospect of further monetary tightening alive. Governor Kazuo Ueda’s speech on 6 October will provide an additional policy signal, while household spending and current-account data are also due.
We are forecasting RBI to hike rates by 50bps this cycle with some risk of 75bps, although we note pricing in the rates market is quite rich already