
BOK in focus, tech under pressure
Download the full PDF report using the link above.
Week Ahead FX outlook:
High US yields remain a key constraint on Asia FX, but the tech outlook is becoming the next risk to watch. Resilient US activity has kept the USD and Treasury yields supported. Next week's US PMI survey, Q3 GDP and consumption data will therefore matter through the rates channel: another resilient US macro data set would reinforce higher-for-longer yields.
The bigger risk is that the US tech sell-off starts moving down the investment chain. So far, the equity correction has been concentrated more in valuations and portfolio flows than in underlying Asian semiconductor demand. The key question is whether weaker tech equities begin to affect hyperscaler capex, semiconductor orders and ultimately physical AI/data-centre investment. If that happens, Asia FX would face a tougher combination of equity outflows and weaker export expectations, particularly for KRW and TWD.
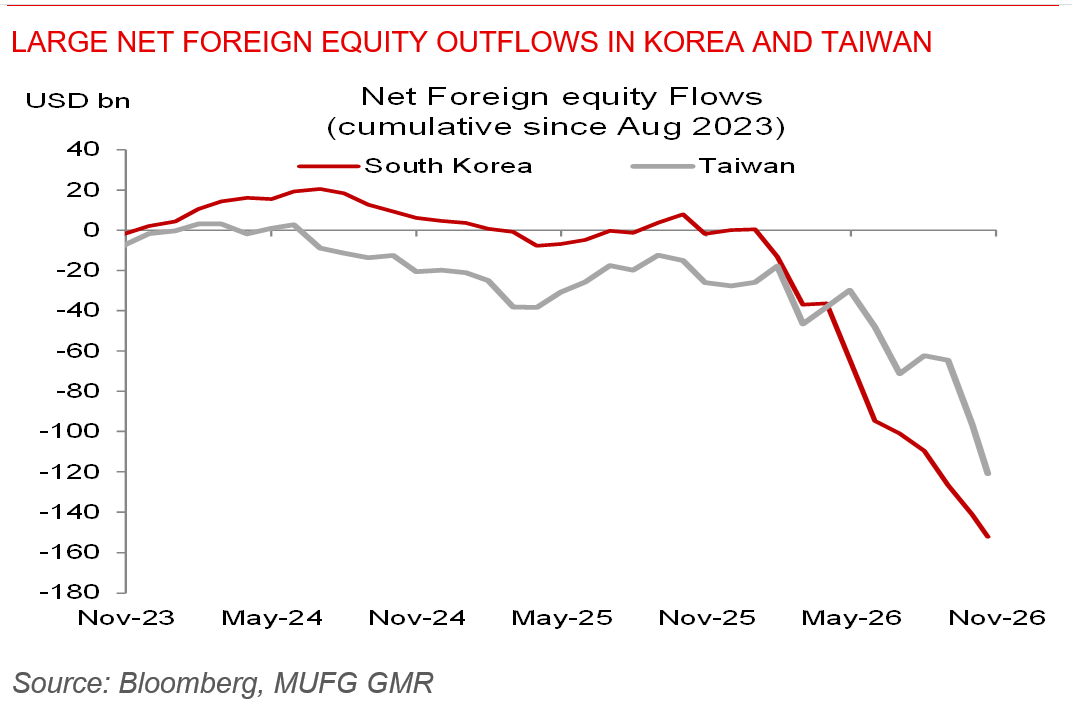
KRW has been relatively resilient because strong macro and trade fundamentals are cushioning equity outflows. Korea continues to benefit from the semiconductor-led trade cycle, while potential rate hike at next week's BoK meeting adds an important domestic catalyst amid firm growth and sticky inflation. This has helped KRW hold up despite KOSPI weakness and around US$11bn of foreign equity outflows this month.
TWD illustrates more clearly how portfolio flows can overwhelm good fundamentals. Taiwan remains at the centre of the AI and semiconductor cycle, and next week's Q3 GDP print is expected at a very strong 14.4%yoy. Yet more than US$24bn of foreign equity outflows this month, considerably larger than Korea's, have put greater pressure on TWD.
Singapore also has a relatively busy week. October CPI is expected to moderate to 1.9%yoy from 2.2%, followed by final Q3 GDP growth of 5.6%yoy versus 5.4% previously and industrial production. The combination of easing inflation but still strong growth would broadly reinforce a resilient backdrop for SGD.
Large net foreign equity outflows in Korea and Taiwan