
Please download PDF using the link above for the full report
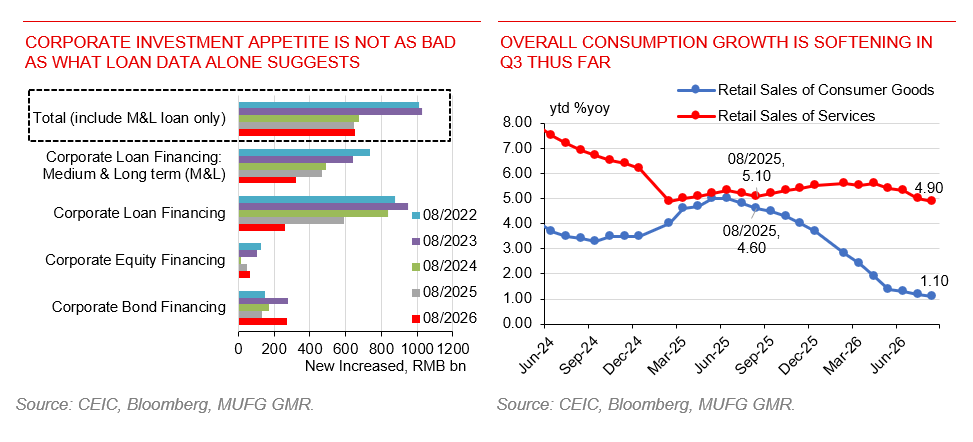
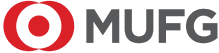
Domestic demand remained weak in August despite resilient industrial activity.
Policy implementation appears to be accelerating, but its impact has yet to materialize. Meanwhile, recent property reforms should strengthen the sector’s long-term fundamentals but may create near-term headwinds for sector’s activities.
The pace of fiscal and quasi-fiscal support, together with the implementation of key projects such as the “Six Networks”, will be critical in determining whether domestic demand can achieve a sustained recovery. We expect ongoing policy support and accelerated project execution to help stabilize investment in Q4.
We remain constructive on the RMB, supported by China’s strong trade surplus and positive sentiment toward the technology sector. We continue to expect USD/CNY to reach 6.65 by Q4, although risks remain two-sided.