
USD continues to strengthen despite softer US inflation
USD: US inflation & lower energy prices fail to dampen upward momentum
The US dollar has continued to strengthen overnight resulting in the dollar index moving closer to the year-to-date high from June at 101.80. The US dollar’s upward momentum has continued even after recent Fed rhetoric and softer US inflation data should help to dampen expectations for more aggressive Fed hikes. New York Fed President Williams message that “there is no need for urgency” following this month’s rate hike, and they can take their time to review additional data before tightening policy further” was quickly backed up by the release of the softer than US PCE deflator report for August. The report revealed that the core PCE deflator increased by 0.2%M/M in August, and there were bigger than expected downward revisions to prior months. As a result, the annual rate of change came in at 3.0% compared to consensus forecast of 3.3%.
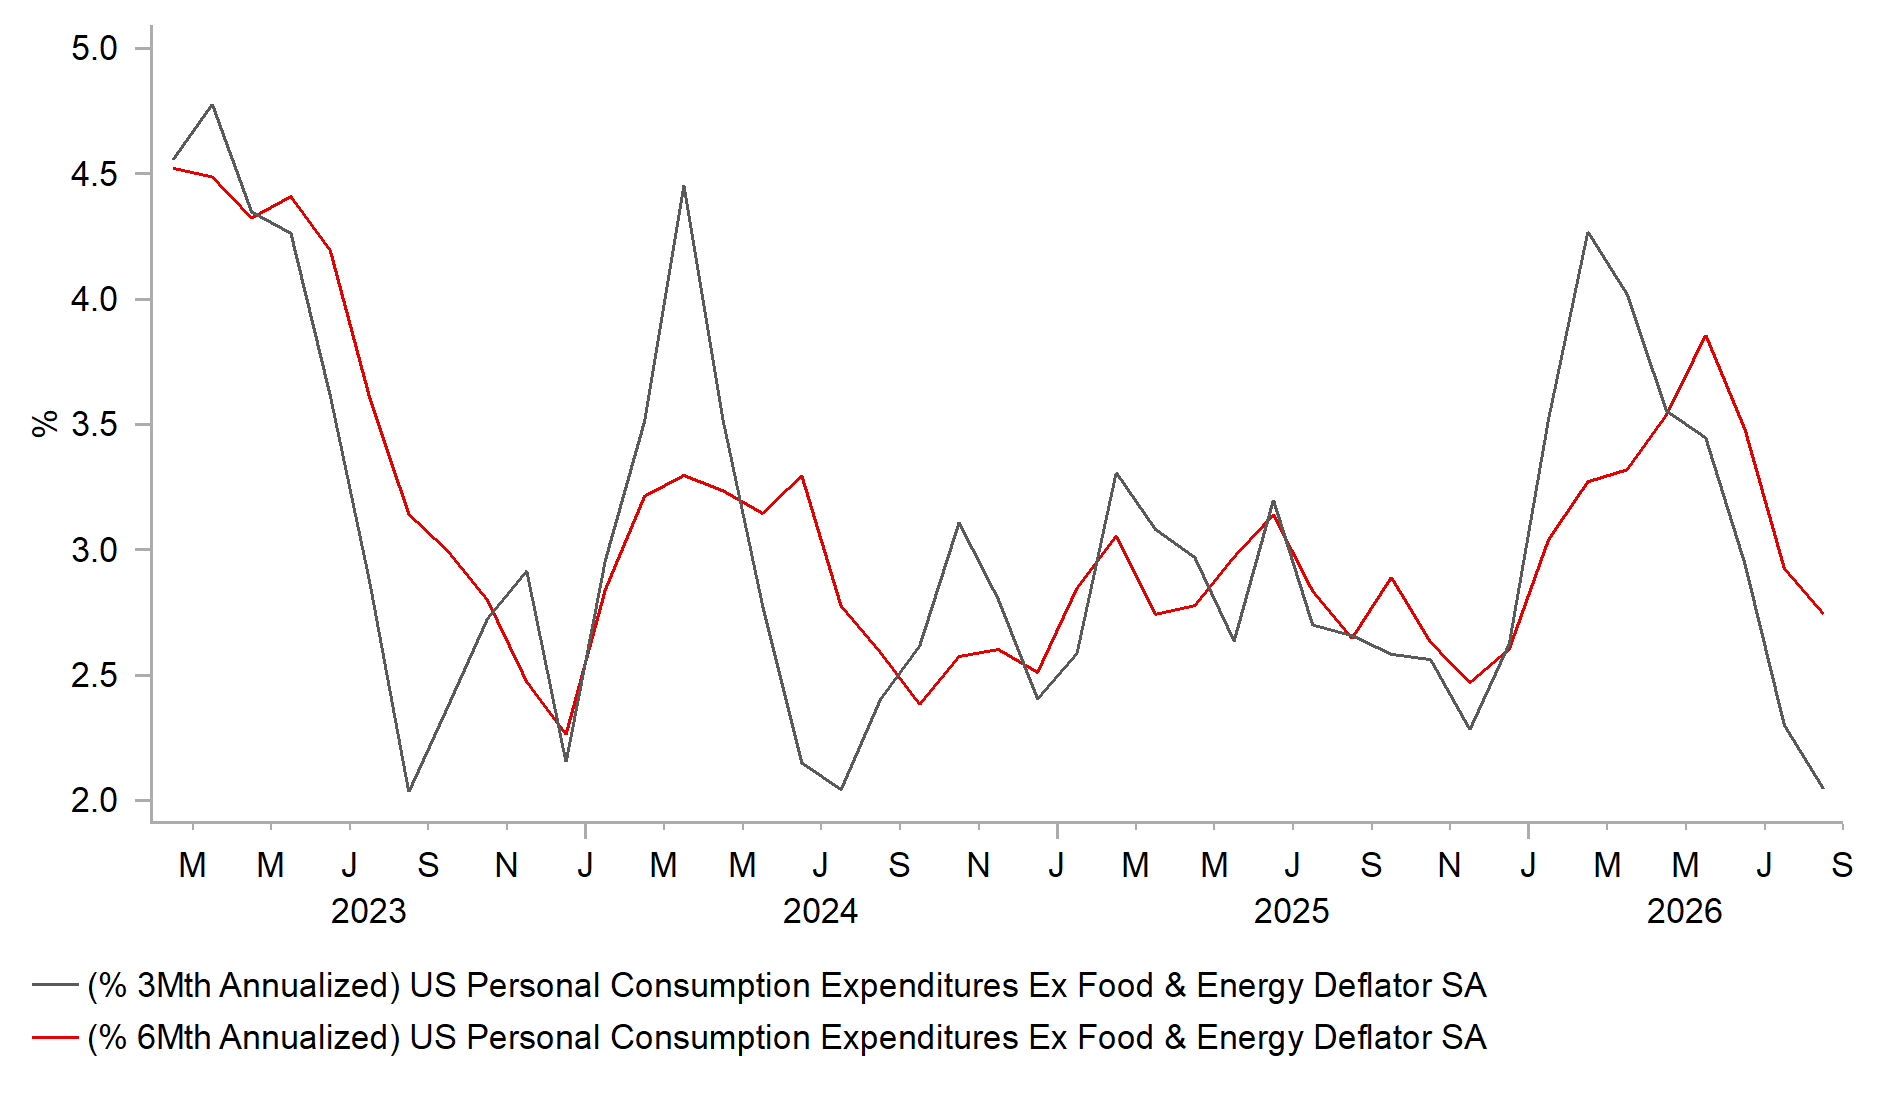
After the downward revisions, there is clearer evidence of a slowdown in the Fed’s preferred measure of underlying inflation pressures. The three-month annualized rate of growth has fallen to just 2.1%. Looking back at the period since the US-Iran conflict began, the six-month annualized rate of growth has slowed to 2.7% in August down from 3.3% in February. The report should provide some reassurance that there has been some progress towards meeting their inflation goal, although perhaps not as quickly as they would like. It makes it less likely that the Fed will hikes rates as aggressively as currently priced into the US market which is expecting three to four hikes in the year ahead. The probability of back-to-back hike as soon next month ahead of the US mid-term elections has continued to fall. Short-term US yields and the US dollar initially fell after the report but the moves proved to be short-lived.
The main reason for the softer PCE deflator report were bigger than expected revisions from the Bureau of Economic Analysis after they updated their methodology for three components: portfolio management and advice, software and accessories, and legal services. It was broadly expected that the revisions would lower the annual rate of change for the core PCE deflator by roughly 10-20bps but the actual revisions lowered it by 36bps. Of which portfolio management and advice account for 30bps of the downward revisions. The Fed will now wait to see the upcoming NFP report on Friday and US CPI report for September on 14th October as they continue to assess when to hike rates further.
At the same time, the US dollar has continued to strengthen even as energy prices have eased over the past week. The price of Brent has dropped back below USD100/barrel encouraged by reports that crude oil flows from the Middle East are returning toward pre-conflict levels despite continued risks to shipping. Bloomberg has reported that shipments of crude oil have rebounded to 17.5 million barrels/day, or 98% of pre-ware levels according to JPMorgan. However, shipments of diesel and gasoline are still more disrupted at around 58% of pre-war levels. The report adds that Saudi Arabia’s estimated exports of oil have more than doubled in September and rose above last year’s average. The report backs up claims from the US recently that elevated flows were begin shipped through the Strait.
US INFLATION PROGRESS BETTER THAN EXPECTED OVER SUMMER
Source: MUFG Research, Macrobond, Bloomberg
JPY: October BoJ rate hike speculation fades triggering renewed selling
The yen has been the biggest mover overnight falling by around 0.5% against the US dollar which has lifted USD/JPY up to a high of 158.44. The main trigger for the yen’s sell-off was the release of the Summary of Opinions from the latest BoJ policy meeting from 17th-18th September policy meeting. The Summary of Opinions appears to have disappointed some market participants who were looking for a stronger signal that the BoJ were open to another hike as soon as next month. It has prompted the Japanese rate market to scale back rate BoJ hike expectations. At the start of this week, the Japanese rate market had been pricing in around 10bps of hikes by the October policy meeting and that has now dropped to around 5bps. It fits with our view that another hike as soon as next month remains unlikely given that the BoJ had just sped up the pace of hikes this month and signalled that it is likely to continue hiking rates every three months. We expect another hike by the end of this year in December.
The Summary of Opinions reiterated that underlying inflation is now getting closer to their 2.0% target, and the perspective of stabilizing it around 2.0% has become important in order to keep the risk of underlying inflation deviating upward to a level above the price stability target and thereby exerting an adverse impact on the economy afterward. It was for this reason that the BoJ considered there had been a shift in the phase of monetary policy. The BoJ added that “if signs of an upward deviation in prices are observed, they will need to accelerate the pace of rate hikes. We expect a rate hike every three months in the new phase of monetary policy. Rising rates in Japan should continue to offer support for the yen over time. However, with the Fed and other major central banks also hiking rate at the same time it makes it is making it more difficult for Japanese policymakers to prevent a weaker yen.
KEY RELEASES AND EVENTS
Country | BST | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
GB | 09:00 | BoE Gov Bailey Speaks | - | - | - | !!! |
EU | 09:00 | Manufacturing PMI | (Sep) | 52.7 | 52.7 | !! |
GB | 09:30 | Manufacturing PMI | (Sep) | 52.0 | 51.7 | !!! |
EU | 10:00 | Unemployment Rate | (Aug) | 6.4% | 6.4% | !! |
DE | 11:35 | German Buba President Nagel Speaks | - | - | - | !! |
GB | 13:00 | BoE MPC Member Mann | - | - | - | !! |
US | 13:30 | Initial Jobless Claims | - | 201K | 197K | !!! |
GB | 13:30 | BoE MPC Member Pill Speaks | - | - | - | !! |
EU | 14:30 | ECB President Lagarde Speaks | - | - | - | !! |
US | 15:00 | ISM Manufacturing PMI | (Sep) | 54.8 | 54.6 | !!! |
US | 15:00 | Fed Waller Speaks | - | - | - | !! |
Source: Bloomberg & Investing.com