
Rising volatility could extend US dollar gains
EUR: OAT selling intensifies
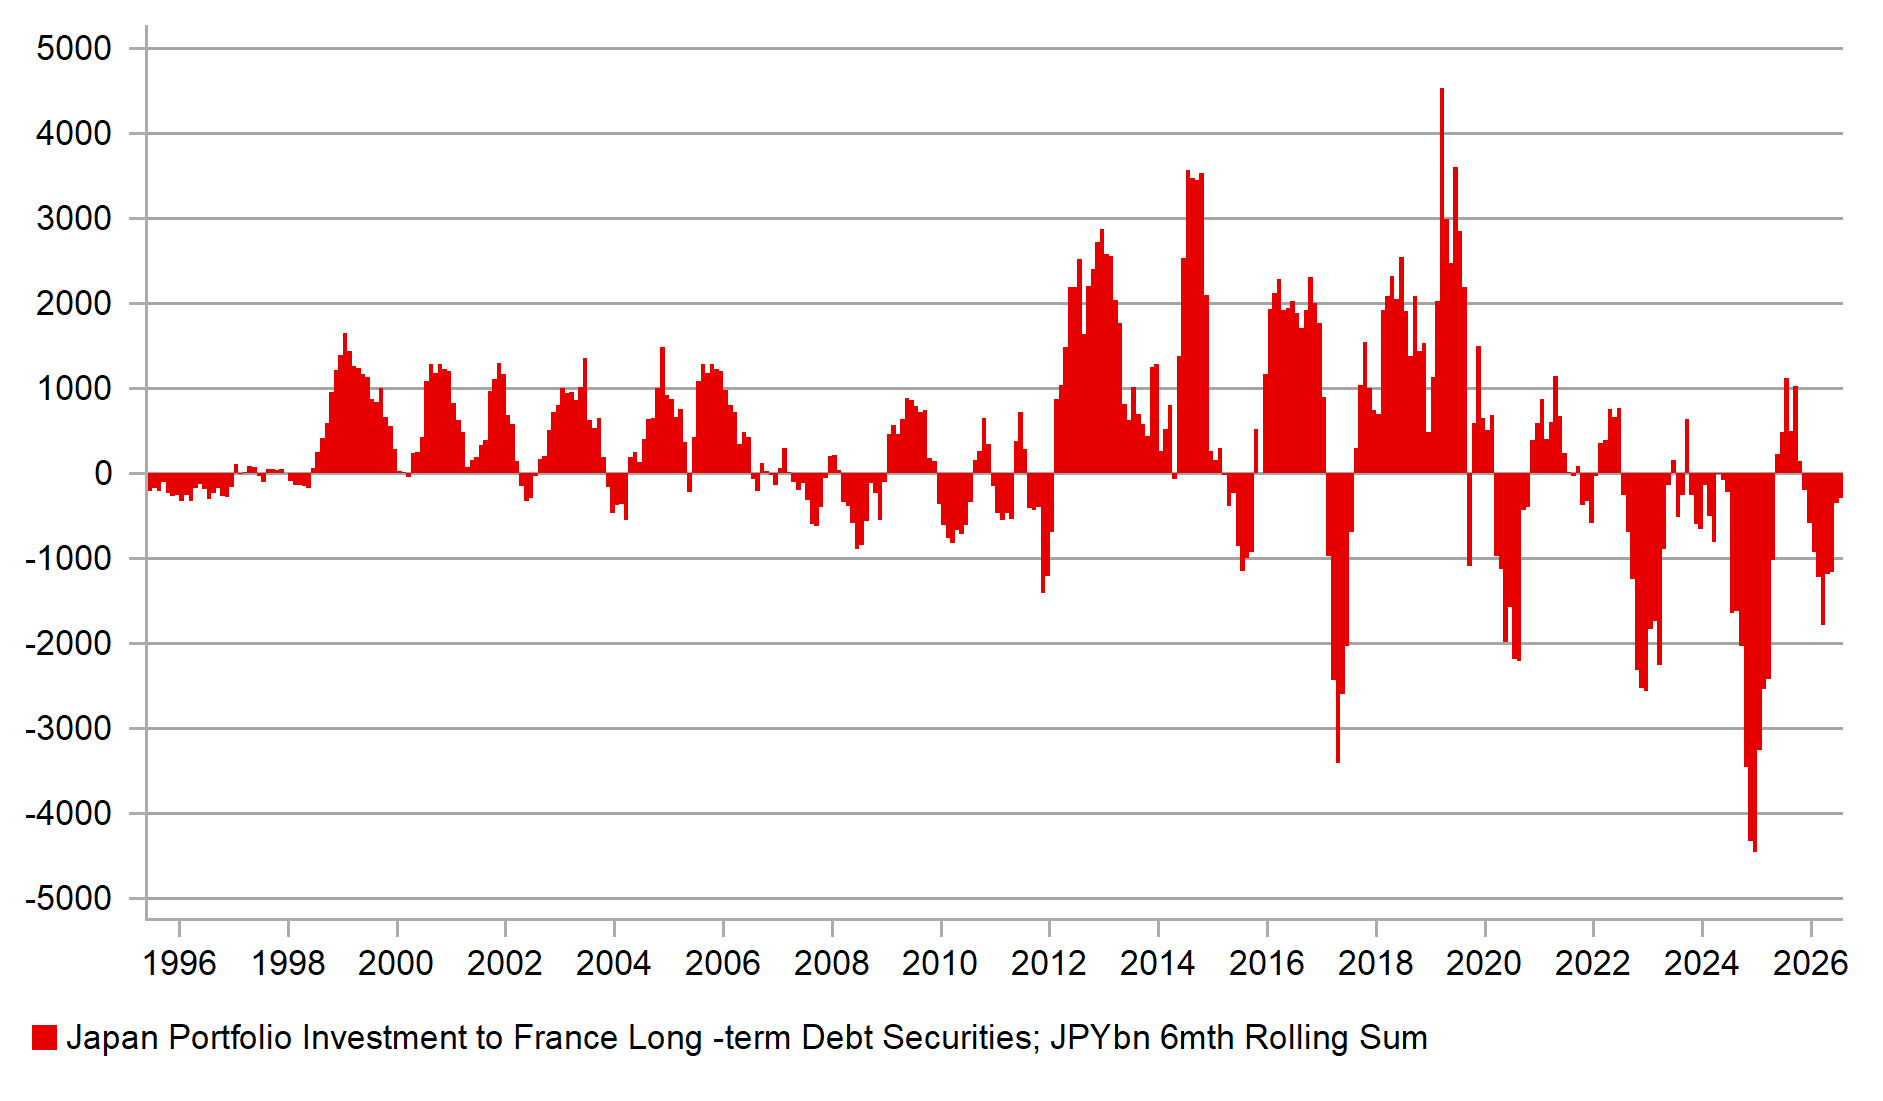
The OAT/Bund spread widened out sharply yesterday, which was a clear indication that the budget details announced in parliament did not go down well with investors. It was perhaps a difficult task anyway given the poor fixed income sentiment at the moment. Still, the scale of the move is surprising and since the end of August the spread has widened by 56bps, a 65% increase pointing to large scale selling by investors. Bloomberg today reports that Sumitomo Mitsui DS Asset Management had sold its entire French bond holdings. In general, Japanese investors have been paring their holdings according to Balance of Payments data. In 2025 and in 2026 year-to-date, Japanese investors have bought JPY 658bn worth of German debt, JPY 775bn worth of Italian debt but have sold JPY 356bn of French debt. In 2024 Japanese investors were sellers across most key European debt markets but sold the most of French debt – JPY 4,678bn worth compared to JPY 891bn worth in Germany and JPY 687bn worth of Italy debt. Japan has been sellers since 2020 although France historically has been a popular debt market destination in Europe.
One of the issues yesterday was the question marks over the projections used for the basis of the budget calculations. The HCFP – the fiscal watchdog in France – described the budget as “optimistic” with growth forecast to accelerate from 0.5% this year to 1.0% in 2027. That’s the growth needed to bring the budget deficit down from 5.4% to 5.0%. There was specific doubts mentioned over the assumption of a notable pick-up in business investment during a period in which we are witnessing surging sovereign yields that will feed through to tighter financial conditions.
The euro also could suffer further given the risks of another surge in energy prices. A US export ban of diesel hangs over the market which if introduced would certainly see prices extend higher – Europe imports around 32% of its total diesel imports from the US. The Trump administration is now pressuring Europe to release stocks or deal with the consequences of an export ban. Trump needs to get diesel prices down ahead of the mid-terms following a 70% surge since the Middle East conflict began. Wholesale prices are up by a similar amount in Europe. Europe’s Energy Union Task Force will meet this morning to discuss possible action.
The dominant factors today for EUR/USD will be the OAT/Bund spread and the payrolls report from the US. A strong report could reinforce the poor sentiment and create additional volatility. If the spread does keep widening, we could quickly see markets speculate on possible ECB support from talking back rate hikes priced or considering indirect (changes in QT) or direct (TPI) action to support OATs. We are a long way from that but all of these potential ECB responses are EUR negative that will only reinforce the current downward pressure. Our FX Outlook (here) released yesterday included very notable downward revisions to our EUR/USD forecasts.
JAPAN HAS BEEN MOSTLY SELLERS OF FRENCH DEBT SINCE COVID
Source: MUFG Research, Macrobond, Bloomberg
EM FX: Carry unwind intensifies
We have been flagging the increased risk of the volatility in the rates market spreading to other markets and the increased risks of a broader liquidation of carry positions. EM FX is certainly seeing that now with significant moves in LatAm FX as carry liquidation intensifies. There has been an increasing risk of losses suffered in fixed income spreading as investors start to pare profitable positions to offset fixed income losses. EM FX volatility has now surged back close to the highs seen following the start of the Middle East conflict in March.
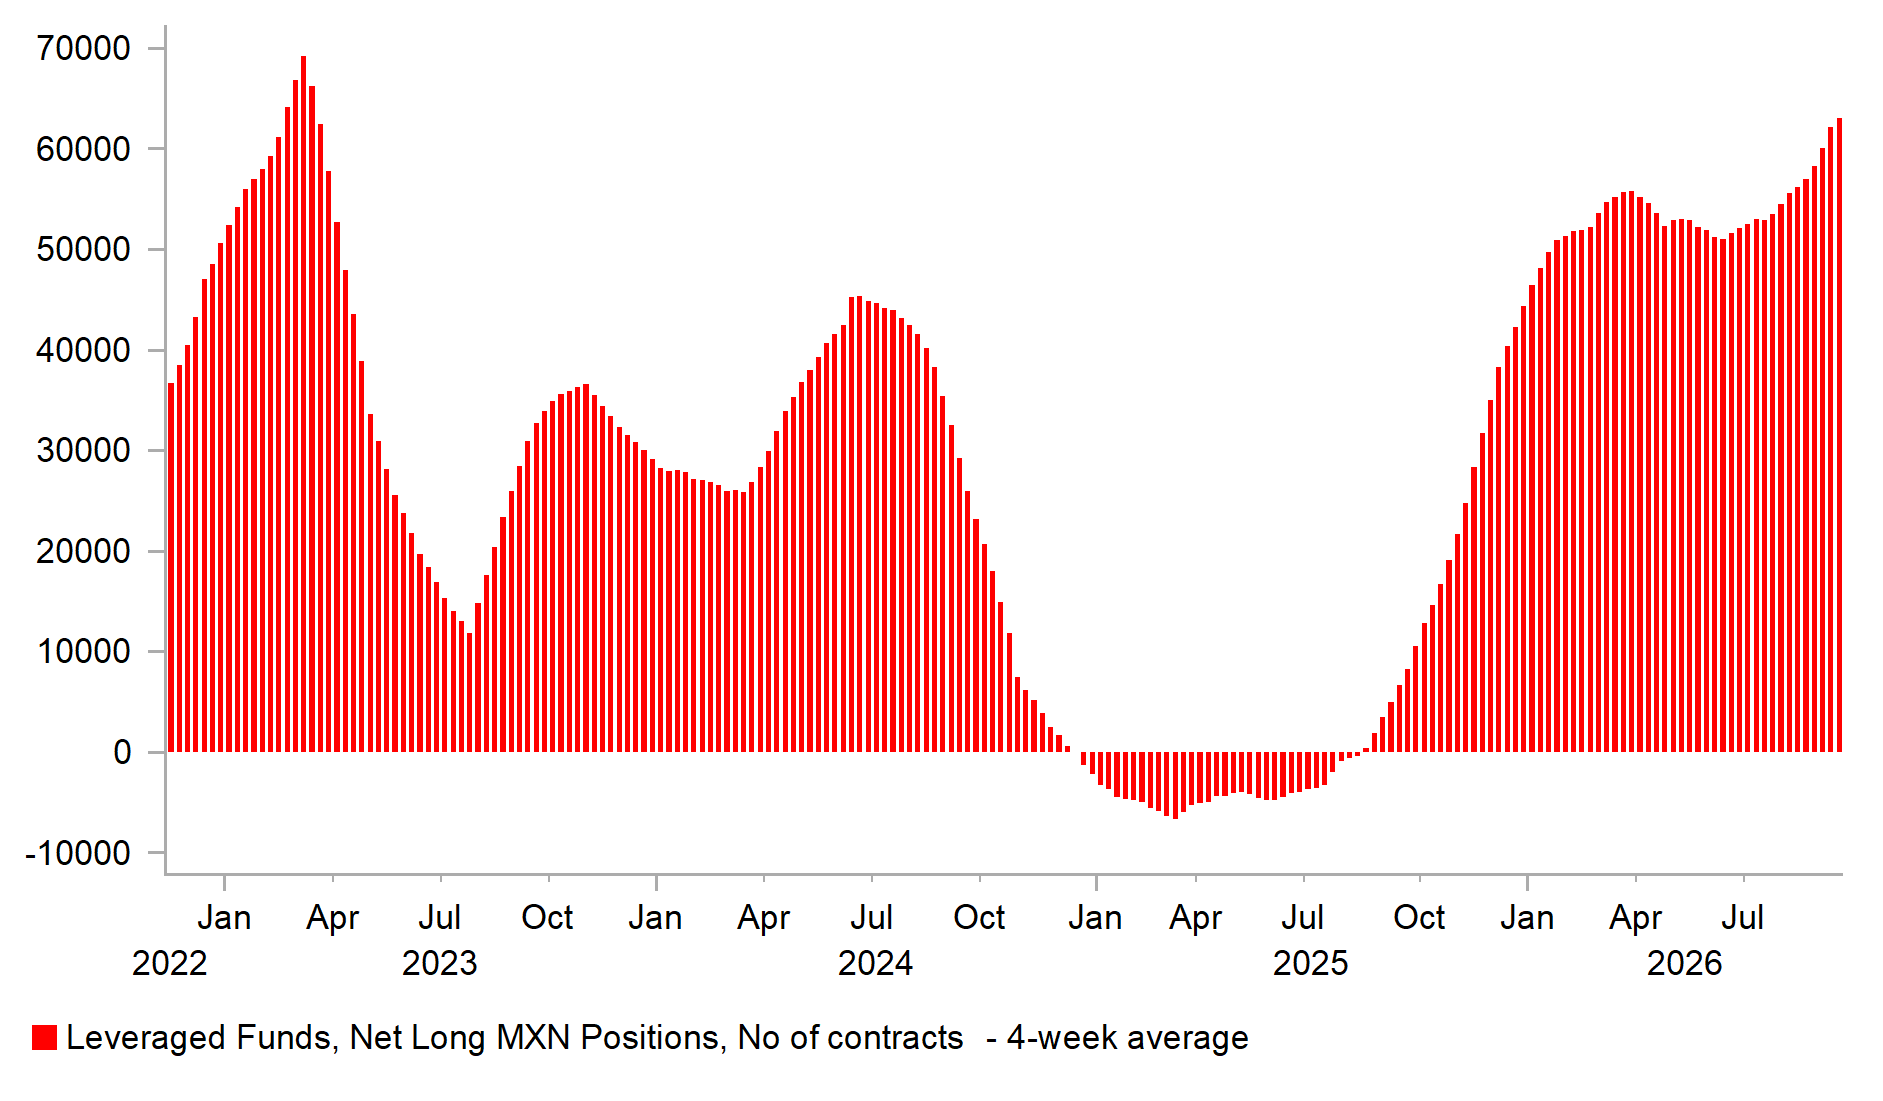
Since the middle of September USD/MXN has now jumped 8% and is the worst performing LatAm currency since the start of September. IMM positioning data explains why MXN is suffering. The latest data shows Leveraged Funds’ long position at the highest level since the start of 2023. Long MXN has been a popular trade this year – while there are LatAm currencies offering greater carry, the added protection of a positive terms of trade from higher energy prices had fuelled demand. 1mth Implied volatility in just over a week has surged from 7.5 to 12.2, the highest since the end of March as these positions are now likely being squeezed from the market.
LatAm more widely suffered yesterday. The Brazilian real had until yesterday held in well with expectations of a Lula victory in the election diminishing helping support the real. The first round of the elections take place on Sunday. One recent poll (Atlasintel) had Lula on 45% and Bolsonaro on 42% in the first round and then even on 48% in the run-off.
There are signs of liquidation of risk in other areas of the markets as well. The weekly MoF cross border flow data from Japan, released yesterday, revealed the third week of Japanese equity sales by foreign investors last week. Sales totalled JPY 362bn last week and JPY 6,825bn over the three weeks. That was the largest 3-week selling since March after the start of the conflict in the Middle East. This risk aversion could well have further to go. In G10, the Swiss franc and the yen were the top performing currencies yesterday and those moves could extend further.
MXN LONG LEVERAGED POSITIONS HAD REACHED NEW MULTI-YEAR HIGH
Source: Bloomberg, Macrobond, MUFG Research
KEY RELEASES AND EVENTS
Country | BST | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
EZ | 10:00 | CPI (MoM) | (Sep) | 0.5% | 0.4% | !!! |
EZ | 10:00 | CPI (YoY) | (Sep) | 3.7% | 3.2% | !!!! |
EZ | 10:00 | Core CPI (MoM) | (Sep) | - | 0.2% | ! |
EZ | 10:00 | Core CPI (YoY) | (Sep) | 2.5% | 2.4% | !!! |
US | 13:30 | Nonfarm Payrolls | (Sep) | 89K | 162K | !!!!! |
US | 13:30 | Unemployment Rate | (Sep) | 4.1% | 4.1% | !!!!! |
US | 13:30 | Average Hourly Earnings (MoM) | (Sep) | 0.3% | 0.3% | !!!! |
US | 13:30 | Private Nonfarm Payrolls | (Sep) | 82K | 127K | !! |
US | 13:30 | Average Hourly Earnings (YoY) (YoY) | (Sep) | 3.10% | 3.1% | !!! |
US | 13:30 | Manufacturing Payrolls | (Sep) | 10K | 16K | ! |
US | 13:30 | Average Weekly Hours | (Sep) | 34.3 | 34.4 | ! |
US | 15:00 | Factory Orders (MoM) | (Aug) | 0.1% | 0.9% | !! |
US | 19:00 | Total Vehicle Sales | (Sep) | 16.30M | 16.80M | ! |
Source: Bloomberg & Investing.com