
Euro sell-off reinforced by intensifying fears over fiscal contagion
EUR: Fears over fiscal contagion trigger broad-based sell-off
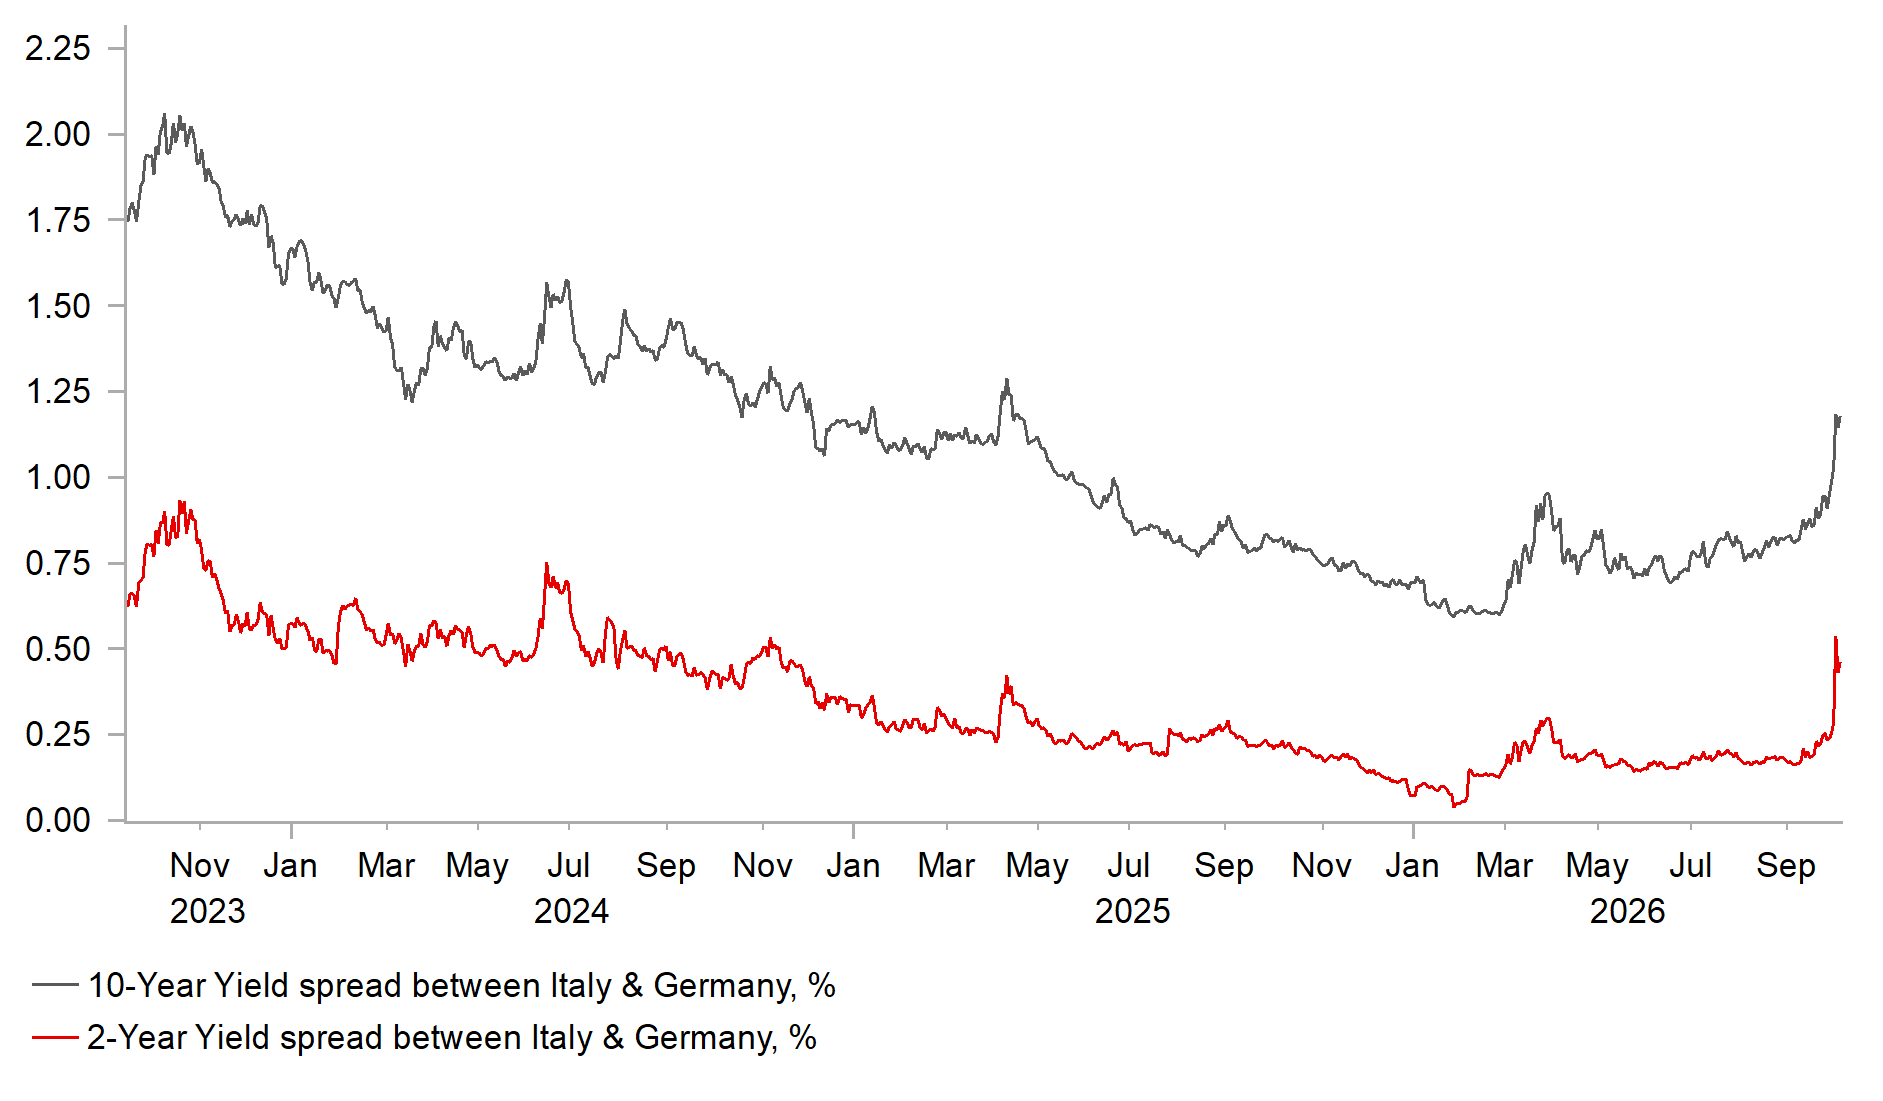
The euro has continued to weaken at the start of this week driven by intensifying fears over the destabilizing financial conditions in the euro-zone triggered by the sharp sell-off in Franch government bonds. It has encouraged a broad-based softening of the euro which has fallen to fresh year-to-date lows overnight against the US dollar and yen at 1.1161 and 176.41 respectively. It follows the ongoing sell-off in French government bonds at the end of last week when the 10-year yield almost hit 5.0% on Friday. The yield spread over German Bunds has blown to just over 140bps which is almost 60bps wider than before the summer. The increasingly rapid sell-off is adding to sense of crisis in the French government bond market. At the same time, market participants are watching closely to see if there further signs of contagion in the region. It was notable at the end of last week that Italina government bonds were also negatively impacted even at the short-end of the curve. The 2-year yield spread between Italian and German government bonds has widened by around 20bps. The unfavourable developments have triggered fears over the re-emergence of fragmentation risks in the euro-zone that could impede the transmission of monetary policy.
The unwanted tightening in financial conditions has already encouraged market participants to scale back expectations for further ECB rate hikes in response to the energy price shock. President Lagarde stated last week that higher long-term borrowing costs would dampen growth and inflation in the euro-zone implying that they could have less to do with the policy rate. The yield on the 2-year German government bond dropped sharply at the end of last week and now stands almost 30bps below the recent high from the end of last month. Market pricing for ECB hikes has moved more int line with our own forecast for two further hikes which could still prove too aggressive if the re-emergence of fragmentation risks intensify. There is also building speculation that the ECB may have to take further policy action to ease contagion risks by slowing down QT, and/or even utilizing their Transmission Protection Instrument (TPI) for the first time. It was created to counter unwarranted and disorderly market moves that disrupt the monetary policy transmission in the euro-zone. However, a decision to utilize the TPI would create the impression that the ECB is helping governments to finance their deficits. As such, the ECB would only decide to purchase government bonds through the TPI if the purchases are temporary, and governments take action as well to tighten fiscal policy to restore investor confidence.
The latest budget plans announced last week by the French government failed to stabilize the French bond market. Prime Lecornu has laid out budget plans for next year that target narrowing the budget deficit to 5.0% of GDP from around5.4% of GDP this year including EUR54 billion of fiscal tightening measures. However, France’s budget watchdog has warned that weak growth could again scupper plans to narrow the budget deficit to 5.0% of GDP similar to this year. Furthermore, it remains unclear if the fiscal tightening measures will be adopted given the government lacks a majority. The close proximity of next year’s presidential elections held in April also adds to investor uncertainty over the fiscal and political outlook in France. On the plus side, National Rally leader Marine Le Pen has indicated that she may refrain from trying to topple the government and back their budget plans. Having the budget in place is viewed as in Le Pen’s interest. It would be easier to make swift legislative changes should she win the election, rather than having to deal with an emergency situation. She has also stated that if elected she would propose a referendum to create a golden rule on deficits to ensure that appropriate fiscal tightening measures are adopted. She plans to lay out more details of her fiscal proposals later this month having offered little detail on her objective to find EUR125billion of cuts. With no easy way out in the near-term, the euro can weaken further in the near-term, we recommended a short EUR/JPY trade idea in our latest FX Weekly report (click here) on top of our existing long USD/SEK trade idea.
WATCHING FOR CONTAGION FROM FRENCH GOVT. BOND SELL-OFF
Source: MUFG Research, Macrobond, Bloomberg
KEY RELEASES AND EVENTS
Country | BST | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
DE | 08:45 | German Buba President Nagel Speaks | - | - | - | !! |
FR | 08:50 | French Services PMI | (Sep) | 51.4 | 48.0 | !! |
EU | 09:00 | Services PMI | (Sep) | 53.0 | 51.6 | !! |
EU | 09:00 | ECB's Lane Speaks | - | - | - | !! |
GB | 09:30 | Services PMI | (Sep) | 51.7 | 52.5 | !!! |
EU | 10:00 | ECB's Schnabel Speaks | - | - | - | !! |
US | 15:00 | ISM Non-Manufacturing PMI | (Sep) | 55.1 | 55.4 | !!! |
Source: Bloomberg & Investing.com