
USD & GBP benefitting from building fiscal & political risks in euro area
USD: FOMC minutes indicate that Fed is not in a rush in hike again this month
The major foreign exchange rates have remained relatively stable overnight with the dollar index continuing to trade close to year-to-date highs. The US dollar has continued to trade at stronger levels even as the US rate market has pared back expectations for Fed rate hikes highlighting that recent gains have been driven more by negative developments overseas. The US dollar has been benefitted by building concerns over fiscal and political risks in the euro area. After narrowing earlier this week, yield spreads between French and German government bonds have rewidened back out over the last 24 hours encouraging a stronger US dollar. We outlined our thoughts in more detail on the potential impact for the euro from another fiscal shock in the euro area (click here). Those concerns have helped to dampen the negative impact for the US dollar from market participants paring back expectations over the timing and scale of future Fed hikes. After hitting a high of 4.96% at the end of last months, the 2-year US Treasury yield has since dropped back by almost 20bps encouraged by the recent run of softer US data releases (PCE deflator report for August and NFP report for September) alongside relatively cautious comments from the Fed’s leadership signalling there is not an urgent need to hike rates again as soon as this month. In response the US rate market is now only pricing in around 5bps of hikes for this month compared to around 10bps at the end of last month.
The release overnight of the minutes from the last FOMC meeting in September when the Fed hiked rates for the time in response to the energy price shock also gave no sense of urgency to push for a hike again as soon as this month. “Many” Fed officials viewed the decision to hike rates last month on “risk management grounds” as they felt it was necessary to take out some insurance against the possibility that demand is stronger than expected and/or supply driven inflation proves to be more persistent. “Some” officials noted that the “AI build-up could cause aggregate demand to outpace aggregate supply”. However, only “several officials” thought that policy might not be restrictive or materially restrictive while “many” judged that financial conditions were broadly favourable. Participants indicated that they would approach each meeting “with an open mind and decisions at future meetings would depend on incoming information and its implications for the outlook and balance of risks”. Overall, the minutes were more consistent with the Fed’s plans for one or two more hikes rather than current market pricing for three to four more hikes. Market participants will now listen closely to comments today from Fed Governor Waller.
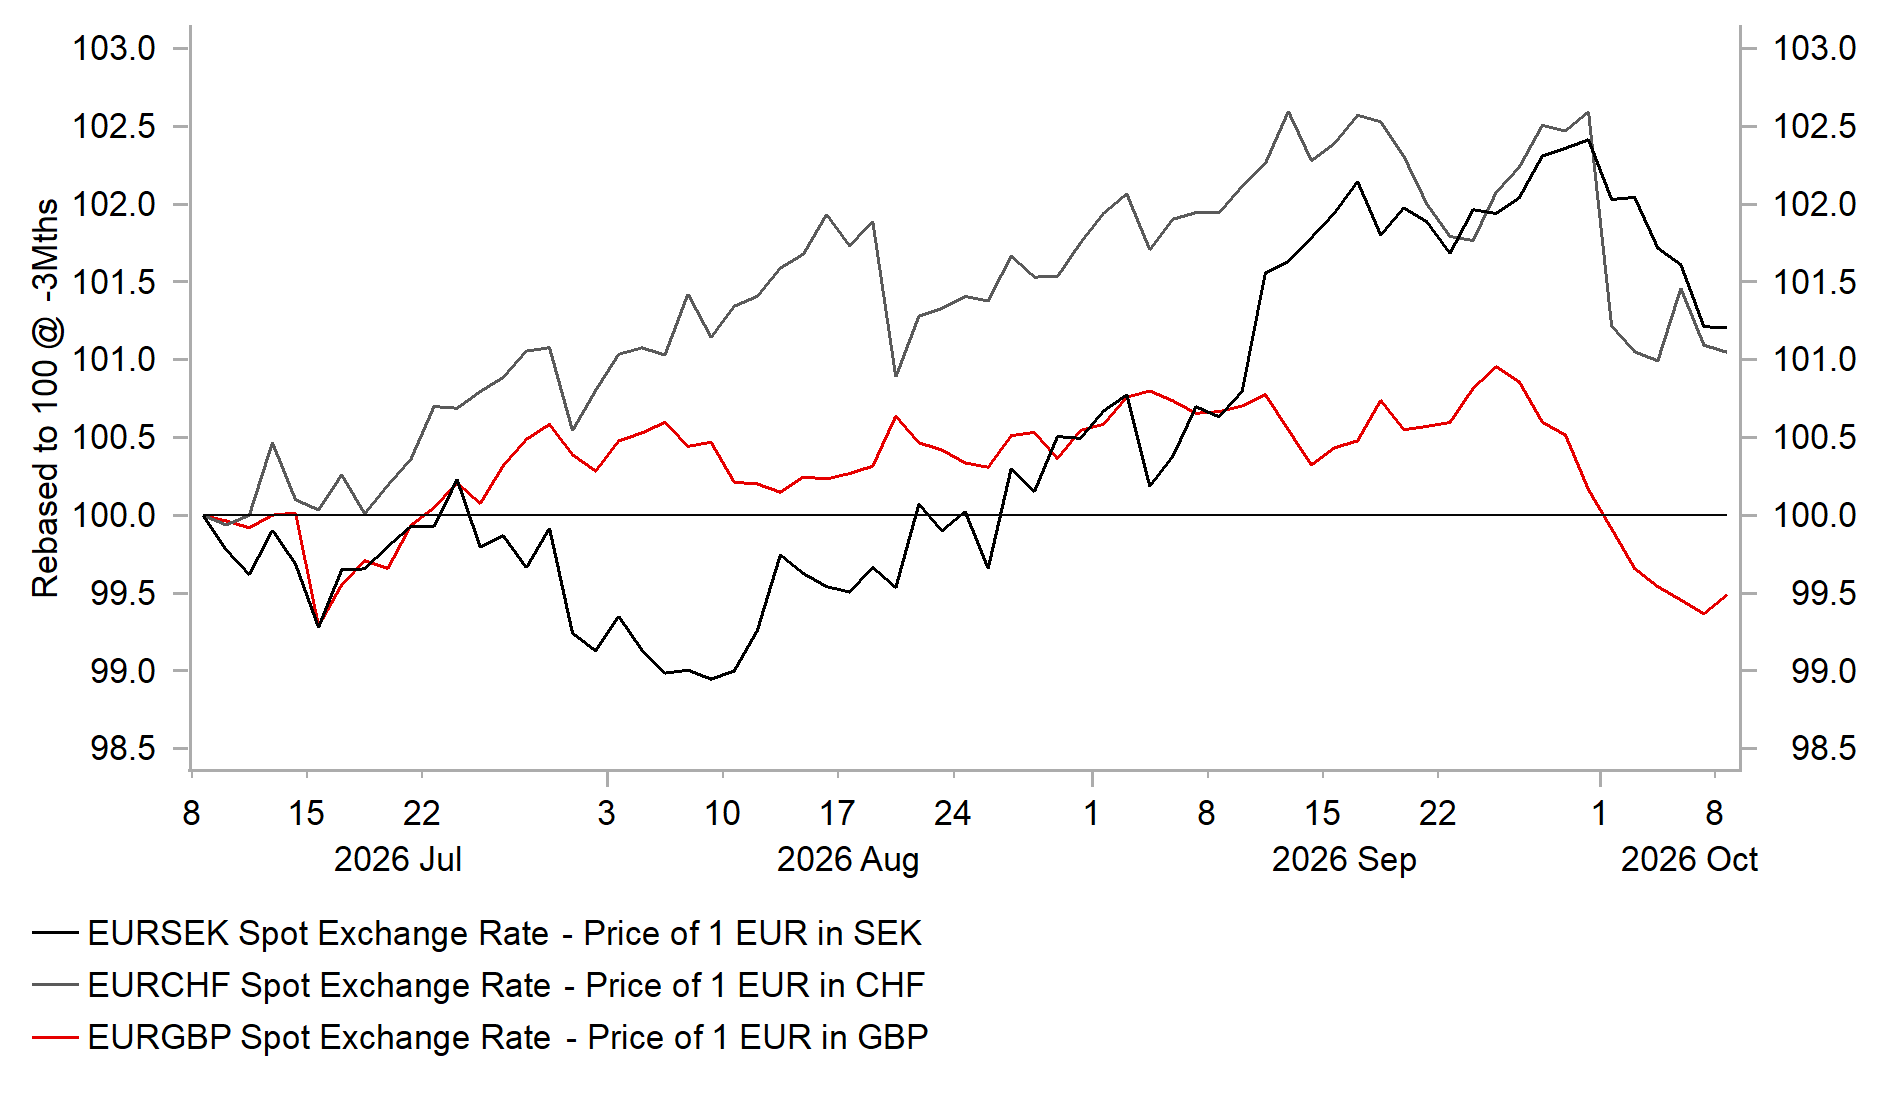
EUR SELL-OFF HAS BROADENED OUT THIS MONTH
Source: MUFG Research, Macrobond, Bloomberg
GBP: Fresh year-to-highs against EUR where fiscal concerns are more acute
The pound has strengthened sharply against the euro since the end of last month as the euro sell-off has broadened out. It has resulted in EUR/GBP falling from just above the 0.8600 to a fresh year-to-date low yesterday of 0.8448. EUR/GBP is moving back closer to levels that were in place prior to President Trump’s Liberation Day tariffs announcement back in April of last year when it was trading between 0.8200 and 0.8400 between September 2024 and March 2025. Negative development in the euro-zone have boosted the relative appeal of the pound. While fiscal concerns are also in focus in the UK with 10-year Gilt yields hitting their highest levels since prior to the Global Financial Crisis in 2007, they are not as acute as in France currently. Media reports have suggested that the Labour government is well aware of challenging global bond market conditions ahead of this month’s budget scheduled for 28th October which is encouraging them to play it safe as they seek to limit the risk of negative market reaction. A development that would help to ease downside risks for the pound.
At the same time, the BoE is moving closer to joining other major central banks by tightening policy. There is a heavy schedule of BoE speakers today including Governor Bailey. Market participants will be listening closely to assess the likelihood of the BoE hiking next month. While bond yields are contributing to tighter financial conditions, e still expect the BoE to finally begin to lift their policy rate for the first time in November, although guidance over the need for further hikes is likely to remain cautious.
KEY RELEASES AND EVENTS
Country | BST | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
GB | 09:30 | BOE Credit Conditions Survey | - | - | - | !! |
US | 09:30 | Fed Waller Speaks | - | - | - | !! |
EU | 11:00 | ECB's Lane Speaks | - | - | - | !! |
GB | 11:30 | BoE MPC Member Pill Speaks | - | - | - | !! |
EU | 12:30 | ECB Publishes Account of Monetary Policy Meeting | - | - | - | !! |
GB | 13:15 | BoE Gov Bailey Speaks | - | - | - | !!! |
US | 13:30 | Initial Jobless Claims | - | 200K | 197K | !!! |
Source: Bloomberg & Investing.com