
Any FOMC rate hike doubts put to bed by CPI & Waller
USD: 2-year surges providing renewed momentum for the dollar
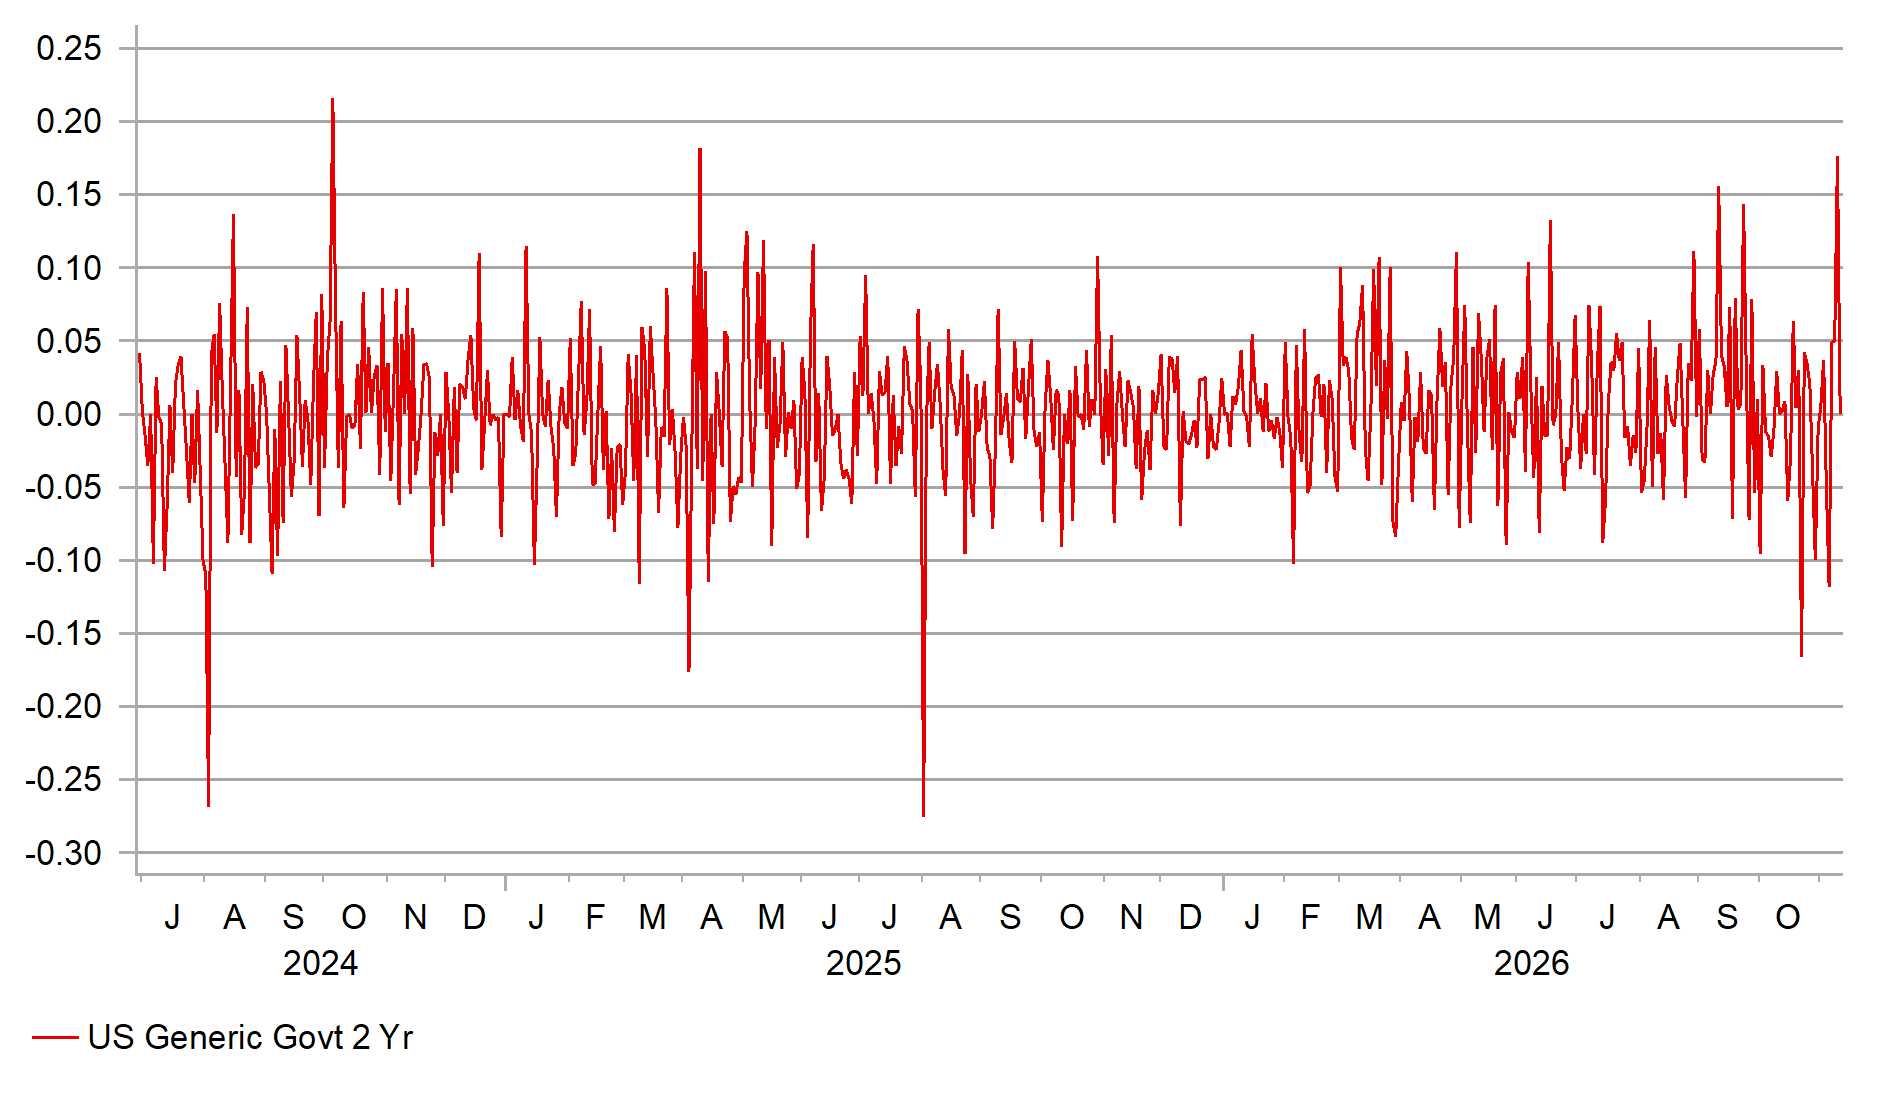
We didn’t think we would have a near 20bp move in the 2-year yield yesterday and while we can quibble about the justification (we will a little) the move serves as an important reminder – fundamentals matter! The focus had very much shifted to the political fallout and potential AI consequences of the mid-term election results but a stronger than expected CPI print that followed hawkish comments from Fed Governor Waller were enough to prompt the biggest jump in the 2-year UST bond yield since it was matched in April 2024 (Liberation Day). The previous bigger move was back in October 2024. That was the day of a blowout NFP that prompted a rethink by the markets over its pricing of a 50bp cut at the November meeting. The Fed cut by a smaller 25bp at the FOMC meetings that followed.
On this occasion the market rethink is to consider the prospect of a 50bp hike. This is only now being considered because of Waller’s comments prior to the CPI report rather than the CPI report itself. Waller’s comment that a stronger CPI print may warrant a 50bp hike has sparked a debate over whether Waller had knowledge of the CPI print. If he did, then there was intent in his comment to try and steer the market in the direction it has now gone. The OIS market is now partially pricing the risk of a 50bp hike on 9th December. Waller makes the point that the sticky inflation and energy risks warrant the reversal of the 75bps of cuts and hence why wait two meetings to do that.
In regard to Waller’s knowledge, I guess in a way we may never know but taking the publicly available information on procedure, the Office of Management and Budget manages and issues statistical policy directives and states clearly that information on data releases are strictly limited to a small number of designated officials within the producing agency. So our assumption is that when Waller spoke (in London 4.5hrs prior to the CPI release) he did not know the data. Still, he’s certainly hawkish and along with Fed President Logan who also called for “more rapid rate increases” means there may well be FOMC members pushing for a more aggressive response in December.
We remain sceptical of the need to hike by 50bps at this stage and suspect the majority will see the better risk-reward in going by 25bps. We still have another payrolls report (but no further CPI prints, although it’s the day after) before the FOMC meeting and a strong print plus a rebound in crude oil after the recent sharp drop would be one scenario of a possible more aggressive hike. It’s a scenario that might add to the reasons for President Trump to push for a deal with Iran to reopen the Strait of Hormuz and end the conflict.
It’s still more a risk than a core view but it would alter the current balanced expectations in the markets across key central banks and shift rate hike expectations much more in favour of the dollar that would likely prompt a further lurch lower in EUR/USD and bring levels below the 1.1000-level into play.
BIGGEST JUMP IN THE 2-YEAR YIELD SINCE LIBERATION DAY IN 2025 AND BEFORE THAT OCTOBER 2024
Source: MUFG Research, Macrobond, Bloomberg
JPY: JGBs sell off but individuals buying picks up notably
The yen weakened sharply yesterday in response to the US inflation data and USD/JPY has returned closer to the 160-level, above which intervention becomes a much greater prospect. The JGB market has seen a heavy sell-off as well in response to the UST bond market move yesterday although it is noticeable that there has been very little steepening of the curve. 2s10s is 2bps steeper but 2s30s is flat. There continue to be signs that confidence in the JGB market has improved, no doubt helped by the more active BoJ and the general consensus that within one or two hikes, the BoJ would be at the neutral policy rate. The move today followed a JGB auction yesterday that recorded a bid-to-cover of 3.36, slightly weaker than the 12mth average. Nonetheless, sentiment has certainly improved and there was further evidence of that today with the FT reporting of a strong pick-up in demand for JGBs amongst Japanese households. This could be a significant point in a potential gradual shift in flows reflecting the better returns available domestically. With inflation more elevated and now the BoJ formally confirming the achievement of the 2% inflation goal, households have to focus more on ensuring their savings are protected in real terms. Historically that required investing abroad, but now domestic assets offer a choice. Data in September revealed that 45% of households’ USD 16trn of household assets is parked in cash deposits (USD 7.1trn).
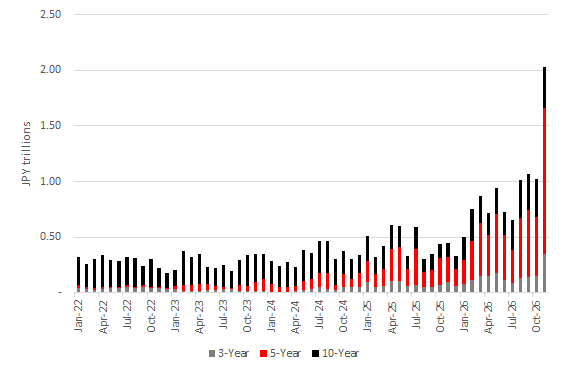
The data confirming this pick-up in JGB buying by Japanese households comes from the MoF. The MoF has an entire portion of its website dedicated to JGBs for individuals and issuance data there shows a marked pick-up in issuance to individuals with the November total for 3,5 and 10-year totalling JPY 2,026bn, the largest single-month total. In August there was a new record of JPY 1,108bn with another record in September underlining the notable pick-up in recent months. This coincides with Finance Minister Katayama earlier this year calling on investors to invest more in domestic assets. There is also growing speculation that the government will soon make changes to incentivise JGB buying by including individual JGB holdings in tax-free NISA accounts and/or removing these holdings from inheritance tax.
Early signs of a shift in flows perhaps, and the more examples of this we start to see the more compelling the case will become of a more sustained turnaround in the multi-year trend of yen weakness. With intervention likely halting the prospects to the upside, and confidence in the BoJ improving, the risks certainly look more skewed to yen strength over the medium term.
ISSUANCE OF JGBS TO INDIVIDUALS IN JAPAN
Source: Ministry of Finance Japan & MUFG Research
KEY RELEASES AND EVENTS
Country | GMT | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
GE | 08:20 | ECB’s Nagel Speaks | - | !! | ||
EZ | 09:45 | ECB President Lagarde Speaks | - | !!!! | ||
US | 10:00 | OPEC Monthly Report | - | !! | ||
US | 12:00 | MBA Mortgage Applications (WoW) | - | -1.20% | ! | |
US | 16:00 | Thomson Reuters IPSOS PCSI | (Nov) |
| 45.18 | ! |
CA | 16:00 | Thomson Reuters IPSOS PCSI | (Nov) |
| 46.61 | ! |
Source: Bloomberg & Investing.com