
USD hits fresh year-to-date highs on hawkish repricing of Fed expectations
USD: Market expectations for faster Fed hikes lifts USD
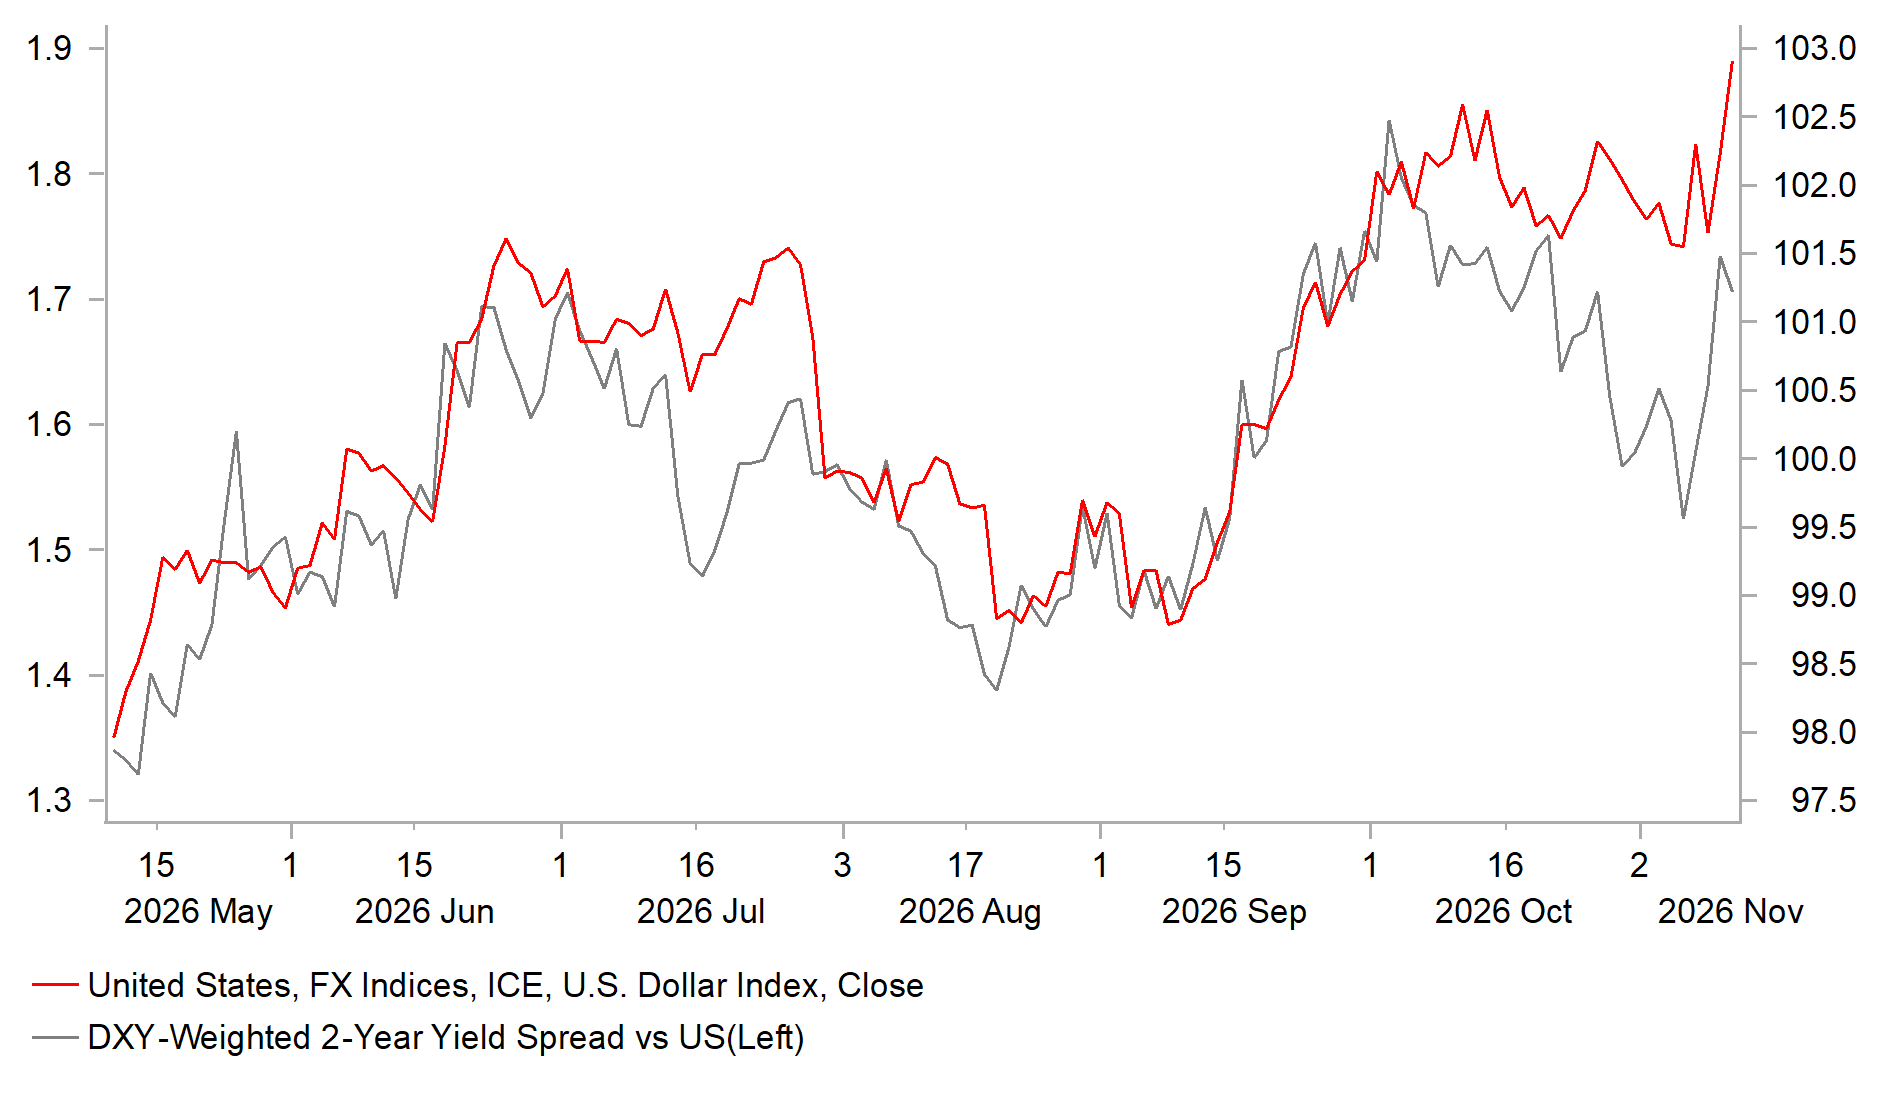
The US dollar has continued to strengthen overnight resulting in the dollar index hitting a fresh year-to-date high of 103.08. The US dollar’s renewed upward momentum has been encouraged by expectations that the Fed is likely to speed up the pace of rate hikes in response to the recent run of stronger US inflation data. The yield on the 2-year US Treasury has jumped high by around 33bps from the low at the end of last week although still remains below the peak set in September at 4.96%. A 25bps rate hike at the next FOMC meeting in December is now fully priced in, and market participants have moved further to price in small probability of larger 50bps hike. There are currently around 28bps of hikes priced by December, and 43bps of hikes priced by the following meeting in January indicating that even if the Fed hikes by 25bps in December it is now expected to quickly follow up with another 25bps hike at the start of next year.
Market expectations for the faster pace of Fed rate hikes were encouraged by hawkish comments this week by Fed officials including Governor Waller who stated he would consider voting for a larger 50bps hike in December, and Dallas Fed President Lorrie Logan who is a voting member this year stated that “the FOMC needs to implement at least two more 25bps rate increases” and that “it may be possible to move more rapidly this winter than the FOMC has moved this fall”. Chicago Fed President Austan Goolsbee who becomes a voting member next year also described the October CPI report as “another distressing report, borderline disturbing” particularly services inflation which has remained persistently high. When asked about the possibility of larger 50bps hike in December he stated that “everything is always on the table”.
There is a heavy schedule Fed speakers today including Cleveland Fed President Beth Hammack (voter this year), Fed Governor Michael Barr, Chicago Fed President Austan Goolsbee (voter next year), San Francisco Fed President Mary Daly (voter next year), and New York Fed President John Williams. Market participants will be listening closely to better assess both the risk of larger 50bps hike in December and likelihood of back-to-back hike sin December and January. The updated views of New York Fed President John Williams could carry more weight. He stated earlier this month that it is an “appropriate time to accumulate more information to help us determine what the appropriate stance of policy is to make sure we achieve a timely return to our 2% target”. While we don’t expect a larger 50bps hike to be delivered in December, it is more likely now that the Fed could hike rates back-to-back in December and January. A development that will encourage the US dollar to trade at stronger levels heading into year end. A sharp tightening of US financial conditions and/or ongoing drop in energy prices would likely be required to significantly push back against market expectations for faster Fed hikes at the current juncture.
FRESH YEAR-TO-DATE HIGHS FOR USD AS US YIELDS REBOUND
Source: MUFG Research, Macrobond, Bloomberg
JPY: Japan steps up verbal intervention as USD/JPY rises toward 160.00
The hawkish repricing of Fed rate hike expectations and stronger US dollar have resulted in USD/JPY rising back to within touching distance of the 160.00-level for the first time since the start of September. USD/JPY has now almost fully reversed the adjustment lower in September that was triggered by market expectations for BoJ to speed up the pace of rate hikes and media reports suggesting that the GPIF discussed over the summer increasing funds allocated towards domestic assets. The GPIF released their latest investment results for Q2 of FY2026 last week which revealed that there has been no significant shift in allocations yet. At the end of September 2026, pension reserves totalled JPY319.78 trillion of which 24.80% were held in domestic equities and 26.49% were held in domestic bonds. It compares to at the end of June 2026 when 24.48% of reserves were held in domestic equities and 25.59% held in domestic bonds.
With USD/JPY moving back towards pre-joint intervention levels from late July/early August, it has prompted Japanese officials to step up verbal intervention overnight to support the yen. Japan’s top currency official Atsushi Mimura stated overnight that “I have a strong impression that the currency moves over the past few days have been too fast”. He added that “it’s too early to forget what happened this summer”. It sends a strong signal that Japan is prepared to intervene again to support the yen which should help to limit further upside for USD/JPY beyond 160.00. However, it will be even more difficult to reverse the upward trend for USD/JPY right now with the USD strengthening broadly on the back of expectations for faster Fed rate hikes. If the rising risk of further intervention helps to stabilize USD/JPY while the US dollar continues to strengthen more broadly it could see non-USD yen crosses moving lower.
Dovish BoJ board member Toichiro Asada, who voted against the September hike, also spoke overnight stating that “I believe that the recent price increases have not necessarily been driven by demand factors” and considers “it necessary for the Bank to give consideration to the pace of any hikes”. It does not change our view that the BoJ to continue with the faster quarterly pace of hikes in December.
KEY RELEASES AND EVENTS
Country | GMT | Indicator/Event | Period | Forecast | Previous | Mkt Moving |
GB | 12:00 | NIESR Monthly GDP Tracker | (Oct) | 0.7% | !! | |
DE | 12:00 | German Current Account Balance n.s.a | (Sep) | 10.3B | !! | |
CA | 12:30 | Building Permits (MoM) | (Sep) | -4.0% | 8.8% | !! |
US | 13:30 | Initial Jobless Claims | - | 194K | 189K | !! |
US | 15:00 | Existing Home Sales | (Oct) | 3.89M | 3.99M | !! |
US | 15:00 | Fed Vice Chair for Supervision Barr Speaks | - | !!! | ||
US | 16:30 | Fed Goolsbee Speaks | - | !!! | ||
US | 18:10 | FOMC Member Daly Speaks | - | !!! | ||
EU | 21:30 | ECB President Lagarde Speaks | - | !!! | ||
US | 23:30 | FOMC Member Williams Speaks | - | !!! |
Source: Bloomberg & Investing.com