
JPY continues to trade on stronger footing alongside USD
JPY: Heightened intervention risk & BoJ policy normalization remain in focus
The yen has strengthened modestly overnight resulting in USD/JPY moving back closer towards the 158.00-level. The pair has been trading just below the 200-day moving at around 158.50 so far this month. The heightened risk of further intervention from Japan to support the yen is still helping to curtail upside for USD/JPY even as the US dollar continues to strengthen against other major currencies. Prime Minister Takaichi reiterated overnight when speaking to parliament that the US and Japanese finance ministers are still in close contact on foreign exchange, and that the yen was raised as an issue at the latest US-Japan Summit in general terms. However, she did add that the weak yen has both upsides and downsides. The yen has remained at stronger levels since the join US-Japan intervention in late July highlighting that is has proven effective at preventing further yen weakness in recent months.
At the same time, the yen has been deriving more support from building expectations for a faster pace of BoJ tightening. The Japanese rate market expects the BoJ to deliver another rate hike by year end in December and a cumulative total of around 75bps of additional tightening by the middle of next year. It follows the BoJ’s decision to deliver a hike last month, and signal that monetary policy has moved into a new phase indicating that a faster pace of hikes is likely to continue. BoJ Governor Ueda also spoke overnight in parliament where he stated that underlying inflation is very close to their goal and that it is very important to the price trend around 2.0%. In the current environment of broad-based US dollar strength, we expect the yen to continue to perform better against non-US dollar crosses. We recently recommended a short EUR/JPY trade idea (click here) to reflect building downside risks for the euro from heightened fiscal and political risks in the euro area. After peaking at 187.47 at the end of July, EUR/JPY has since dropped by around -5.5% falling to its lowest level in almost a year.
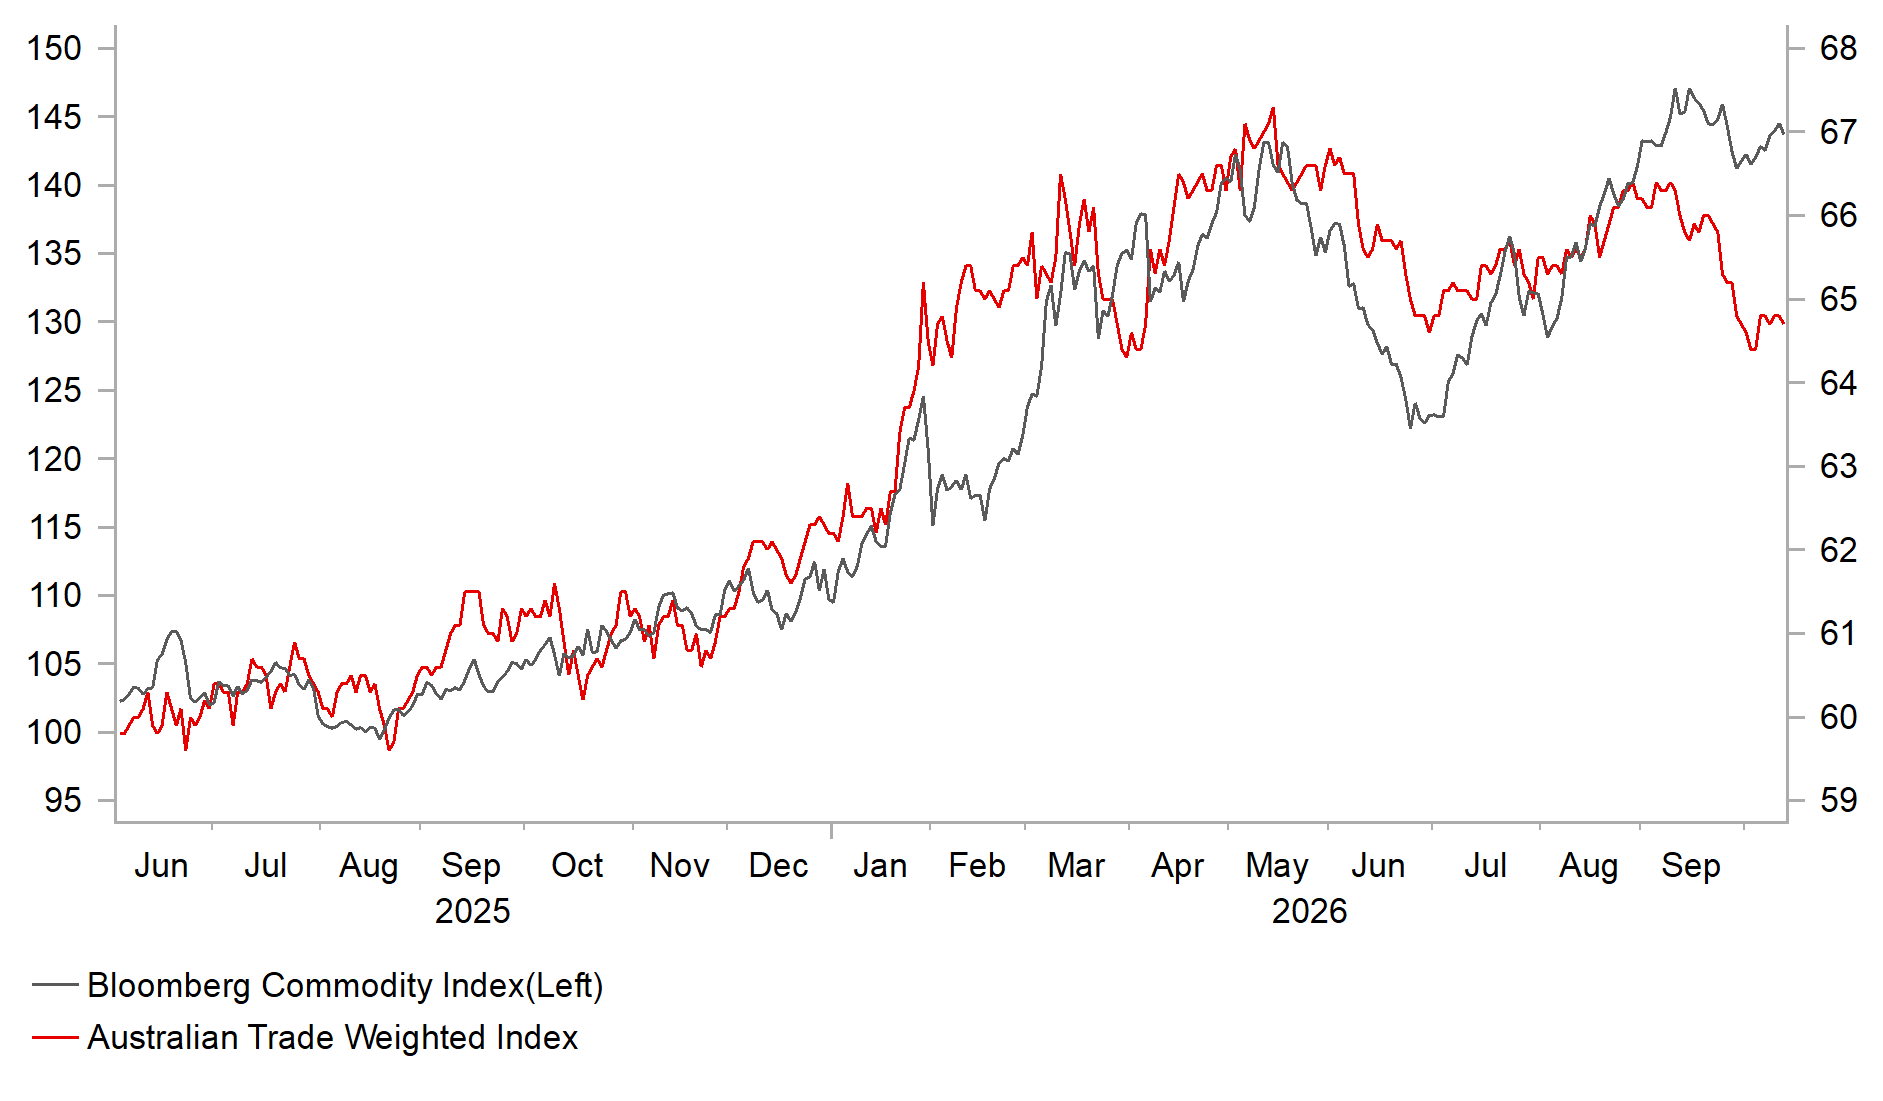
AUD SUPPORTED BY POSITIVE TERMS OF TRADE SHOCK
Source: MUFG Research, Macrobond, Bloomberg
AUD: Higher rates & resilient global growth continue to provide support
The main release overnight was the minutes from the latest RBA policy meeting in September when they raised the policy rate by 0.25 point to 4.60%. The minutes reinforced the message from the policy meeting that the RBA is prepared to hike rates further if required even though they have already lifted the policy rate by 100bps this year. It is currently the highest policy rate amongst G10 central banks which helped the Australian dollar to outperform in 2026 alongside the Norwegian krone. RBA officials displayed concern that the Australian dollar could weaken going forward if overseas central banks played catch up by increasingly moving to raise rates which could add to upside risks in Australia. The RBA also noted that they were also wary of the risk that falling house prices could have a larger effect on household spending than assumed which could strength the case for keeping rates on hold in Australia.
The outperformance of the Australian dollar also reflects the resilience of the global growth to the energy price shock. Tighter supplies and resilient demand have contributed to Bloomberg’s commodity price index trading close to year-to-date highs having increased by just over 30% so far this year. The still favourable external backdrop for the Aussie was highlighted by the IMF’s updated World Economic Outlook report released overnight which revealed another upward revision to global growth for this year by 0.1ppt to 3.1%. It was mainly driven by upward revisions to growth in Germany (+0.6ppt), Spain (+0.4ppt), the UK (+0.3ppt), and India (+0.6ppt). The IMF stated that the global economy is again proving resilient but warned that growth is uneven with rapidly narrowing margins of adjustment in the near-term. The IMF cited downside risks to global growth from: i) a prolonged stalemate or further escalation in the Middle East, ii) a reassessment of AI-related profitability and productivity prospects, and iii) fiscal and renewed trade tensions could further weaken growth. The IMF called on governments to implement credible fiscal adjustment plans.
KEY RELEASES AND EVENTS
Country | BST | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
US | 08:45 | Fed Waller Speaks | - | - | - | !! |
US | 11:00 | OPEC Monthly Report | - | - | - | !! |
US | 11:00 | NFIB Small Business Optimism | (Sep) | 98.1 | 98.7 | ! |
DE | 13:00 | German Current Account Balance n.s.a | (Aug) | - | 21.2B | ! |
US | 15:00 | Existing Home Sales | (Sep) | 3.95M | 3.98M | !!! |
GB | 17:00 | BoE MPC Member Dhingra Speaks | - | - | - | ! |
EU | 18:30 | ECB's Lane Speaks | - | - | - | !! |
Source: Bloomberg & Investing.com