
More volatile market conditions remains the key risk
USD: Energy & AI risks to volatility
G10 FX volatility is starting to turn lower again after the recent spike higher as the US dollar strengthened in response to the surge in sovereign bond yields. There has been a similar modest retracement in bond market volatility as well and if bond yields have settled around a new equilibrium then we could see volatility come down further in both rates and FX. However, the risks appear greater to us that we could still have further to go in this current spike in yields. The general consensus on the Middle East is that energy prices are unlikely to retrace and that the current status is likely to continue. But the risks now seem more skewed to a worsening of the crisis. The Houthis have shown no sign of letting up and is now reported to have attacked the Saudi Aramco headquarters in Dhahran and several other cities. Each day of increased attacks brings a greater risk of US involvement in support of Saudi Arabia that would likely prompt a further jump in energy prices. President Trump sees the Houthi attacks as trying to lift energy prices ahead of the US mid-term elections in November. The Israeli media has also reported that Netenyahu has been pushing President Trump to restart attacks on Iran ahead of the mid-term elections given Iran’s recent surge in attacks in the Strait of Hormuz. The US response to Israel was reportedly to “go ahead of prepare”. President Trump may see he has nothing to lose by showing action to halt rising energy prices by restarting attacks. An FT poll this week revealed the poor approval ratings of President Trump with his support suffering due to the economy. 68% disapprove of his handling of inflation and the cost of living. 59% disapprove on tariffs and trade; 57% on jobs and the economy. Most predictions now show a greater probability of the Democrats winning both the House and the Senate which will result in the final two years of Trump’s presidency involving Senate investigations into his conduct in the White House. An escalation of renewed attacks would likely see investors price in a more prolonged conflict that would see crude oil prices move toward the peak earlier this year. That would be the catalyst for another jump in long-term yields that would see broader volatility jump.
The FT poll also revealed the growing opposition in the US to AI with around two-thirds favouring binding federal rules for AI companies and a more cautious pace of development. The IMF WEO, released yesterday, highlighted the increased size of global excess savings that is likely feeding the AI boom that could unravel if investors begin to doubt the forward projections. In circumstances of higher global yields that prospect is a lot higher.
Inflation data from the US today is very important (see below) and that will shape the very near-term direction of rates and a softer print would help ease the broader risks but the current conditions and geopolitical backdrop still point to increased risks of more volatile financial market conditions that would, at least initially, be supportive of another leg stronger for the dollar.
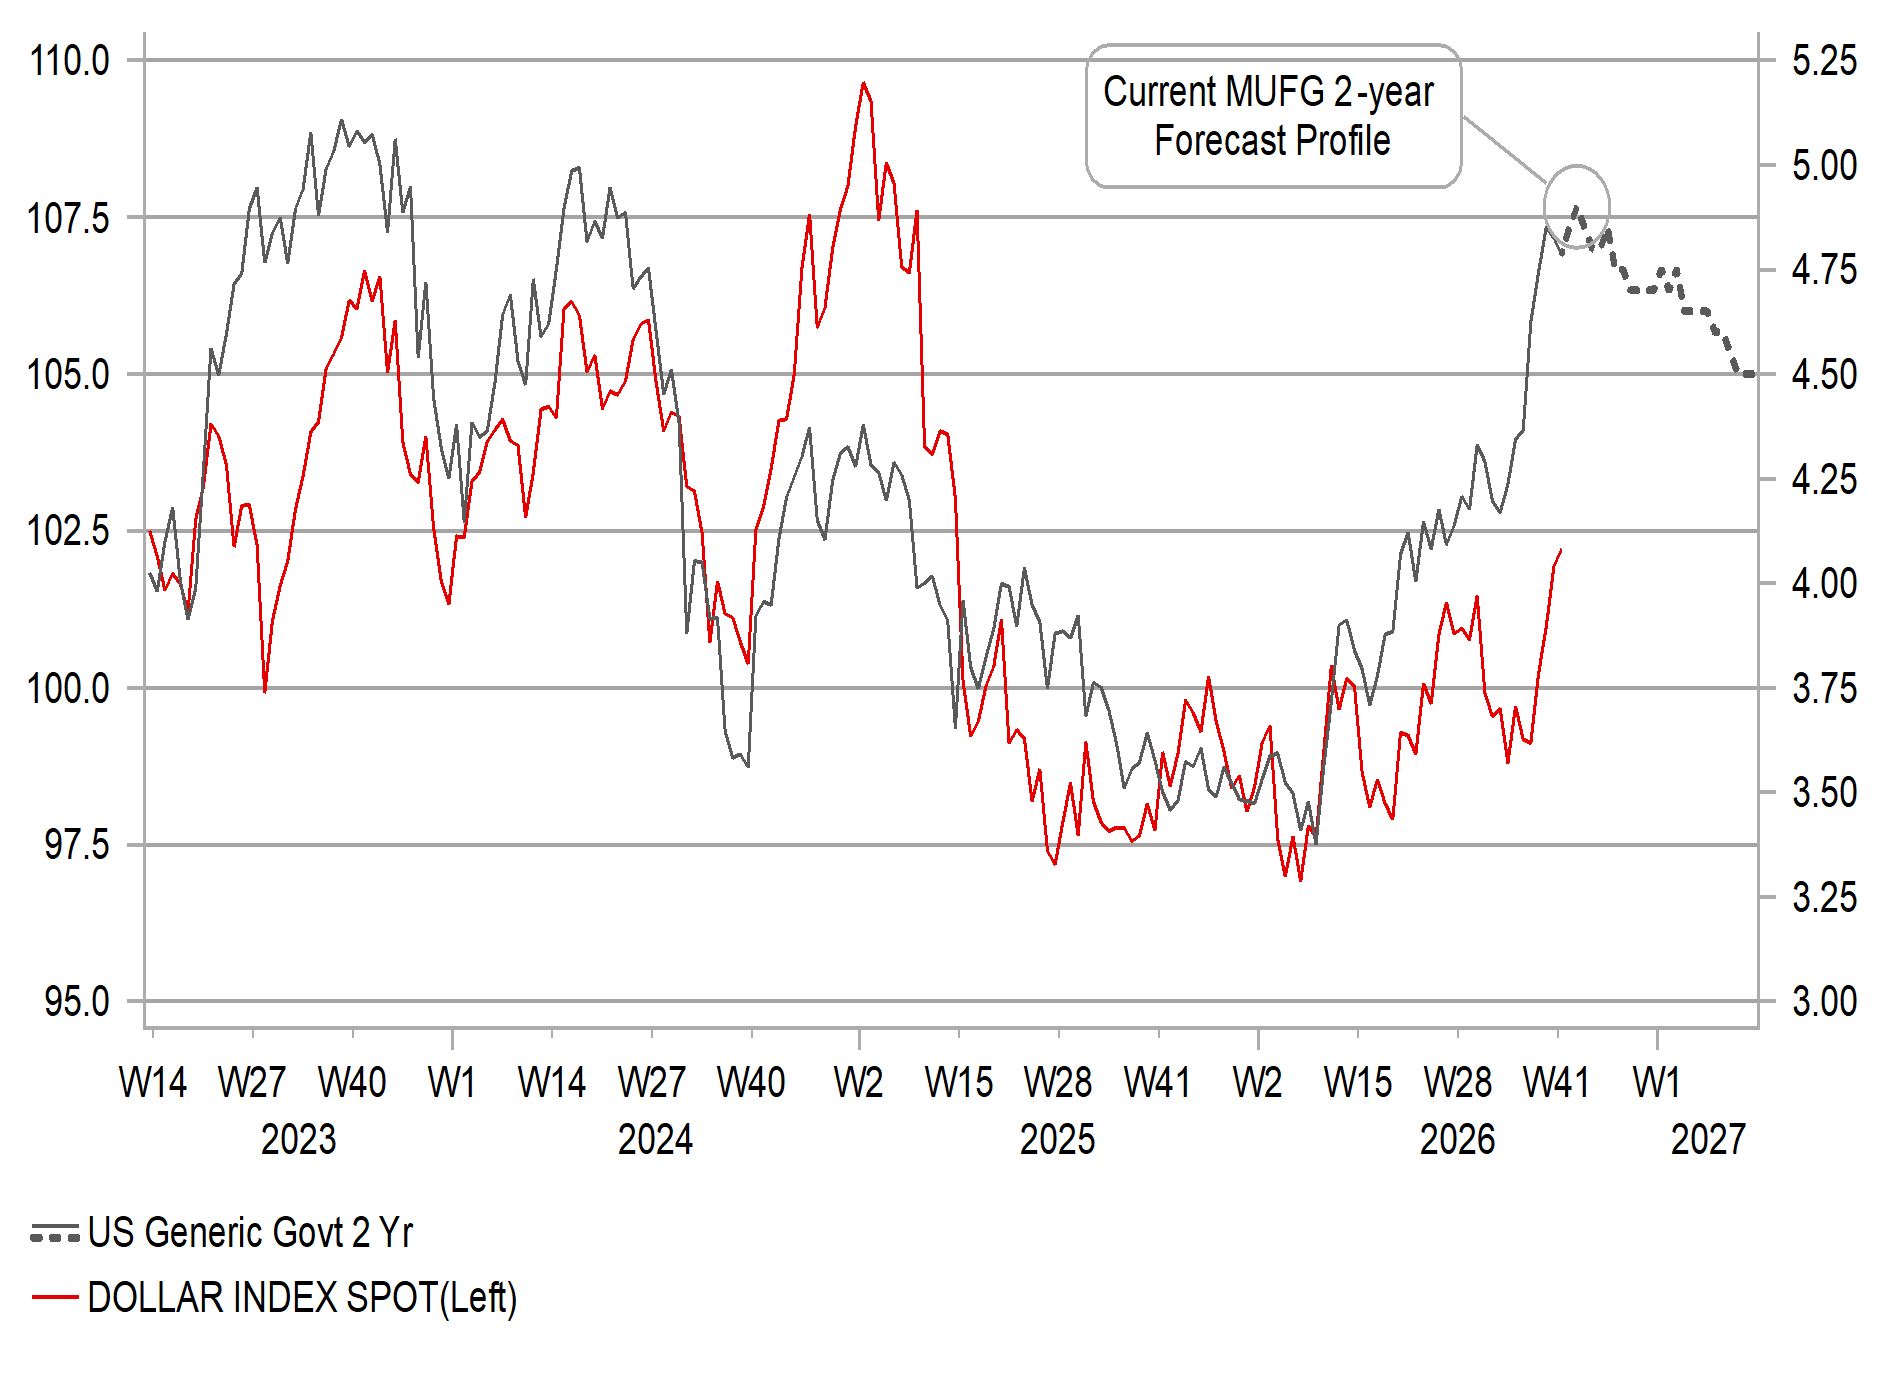
UPSIDE SCOPE FOR DXY TO 105-LEVEL BASED ON MUFG YIELD FORECAST
Source: MUFG Research, Macrobond, Bloomberg
USD: CPI data release a key momentum for rates & FX
The main macroeconomic event arrives today with the release of the September CPI data. Inflation risks ahead remains the dominant concern of central bankers given the extended period of elevated energy prices risks feeding more broadly into non-energy inflation. The Fed has already hiked and another hike is fully priced for December. A very strong report today could shift expectations forward. Currently an October hike is priced at a probability of close to 25%.
The consensus today is for the headline rate to pick up (0.4% to 0.6%) but for the core rate to slow (0.3% to 0.2%). It’s the expected 3.6% YoY headline rate that looks most problematic with risks that this energy-related impact will start to push up the core CPY YoY rate from the expected 2.5% in September. It’s understandable that precautionary rate hikes will be seen as sensible given the risks of pass-through.
Still, we remain sceptical that inflation pressures will continue to build and while we expect the Fed to hike again in December, we do not expect the Fed to deliver the two further rate hikes currently priced by the markets. The inflation backdrop doesn’t appear to be as bad as might have been expected when the conflict first started and if an assumption had been made that it would still be impacting energy supplies by the following October. Taking the PCE measure of inflation, the annualised 3mth change fell in August to the Fed’s 2.0% inflation target for the first time since July 2024. It’s only the third time since the retracement back lower after the global inflation shock that the 3mth annualised core PCE rate has fallen back to target. The most recent peak for core PCE on a 3mth annualised basis was in February at 4.27% and the rate has declined gradually since. There is little evidence of pass-through that likely reflects the fact that the non-AI economy in the US remains relatively weak.
If we project forward current market pricing for the Fed’s policy rate by the middle of next year and use the consensus inflation forecast, the implied real fed funds rate reaches 2.60%, not far from the peak restrictiveness seen following the global inflation shock. We don’t believe the Fed will need to raise rates to that level. Near-term though the Fed look set to hike again and any upside surprise in today’s data would likely trigger another rates sell-off and extend the dollar further stronger. Based on our 2-year UST bond yield projections, the DXY could certainly advance to the 105-level that would imply EUR/USD potentially falling below the 1.1000-level. A consensus CPI print today is unlikely to alter rate expectations much and a meaningful miss to the downside (0.0% m/m core) would be required to see a notable dollar sell-off.
KEY RELEASES AND EVENTS
Country | BST | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
EU | 09:00 | ECB's Elderson Speaks | - | - | - | !! |
EU | 09:30 | ECB President Lagarde Speaks | - | - | - | !!!! |
US | 10:00 | IEA Monthly Report | - | - | - | !! |
US | 10:40 | Fed's Bowman Speaks | - | - | - | !! |
US | 12:00 | MBA Mortgage Applications (WoW) | - | - | -4.2% | ! |
US | 13:30 | CPI (MoM) | (Sep) | 0.6% | 0.4% | !!!!! |
US | 13:30 | CPI (YoY) | (Sep) | 3.6% | 3.4% | !!!! |
US | 13:30 | Core CPI (MoM) | (Sep) | 0.2% | 0.3% | !!!!! |
US | 13:30 | Core CPI (YoY) | (Sep) | 2.5% | 2.4% | !!!! |
CA | 13:30 | Building Permits (MoM) | (Aug) | 2.9% | -17.3% | !! |
US | 14:30 | US Leading Index (MoM) | - | - | -0.1% | !! |
US | 16:00 | Cleveland CPI (MoM) | (Sep) | - | 0.2% | ! |
EU | 17:15 | ECB's Schnabel Speaks | - | - | - | !! |
US | 18:30 | Fed's Barkin Speaks | - | - | - | !! |
US | 19:00 | Beige Book | - | - | - | !! |
Source: Bloomberg & Investing.com