
USD strengthens ahead of FOMC meeting but gains modest so far
USD: Fed hike is expected now but US dollar strength has been modest so far
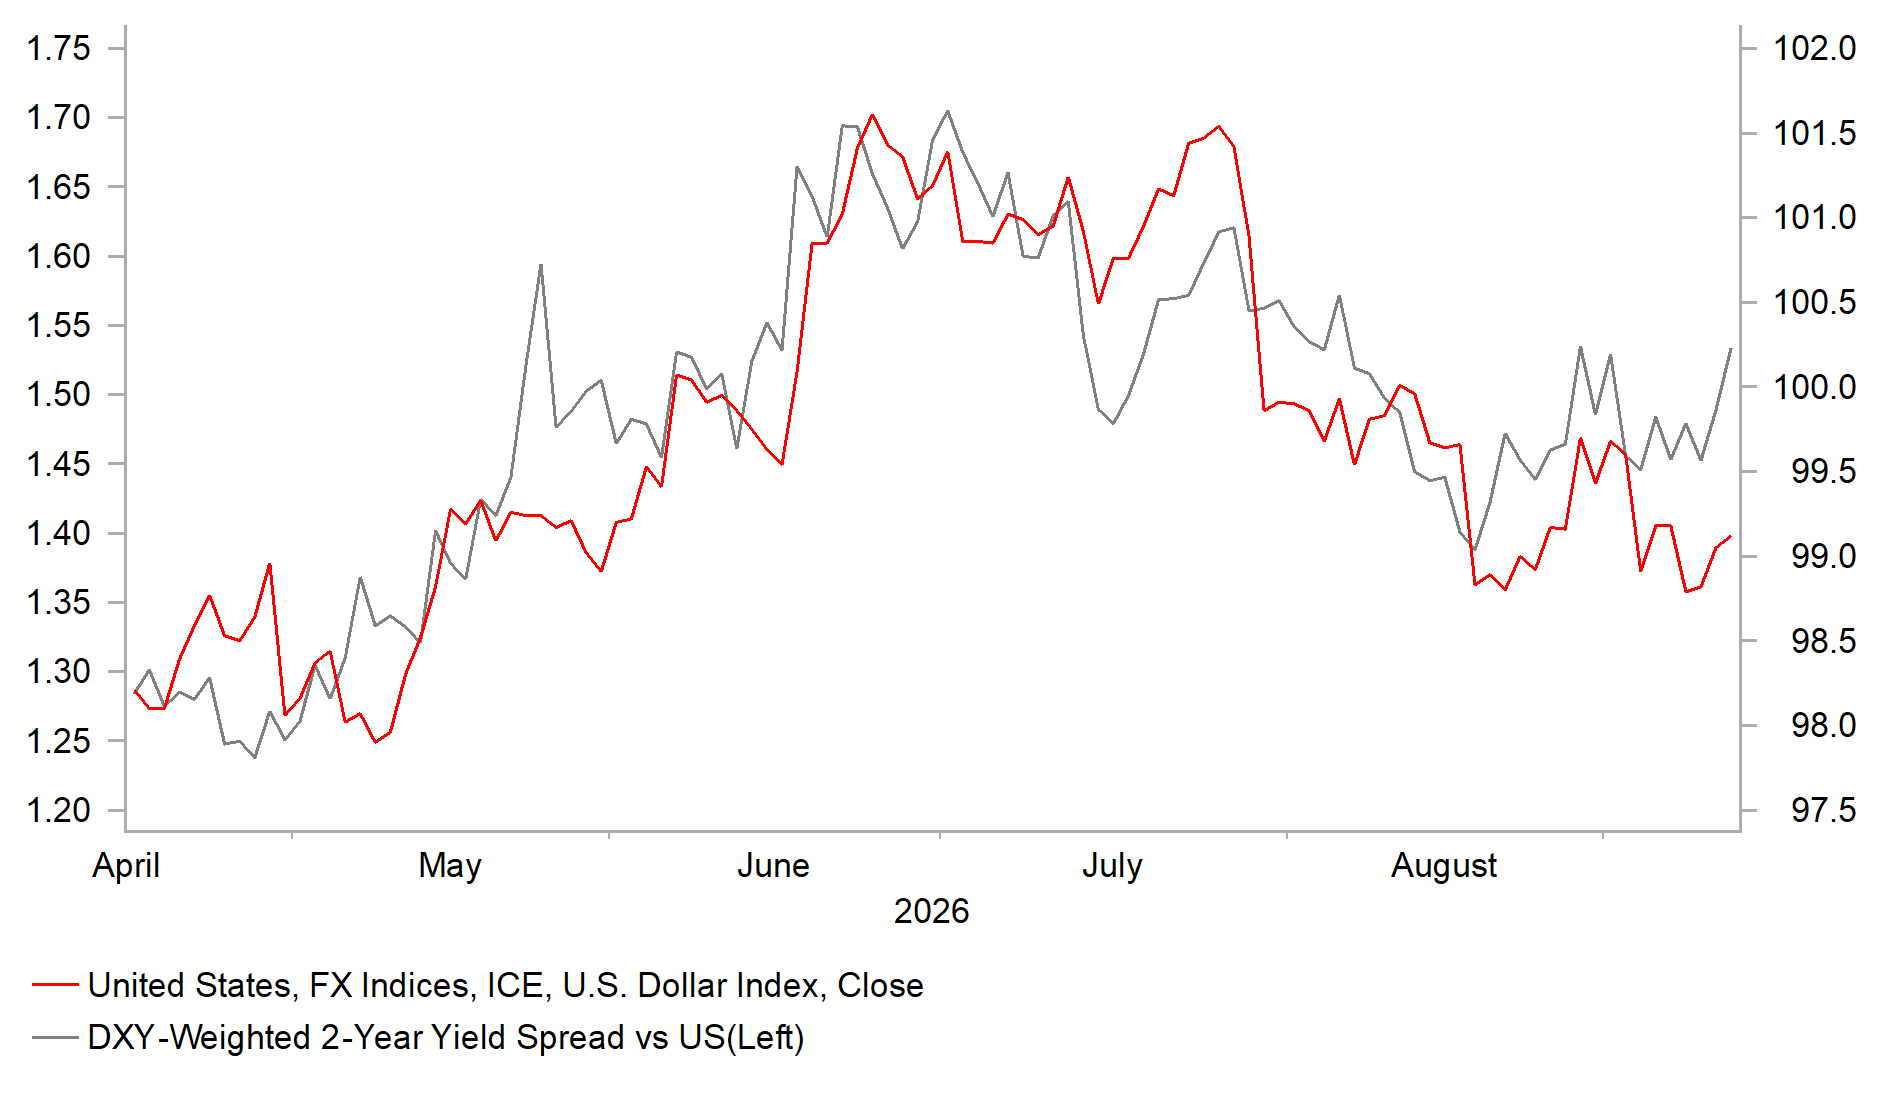
The US dollar has strengthened modestly at the start of this week encouraged by building expectations that the Fed will begin tightening monetary policy this week. It has helped to lift the dollar index back above support form the 200-day moving average at around 99.150. The US dollar has been boosted by the hawkish repricing at the short-end of the US yield curve triggered by stronger US inflation data last week. The 2-year US Treasury yield jumped higher by around 26bps last week as market participants moved to price in a more active Fed tightening cycle in response to upside inflation risks. After the stronger US inflation data, the Fed is expected to begin their tightening cycle as soon as this week. There are currently 22bps of hikes priced in for this week’s FOMC meeting compared to around 15bps a week ago. Over the same period the dollar index has strengthened by just 0.3% highlighting that the positive impact on the US dollar from the hawkish repricing of Fed rate hike expectations has been surprisingly limited so far.
Market expectations for a Fed hike this week were reinforced at the end of last week by the release of the US CPI report for August. The report revealed that core inflation picked up by 0.3%M/M in August which will add to concerns over the lack of disinflation progress towards their 2.0% target. Fed Chair Kevin Warsh indicated clearly in his Jackson Hole speech that they would need to tighten policy if they judged that underlying inflation was not continuing to slow back towards target with sufficient pace. Since the US-Iran conflict began in February, core inflation has increased by an annualized rate of 2.6% which compares to an annualized rate of 3.0% over the previous six-month period, and the annual rate of 2.8% in August. Kevin Warsh had already voiced concern over the lack of progress prior to upside surprise in August. As a result, the August report could be used as justification to begin tightening policy at this week’s meeting. The breakdown of the August CPI report revealed that core services were the main driver behind the pick-up in inflation contributing 0.29ppts while core goods added only 0.03ppts. The biggest contributor to core services inflation was the “wireless” category in telephone services which jumped by 5.5%M/M adding 0.1ppts to core inflation. It reflects recent price plan changes by AT&T and T mobile.
While it is not a done deal that the Fed will begin hiking rates this week, it would be big surprise for the Fed to leave rates on hold after recent communication. A decision to leave rates on hold would also threaten to undermine the Fed’s policy credibility amidst building concerns over upside inflation risks from rising energy prices. The price of Brent is currently trading at just over 50% higher than pre-conflict levels, and there is little optimism that energy supplies from the Middle East will normalize quickly. The announcement late on Friday from Saudi Arabia that it halted their East-West pipeline as precaution after attacks highlights that supplies could be disrupted further in the near-term. It is not yet clear how long the pipeline will remain closed. The East-West pipeline has proved to be a critical lifeline for Saudi Arabia’s oil exports. The 7 millon barrel/day conduit quickly reached full capacity earlier this year after the Strait of Hormuz effectively closed. If the Fed does not take action this week to address upside inflation risks, it could trigger a sharp sell-off for the US dollar and long-term US Treasuries by undermining confidence in their willingness to get on top of inflation. It could be one reason why US dollar gains have only been limited so far on the back of the hawkish repricing of Fed rate hike expectations. Market participants could be waiting for confirmation of policy action to open up further gains for the US dollar.
US dollar strength in the near-term could also be curtailed by the close proximity of the US mid-term elections. Even if the Fed begin to hike rates today, they maybe reluctant to deliver a back-to-back hike at the next meeting on 28th October which comes just before the mid-term elections on 3rd November. The next hike may then not be delivered until 9th December. Such a gradual pace of tightening may not be sufficient to trigger a much stronger US dollar heading into year end. At a time when other major central banks are planning to hike rates further as well. After last week’s policy meeting, we now expect the ECB (click here) to deliver two more hikes in response to higher energy prices taking their policy rate into mildly restrictive territory. It is helping to prevent yield spreads from moving more sharply in favour of a stronger dollar. However, over time a bigger energy price shock and higher US yields for longer should be supportive for a stronger US dollar especially if the recent resilience of global growth starts to fade. Please see our latest FX Weekly for more details (click here).
MUTED USD RESPONSE TO RECENT MOVE HIGHER IN US YIELDS
Source: MUFG Research, Macrobond, Bloomberg
KEY RELEASES AND EVENTS
Country | BST | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
EU | 10:15 | ECB's Schnabel Speaks | - | - | - | !! |
CA | 13:30 | CPI (YoY) | (Aug) | - | 3.0% | !!! |
EU | 16:15 | ECB President Lagarde Speaks | - | - | - | !! |
Source: Bloomberg & Investing.com