
All eyes on FOMC meeting as FX market remains in holding pattern
USD: Will Fed policy update support market expectations for extended hikes?
The major foreign exchange rates have remained in holding pattern ahead of tonight’s FOMC meeting. One of the main movers since the start of this week has been the yen which is giving back some of its strong gains from recent weeks resulting in USD/JPY rising back above the 155.00-level. The yen has been undermined since late last week by the hawkish repricing of rate hike expectations for other major central outside of Japan including the Fed and ECB. It is providing an offset to support for the yen from building expectations that the BoJ will speed up the pace of rate hikes this week. USD/JPY had previously dipped below support at the 155.00-level earlier this year in both January and February but the correction lower proved to be short-lived. Market participants are now waiting to see if today’s FOMC meeting will provide a catalyst for further US dollar strength. The US rate market has already moved along way to price in a more extended Fed rate hike cycle. There are currently around almost 100bps of Fed hikes priced in for the year ahead which would more than fully reverse last year’s rate cuts. The updated market pricing sets a higher bar for a hawkish policy surprise for the Fed to deliver a hawkish surprise at today’s FOMC meeting.
The Fed is now expected to begin hiking rates today after last week’s disappointing US inflation data showed a lack of progress for underlying inflation back towards the Fed’s target. Additionally, the Fed is under pressure to begin hiking rates today to back up their inflation fighting credibility under new Chair Kevin Warsh. If the Fed unexpectedly decided to leave rates on hold today it could trigger a sharp sell-off for the US dollar and weigh on the long-end of the US Treasury curve. For these reasons we expect the Fed to hike now, but the communication is unlikely to provide a clear signal over how much further tightening is likely to be needed. Market participants will focus on the Fed’s updated plot again for guidance even though Fed Chair Warsh places less importance on it and does not provide his own forecasts.
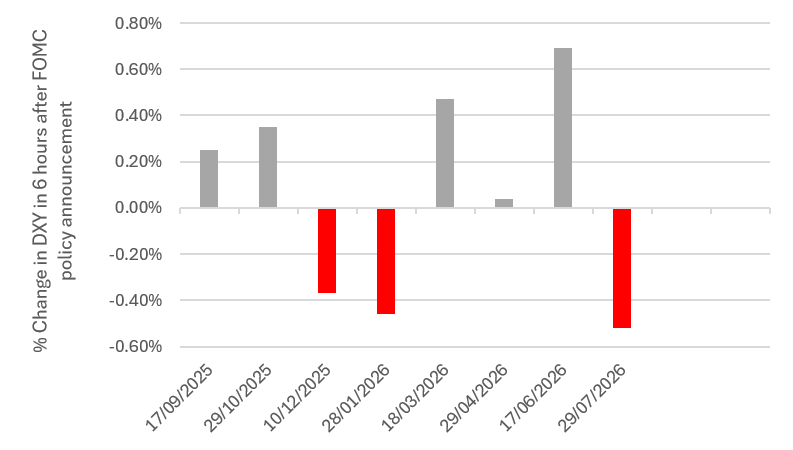
At the last projection meeting back in June, the median projection for the Fed funds rate at the end of this year was set at 3.8% before falling modestly to 3.6% in 2027 and 3.4% in 2028. It provided an indication that FOMC participants were leaning toward hiking rates at least once this year, but then expected to resume rate cuts from next year. Market participants will be watching to see if FOMC participants are now leaning toward delivering a second hike by the end of this year, and if they anticipate further hikes next year as well. For the US dollar to strengthen, the Fed’s policy update will have to reinforce market expectations for an extended rate hike cycle. The update communication from Fed Chair Warsh in the press conference could sound similar to his message at Jackson Hole that the Fed is prepared to act further if they are not confident that underlying inflation will back towards target at sufficient pace.
HAWKISH FED UPDATE IS REQUIRED TO SUPPORT USD
Source: MUFG Research, Macrobond, Bloomberg
GBP: UK CPI data overshadowed by recent energy price developments
The main economic data release this morning in Europe has been the latest UK CPI report for August. The report revealed that headline inflation picked up by 0.2ppt to 3.1% in August, while core and services inflation both remained stable at 2.6% and 3.4% respectively. The report provides reassurance that the pick-up in inflation has been mainly driven by higher energy prices so far with limited evidence so far of any broadening in price pressures. The positive contribution to headline inflation from fuels and lubricants for personal transport equipment has increased by around 0.7ppts since the US-Iran conflict began in February.
The lack of second round inflation effects so far and continued weakness in the UK labour market is helping to ease some of the building pressure on the BoE to tighten policy. It is why the BoE is still expected to leave rates on hold at tomorrow’s MPC meeting despite rising upside inflation risks from higher energy prices. However, we do expect MPC members to indicate that they are moving closer to voting for a hike at the following meeting in November. Headline inflation is on course to exceed 4.0% in the new year unless there’s a retracement in energy prices making it harder for the BoE to look through. Nevertheless, market expectations for more aggressive hike (>100bps) appear excessive and could put a dampener on the pound’s performance if those expectations are not met.
KEY RELEASES AND EVENTS
Country | BST | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
EU | 10:00 | Industrial Production (MoM) | (Jul) | -0.2% | 0.0% | !! |
US | 13:30 | Retail Sales (MoM) | (Aug) | 0.8% | -0.6% | !!! |
US | 19:00 | Fed Interest Rate Decision | - | 4.00% | 3.75% | !!! |
US | 19:30 | FOMC Press Conference | - | - | - | !!! |
Source: Bloomberg & Investing.com