
US dollar advance reflects more hawkish Warsh message
USD: Hawkish message signals more to come
The US dollar has held on to most of last night’s gains following the FOMC decision to hike the fed funds rate by 25bps and provide communications that certainly suggest the scope for further action ahead. The headline grabbing comment from Fed Chair Warsh that the hike had “removed a dose of accommodation” was the clearest signal that a certain level of accommodation still exists and therefore more action will be required. That was also underlined by the fact that the YoY core CPI rate only hits the 2% target in 2029. Warsh did play these forecasts down when asked about them in the press conference emphasising these were the product of all nineteen FOMC members – suggesting possibly that he would be willing to take more action and faster in order to bring inflation down more quickly.
In the same light, we possibly shouldn’t read too much into the median dot levels and those levels could and very likely will change as developments unfold moving forward. The 4.125% median dot for 2026 and 2027 points to another hike and then no cuts until 2028 when the median dot drops by just 25bps and then by another 25bps in 2029 to 3.625%. That’s a very cautious removal of the two hikes pencilled in for this year that certainly implies a faster reduction in core CPI will require more than just one additional hike. The long-run fed funds rate was tweaked higher by 12.5bps to 3.25% and the GDP and unemployment rate projections certainly painted a rosy picture of the outlook for the economy.
But while Warsh was hawkish and emphasised again his focus on achieving price stability, the bar was high going into the meeting for a large sell-off in rates and/or advance for the US dollar. Clearly UST bond yields had moved in advance of the decision with larger moves higher in yields on 10th September than the reaction yesterday. The OIS curve ahead of the meeting was priced for more than the two hikes signalled by the 2026 median dot and that should help contain the rates and FX reaction for now with the focus back on the data to determine whether those pushing for more than one further hike will start to have greater say. A lot still rests on energy prices over the short-term and the course of AI-related growth momentum over the medium term. For now, one further hike looks about right at this stage.
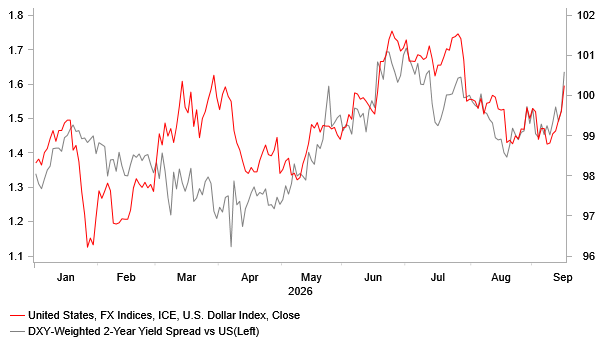
The US dollar gains ahead should also be curtailed by the fact that other central banks are set to turn more active in hiking rates as well. We have altered our view for the ECB (we now assume two further hikes to 3.00%) and the BoE (we have added two hikes to our core view) while the BoJ is set to speed up the pace of tightening (as we expected). Every G10 central bank, bar the SNB, is priced to hike by year-end. Front-end rate spreads (2-yr swap) do not point to further dollar buying from these levels, except for USD/JPY – see below.
SPREAD / FX MOVES CLOSELY ALIGNED SINCE MAY
Source: MUFG Research, Macrobond, Bloomberg
GBP: BoE in focus following FOMC meeting
Attention now will quickly shift to the BoE monetary policy announcement today at 12 noon (BST). We have written a preview (here) posing the very valid question – how long can the BoE hold out before hiking? We believe the BoE will hold out today but the key takeaways from today will point to the increased prospect of a rate hike in November. It is likely to prove increasingly difficult to ignore the developments in energy markets and in particular in natural gas prices with the front future price now up nearly 100% since the start of July. That will translate into a hefty OFGEM utility price cap increase in January that will see annual CPI hit over 4.0%. YoY CPI for August was confirmed at 3.1% yesterday which was above the 2.8% expected by the BoE.
We expect the BoE to hold today but we would also add that we hold that view with a little less conviction than implied by financial market pricing. Just 2bps of hikes are priced for today and when you consider the last meeting was a 6-3 vote and it would no surprise to see a 5-4 vote today, the market appears a little complacent to a surprise, pre-emptive hike.
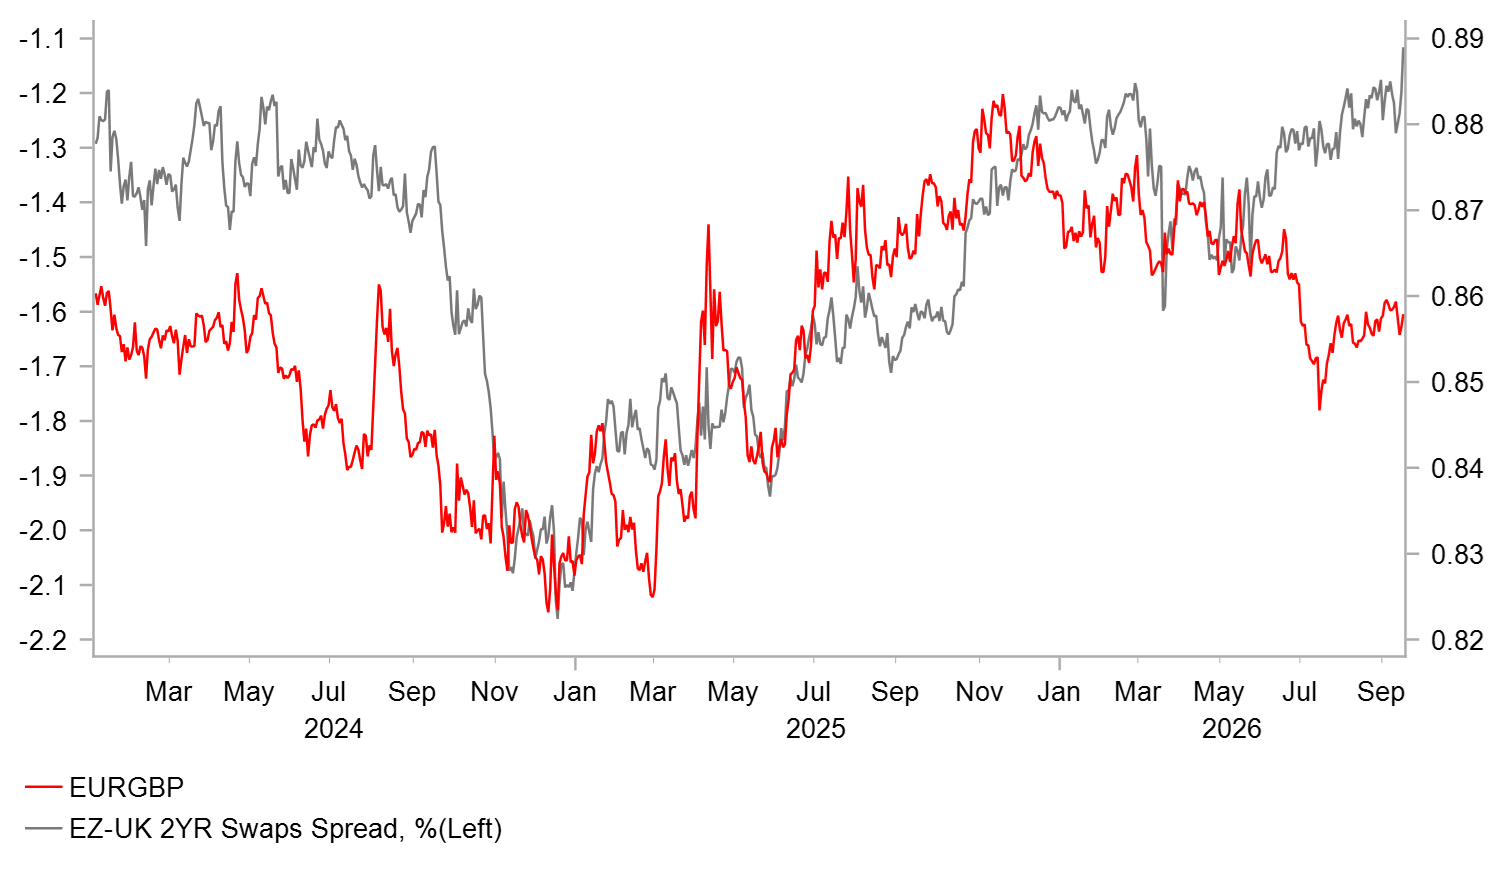
Since the latest lurch higher in global yields – from 9th Sept – the pound has been the best performing G10 currency after the US dollar. Longer-term yields continue to play a role in this resilience, but front-end spreads have been moving against the pound and Fed and ECB hiking could start to weigh on pound performance. Since the conflict began at the end of February, the pound is roughly unchanged versus the US dollar. A hawkish hold that tees up a November hike should put some modest upward pressure on front-end yields as back-to-back hikes get better priced (currently 39bps by Dec). That will help support the pound although we remain sceptical of upside scope of any notable magnitude ahead of the UK budget on 28th October.
EURGBP RISKS SKEWED TO THE UPSIDE
Source: MUFG Research, Macrobond, Bloomberg
JPY: BoJ to hike but beware of caution
Early tomorrow, ahead of the London open, the BoJ will announce its monetary policy decision with market pricing signalling a near 100% expectations of a 25bp rate hike to 1.25%. We certainly expect the general message from the communications to signal a clear plan to raise rates further which will go some way to endorsing the OIS rate curve priced for further hikes. It would also be consistent with the BoJ aligning itself to the coordinated efforts between Japan and the US to strengthen the yen.
That said, there is a notable risk that Governor Ueda’s comments could fall short of what markets are expecting given 90bps of hikes are priced over the next 12mths. Governor Ueda has history on being cautious when global uncertainties rise and with rising energy prices comes rising global yields and the risk of a global equity market downturn. He will certainly give little credence to the reports that the BoJ could need to consider a larger 50bp hike, which were triggered by a speech by uber-hawk Hajime Takata on 2nd September.
The 2-year US-JP swap spread is already signalling upside risks to USD/JPY based on co-movement over the last twelve months. It’s well known that in recent years that spread is not a particularly reliable indicator of FX moves but the co-movement is a lot more resilient since December last year – until the sharp drop in USD/JPY earlier this month. The US-JP 2-yr spread is 30bps higher so any disappointment in Ueda matching market pricing could see USD/JPY bounce more notably higher. That said, the retracement in USD/JPY today is notable and suggests from an FX perspective the expected faster pace of BoJ tightening is becoming a more important influence on FX direction.
KEY RELEASES AND EVENTS
Country | BST | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
EZ | 10:00 | CPI (MoM) | (Aug) | 2.9% | 0.2% | !! |
EZ | 10:00 | CPI (YoY) | (Aug) | 3.3% | 2.9% | !! |
EZ | 10:00 | Core CPI (MoM) | (Aug) | 0.2% | 0.0% | !!! |
EZ | 10:00 | Core CPI (YoY) | (Aug) | 2.4% | 2.5% | !!! |
EZ | 10:00 | HICP ex Energy and Food (MoM) | (Aug) | 0.2% | 0.0% | !! |
EZ | 10:00 | HICP ex Energy & Food (YoY) | (Aug) | 2.1% | 2.2% | !! |
EZ | 11:00 | ECB's Rehn speaks | !! | |||
UK | 12:00 | BoE Interest Rate Decision | (Sep) | 3.75% | 3.75% | !!!! |
UK | 12:00 | BoE MPC Meeting Minutes | - | - | - | !!!!! |
US | 13:30 | Philadelphia Fed Manufacturing Index | (Sep) | 31.3 | 47.4 | !! |
US | 13:30 | Initial Jobless Claims | - | 207K | 206K | !! |
US | 13:30 | Building Permits | (Aug) | 1.400M | 1.433M | !! |
US | 13:30 | Housing Starts | (Aug) | 1.320M | 1.239M | !! |
CA | 13:30 | RMPI (MoM) | (Aug) | 0.7% | -2.2% | !! |
CA | 13:30 | RMPI (YoY) | (Aug) | - | 18.1% | ! |
CA | 13:30 | IPPI (MoM) | (Aug) | 0.0% | 0.6% | ! |
CA | 13:30 | IPPI (YoY) | (Aug) | - | 12.4% | ! |
US | 15:00 | Pending Home Sales (MoM) | (Aug) | 2.0% | -2.3% | !! |
Source: Bloomberg & Investing.com