
AI sentiment stays fragile and the dollar remains stronger
USD: Williams dismisses bigger move but rates remain elevated
The US dollar hit a new intra-day high yesterday as market participants continue to position for a series of Fed rate hikes – this despite the large drop in crude oil prices and some diminished enthusiasm for all things AI-related. Strong results from Nvidia after the close yesterday – Nvidia posted revenues of USD 115.8bn in Q3, up 20% from the previous quarter and 103% from a year earlier has had limited broader impact. The projections for next fiscal year were also raised from 70% growth to 75% growth off a higher base. Nvidia shares advanced in after-hours trading but the follow through to Asian trading has not been sustained with the performance generally mixed. The Kospi is higher, the Taiwan TAIEX is marginally higher while the Topix is down. The Nvidia results are good news but amongst a lot of negatives that will likely keep enthusiasm for AI curtailed.
One of the negatives is of course the level of yields that is creating a bigger burden on valuations and funding and hence increasing risk aversion. The minutes of the FOMC meeting in October will be released this evening and will likely reflect the growing consensus amongst FOMC members that there is more work to do, signalling further rate hikes in Q1 next year. New York Fed President Williams has again tried to bring some balance to the debate on how much tightening is needed arguing yesterday that he didn’t “think the situation calls for dramatic action” and that while he is seeing the drivers of inflation, he is not seeing that inflation broadening out. That puts him firmly in the camp of a 25bp rate hike on 9th December, and in our view the position the majority of the FOMC will likely sit at that meeting. Much of the pricing of a risk of a 50bp hike has been removed from the market and now only a very strong NFP report and rebound in energy prices will bring that prospect back into play. That suggests to us that there is not a lot more that the US dollar can get from rate hike pricing. The market is now priced for three further rate hikes that would take the fed funds rate to 4.50% - 4.75%, a level we still view as excessive and unlikely.
But we understand the pricing at this juncture and acknowledge a re-escalation of the conflict in the Middle East could be a spark for a renewed jump in crude oil prices that would only serve to reinforce the argument for further hikes. There are reports of Iran targeting US forces in Kuwait with drones today while Al Jazeera has revealed US reports of nearly daily unreported attacks between the US and Iran over the last two months with the US now deploying three US aircraft carriers to the region. This doesn’t look like de-escalation in response to the midterm election losses for the Republicans.
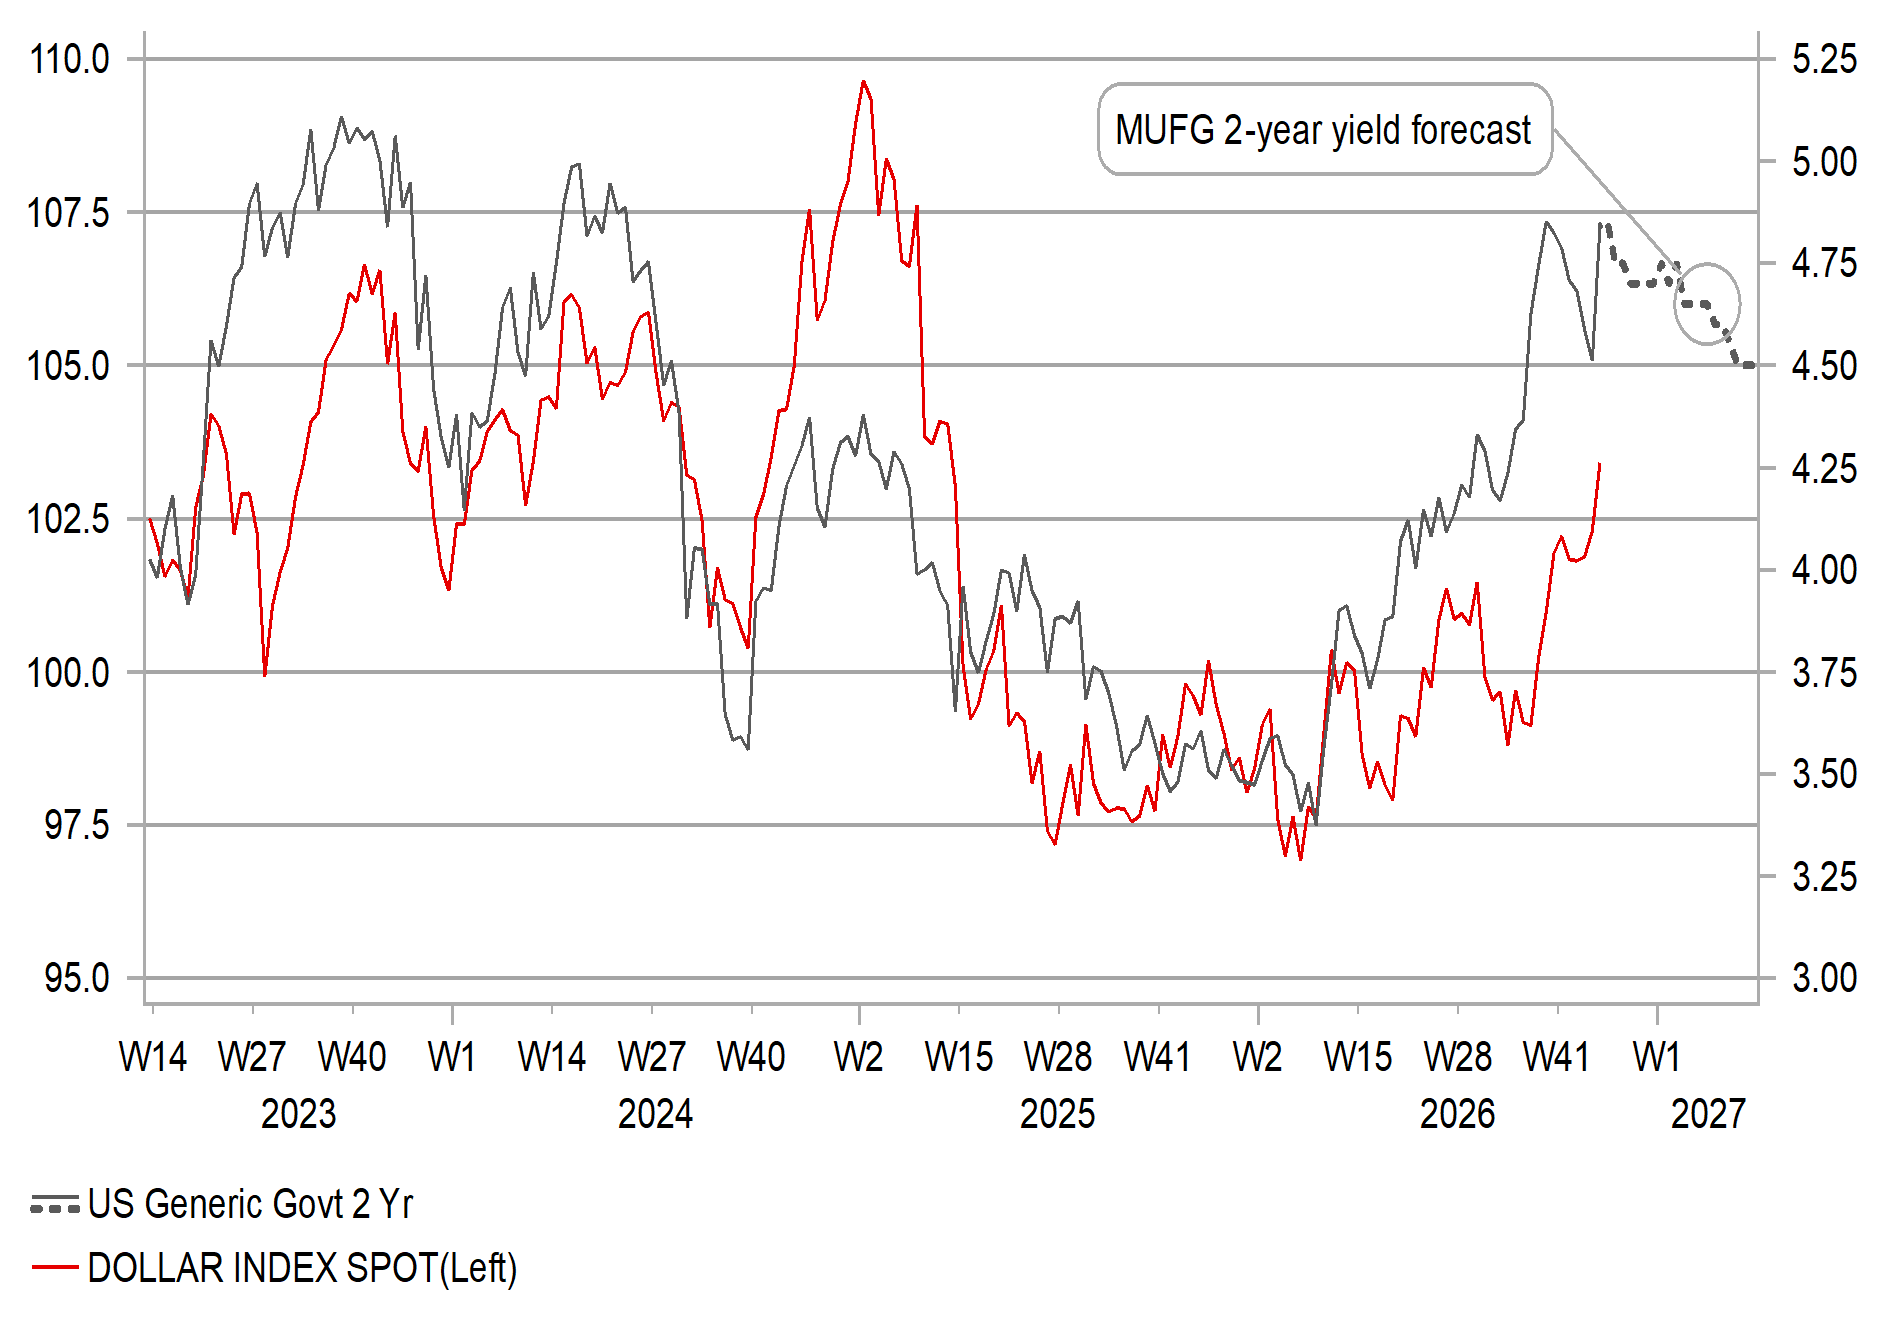
We have stated before that the US yield move higher could result in DXY hitting levels that would coincide with EUR/USD falling to around the 1.0800-level. That’s certainly plausible if crude oil prices rebound sharply on a more dramatic re-escalation of the conflict. But we would still argue that a large portion of the rates move is now done with three further rate hikes priced that should help curtail the extent of further dollar strength.
DXY HAS SCOPE TO ADVANCE FURTHER
Source: MUFG Research, Macrobond, Bloomberg
GBP: CPI jumps as expected driven by specific factors
The pound is broadly stable with the inflation data coming in as expected with energy and tobacco playing a role, as expected. The OFGEM price cap increase of 4% in October and a rise in heating oil were evident in the utilities price increase while petrol and diesel prices increase showed up in the transportation sector. Transport, Alcohol & Tobacco and Recreation and Culture were the top three categories lifting inflation in October. There was a lift to tobacco prices (+5.2% MoM) with higher duties on vapes and tobacco kicking in. The bigger lift to CPI lies ahead with the OFGEM price cap increase in January likely to be more substantial at 25%-27%. A jump in the annual headline rate to around the 4.5% level is feasible in January/February and has been flagged by the BoE. In its projections in November, the BoE projected headline CPI at 4.4% in Q1 2027 and rising further to 4.9% in Q2, dropping only marginally to 4.8% in Q3. The 2.0% target rate is achieved by Q3 2028. Of course, these projections were based on market rates that are very different today following the sharp decline in crude oil prices this month ahead of and after the midterm elections in the US. If these current energy prices remain lower, then the BoE’s projections will likely be too high with a peak likely coming in Jan-Feb rather than in Q2. We certainly suspect the current market pricing of around 90bps of monetary tightening by September next year will prove excessive.
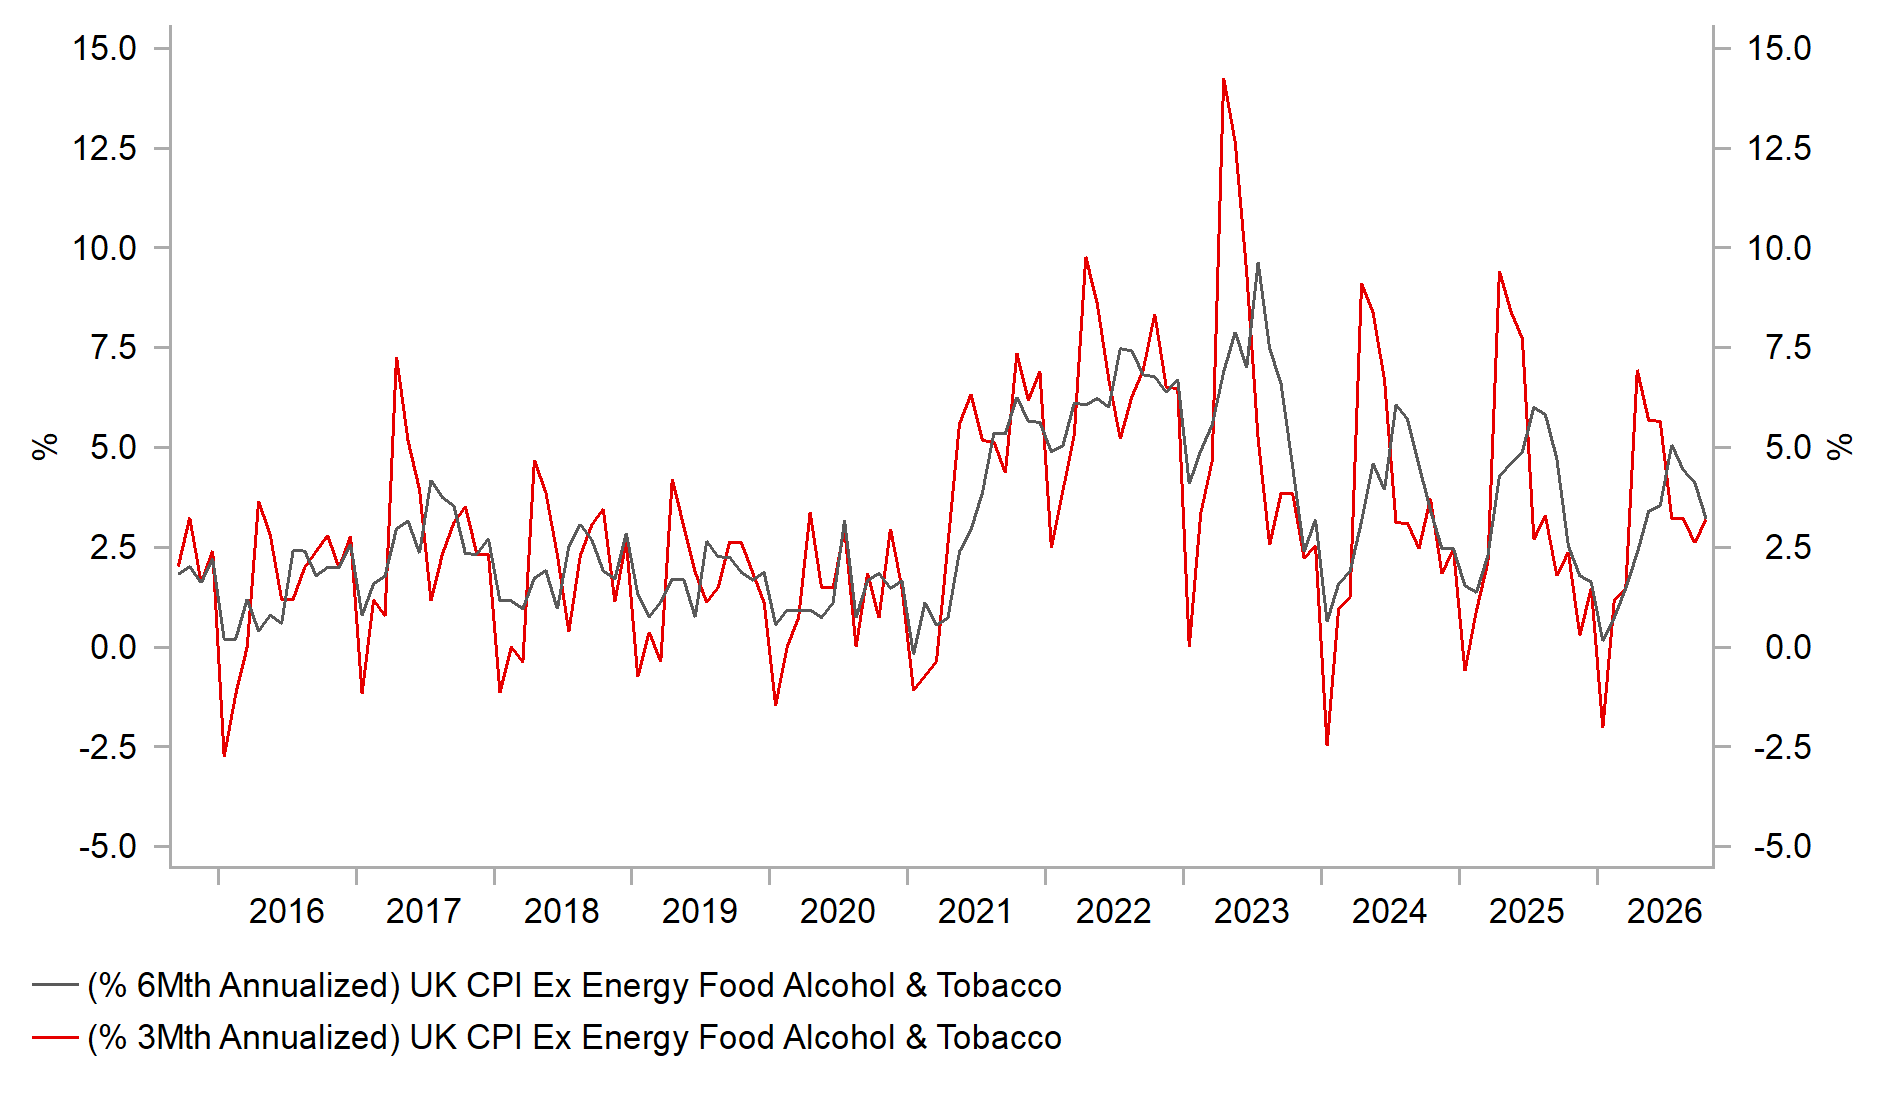
Today’s data is somewhat reassuring in indicating limited risks of further pass-through to underlying inflation with the core annual CPI rate remaining unchanged at 2.8% and services inflation remaining at 3.7% 0.1ppt lower than expected. The labour market continues to show mixed signs, but weaker, more benign wage growth was evident in the labour market data yesterday that will help reassure the BoE that the risks of a broadening of inflation remains contained.
The pound continues to perform well and on a month-to-date basis, is the fourth best performing G10 currency after the dollar, yen and euro. Since the tech correction began (peak was 6th Oct) the pound is the second-best performing currency behind only the dollar. Stronger economic growth, helped in part by AI and signs of stronger productivity growth continue to provide support. Contained inflationary pressures that allows the BoE to hike only modestly could help provide further support for growth. Today’s inflation data should help.
UK CORE CPI 3MTH & 6MTH ANNUALISED RATES ABOVE TARGET BUT CONTAINED
Source: Bloomberg, Macrobond, MUFG Research
KEY RELEASES AND EVENTS
Country | GMT | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
UK | 09:30 | House Price Index YoY | (Sep) | 0.9% | ! | |
EC | 10:00 | CPI YoY | (Oct F) | 4.00% | 4.00% | !! |
EC | 10:00 | CPI MoM | (Oct F) | 0.40% | 0.40% | !! |
EC | 10:00 | CPI Core YoY | (Oct F) | 2.50% | 2.50% | !! |
US | 13:30 | Housing Starts | (Oct) | 1250k | 1221k | !! |
US | 13:30 | Housing Starts MoM | (Oct) | 2.40% | -5.20% | !! |
US | 13:30 | Building Permits | (Oct P) | 1375k | 1398k | !! |
EC | 14:25 | ECB President Lagarde speaks |
|
|
| !!!! |
UK | 15:00 | BoE Governor Bailey speaks |
|
|
| !!!! |
US | 15:00 | Pending Home Sales MoM | (Oct) | -1.7% | -0.7% | ! |
US | 15:00 | Pending Home Sales YoY | (Oct) | -13.7% | -12.6% | ! |
US | 17:15 | Fed’s Daly speaks | - |
|
| !!! |
CA | 18:30 | BoC Deputy Governor Gravelle speaks | - |
|
| !! |
US | 10:00 | FOMC Minutes released | - |
|
| !!!! |
Source: Bloomberg & Investing.com