
Commodity currencies continue to underperform
AUD: Weak Australian labour market data reinforces bearish trend
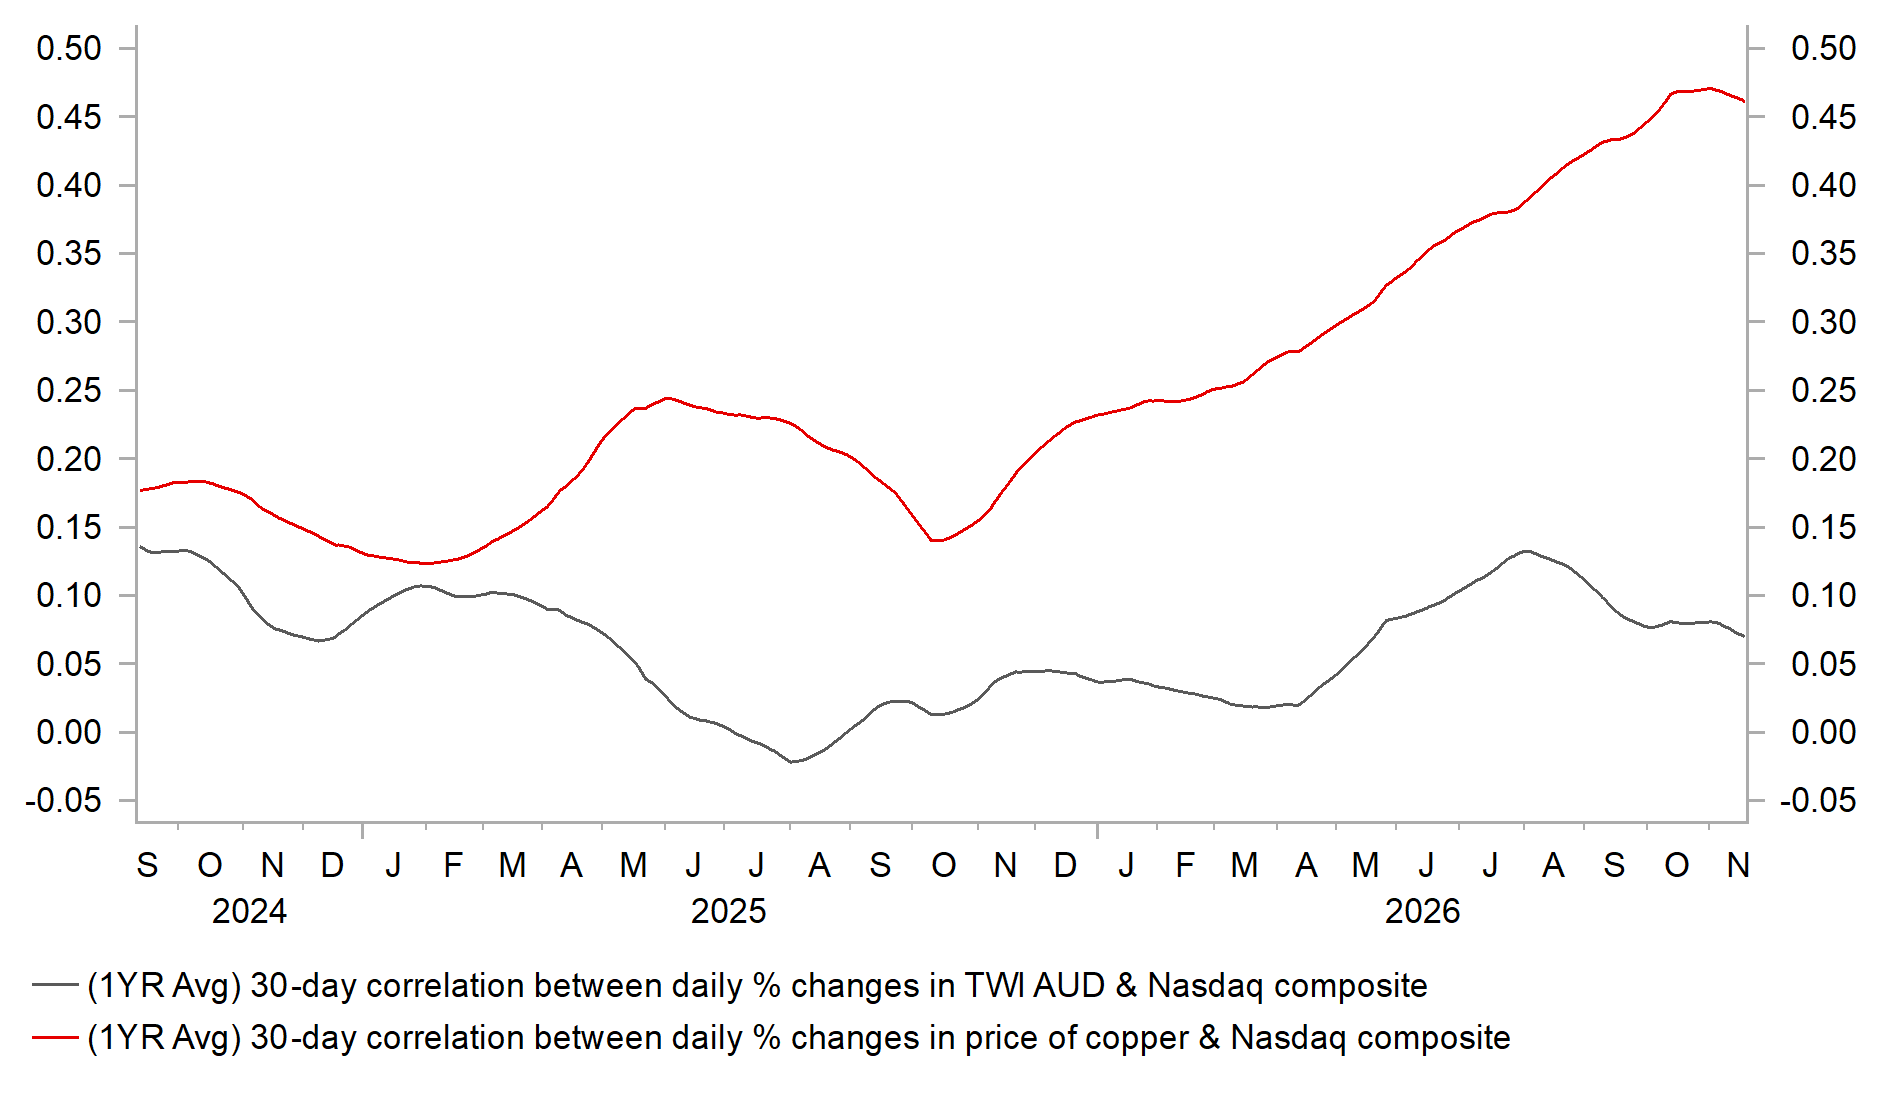
The Australian dollar has continued to underperform overnight giving back all of its year-to-date gains against the US dollar. The pair hit a low overnight at 0.6662 which is close to the closing price at the end of last year at 0.6673. The Australian dollar has weakened sharply over the last couple of months after hitting a high of 0.7238 on 9th September. The Australian dollar has clearly underperformed over this period when it has been the worst performing G10 currency falling by just over 7% against the US dollar. The Australian dollar has been undermined by a perfect storm of bearish developments in the autumn including a sharp correction lower for commodity prices, a loss of investor confidence in the AI-related investments and building confidence amongst market participants that the RBA’s tightening cycle has come to end while G10 central remain on course to raise rates further helping to narrow yield differential with Australia. These negative drivers were again in force over the last 24 hours reinforcing weakness in the Australia dollar. The price of copper fell sharply by around-5.5% hitting its lowest level since April. It has become more tightly correlated to US tech stocks this year suggesting that recent sell-off could also reflect the loss of investor confidence in AI-related investments. The price action could also be sending a warning signal to investors over the potential for a slowdown in global growth ahead after global growth has proven more resilient than expected this year. Bloomberg’s commodity price index has closed below its 200-day moving average in recent weeks for the first time since the summer of last year sending a similar bearish signal. It is unsurprising that commodity-related currencies such as the Australian dollar are underperforming in the current environment.
With commodity prices rolling over it should help to ease pressure on central banks to tighten policy in response to the energy price shock. The RBA has led the way in the current tightening cycle by hiking rates five time for a total of 125bps that has lifted their key policy rate to 4.85%. The policy rate is now at the highest level since the Global Financial Crisis. The lagged impact of monetary tightening on Australian economy is now becoming evident which is reinforcing market expectations that now further tightening is required. The RBA may even have to reverse course and cut rates next year if the economy slows more than expected. The Australian rate market has moved to fully price in a rate cut later next year, and around 16bps of cuts by the middle of next year. Those expectations were encouraged by the release of the much weaker than expected Australian labour market report released overnight. The report revealed that the Australin economy unexpectedly lost -43.5k jobs in October following job losses of -36.4k in September. Weakness in recent months has been driven by part-time job losses. There has been a clear slowdown in employment growth this year which has averaged around 7k/month compared to around 13k/month in 2025. At the same time, the unemployment rate has been trending higher since July jumping by a further 0.2ppts in October up to 4.9%. It compares to the RBA’s forecast for Q4 of 4.7%. Loosening labour market conditions argue against further rate hikes and may require rate cuts next year if the weakening trend continues. The latest developments support our short AUD/JPY trade recommendation (click here).
AUD & COPPER CORRELATIONS WITH US TECH STOCKS
Source: MUFG Research, Macrobond, Bloomberg
USD: FOMC minutes & Fed rhetoric keep alive expectations for faster hikes
The sharp hawkish repricing of Fed rate hike expectations is contributing the weakness sin commodity prices and related currencies. The 2-year US TIPS real yield has risen sharply by around 80bps from the middle of September when Blooberg’s commodity price index topped out. The yield is currently at around 2.67% and is moving back closer to the highs recorded in 2023 and 2024 at around 3.24% and 2.74% respectively. Fed officials have adopted a more hawkish tone recently talking up the need for faster rate hikes even as market-based measures of inflation expectations have been falling alongside lower energy prices. It raises the question of whether the Fed could be making a policy mistake by speeding up the pace of rate hikes just as commodity prices are rolling over.
The release overnight of the minutes from the last FOMC meeting in late October revealed that nearly all participants agreed that they would likely have to raise interest rates in the “months ahead”. However, only a couple of participants noted that hiking by more than 25bps in December might be warranted if the inflation data were unfavourable. We now know that Governor Waller was likely one of those participants considering a larger hike next month. He appeared to moderate that call yesterday by saying he would only back a 50bp hike if the Fed does not signal a January hike alongside raising rates next month. The case for larger hike appears to lack broad-based support within the FOMC. New York Fed Chair Williams pushed back against the need for larger hike yesterday saying that “I don’t think the situation calls for dramatic action”. Still there is currently a high risk of back-to-back hikes in December and January, and possibly even March which is encouraging a stronger US dollar.
KEY RELEASES AND EVENTS
Country | GMT | Indicator/Event | Period | Forecast | Previous | Mkt Moving |
EU | 09:00 | Current Account | (Sep) | 16.6B | 8.7B | !! |
EU | 10:00 | Construction Output (MoM) | (Sep) | 1.85% | !! | |
GB | 12:15 | BoE MPC Member Dhingra Speaks | - | !! | ||
US | 13:30 | Philadelphia Fed Manufacturing Index | (Nov) | 20.6 | 20.9 | !! |
US | 13:30 | Initial Jobless Claims | - | 198K | 200K | !! |
EU | 13:30 | ECB President Lagarde Speaks | - | !! | ||
US | 14:25 | Fed Governor Jefferson Speaks | - | !! | ||
US | 15:00 | US Leading Index (MoM) | (Oct) | 0.0% | 0.0% | !! |
US | 17:30 | Fed Goolsbee Speaks | - | !! |
Source: Bloomberg & Investing.com