
USD remains softer as rate hike expectations build outside of US
USD: US housing market and rate hike expectations outside of US in focus
The major FX rates have remained relatively stable overnight with the US dollar continuing to trade at modestly weaker levels. The US dollar was undermined in party yesterday by the release of evidence showing the negative impact of higher rates on the US housing market. The releases of the latest US housing starts and pending home sales reports for September both came in much weaker than expected declining by -5.2%M/M and -7.3%M/M respectively. It was new record low for pending home sales since the series began back in 2001.The NAR chief economist stated that “market conditions weakened in September due to fast-rising mortgage rates”, although he held out some hope that “buyers and sellers may simply be holding back until mortgage rates move favourably”. The negative impact on US dollar from housing market weakness should remain muted though given it is not a major policy focus for the Fed who setting policy to bring inflation back towards their goal in a more timely manner. We still expect the Fed to hike rates one more time this year in December and can’t completely rule out the probability of another back-to-back hike this month after the stronger US inflation data for September. Recently the US rate market has been scaling back Fed rate hike expectations for this month and there is currently only around 4bps of hikes priced in after Fed officials including Chair Kevin Warsh refrained from signalling that they are in a rush to raise rates further after tightening policy for the first time last month. The scaling back of October Fed rate hike expectations has helped to dampen the US dollar’s upward momentum in the near-term although further hikes remain likely.
At the same time, rate hike expectations have been increasing for other G10 central banks including the BoC, BoE and RBA. The Australian rate market has moved overnight to price in a higher probability of another RBA rate hike before the end of this year after hawkish comments from RBA Deputy Governor Andrew Hausner who stated that the inflation outlook looks “materially worse” than forecast by the RBA back in August. He added that “we’re seeing higher AI prices, tech prices feeding through into CPI…and we’re having a boom in data centre construction here in Australia as well, so that’s upside too, and then on domestic capacity pressure”. It comes on top of higher energy prices with the price of oil currently trading about a third higher than the RBA has assumed back in August. He displayed concern that “inflation has been high for a very long time now, and we are beginning to see some signs that people in the community are not sure if we’re going to bring inflation back to target, or certainly not for an extended period”. The hawkish comments have encouraged market participants to price in closer to a 50:50 probability of another RBA hike next month. Higher yields in Australia have encouraged a stronger Australin dollar this year although it’s has underperformed recently alongside the wobble for AI-related trades.
We continue to expect the BoE to begin their hiking cycle in November after recent stronger economic data for both activity and employment alongside comments from BoE officials including Governor Bailey. The release of the latest UK CPI report this morning should seal the deal for a hike next month. The report revealed that headline inflation jumped to 3.5% in September up from 3.1% in August. We expect inflation to pick up further rising above 4.0% next year once the energy price cap is reset higher again. The breakdown of the report also revealed that core inflation and services inflation both picked up to 2.8%and 3.7% respectively in September. The latest developments remain favourable for the pound to strengthen further in the near-term.
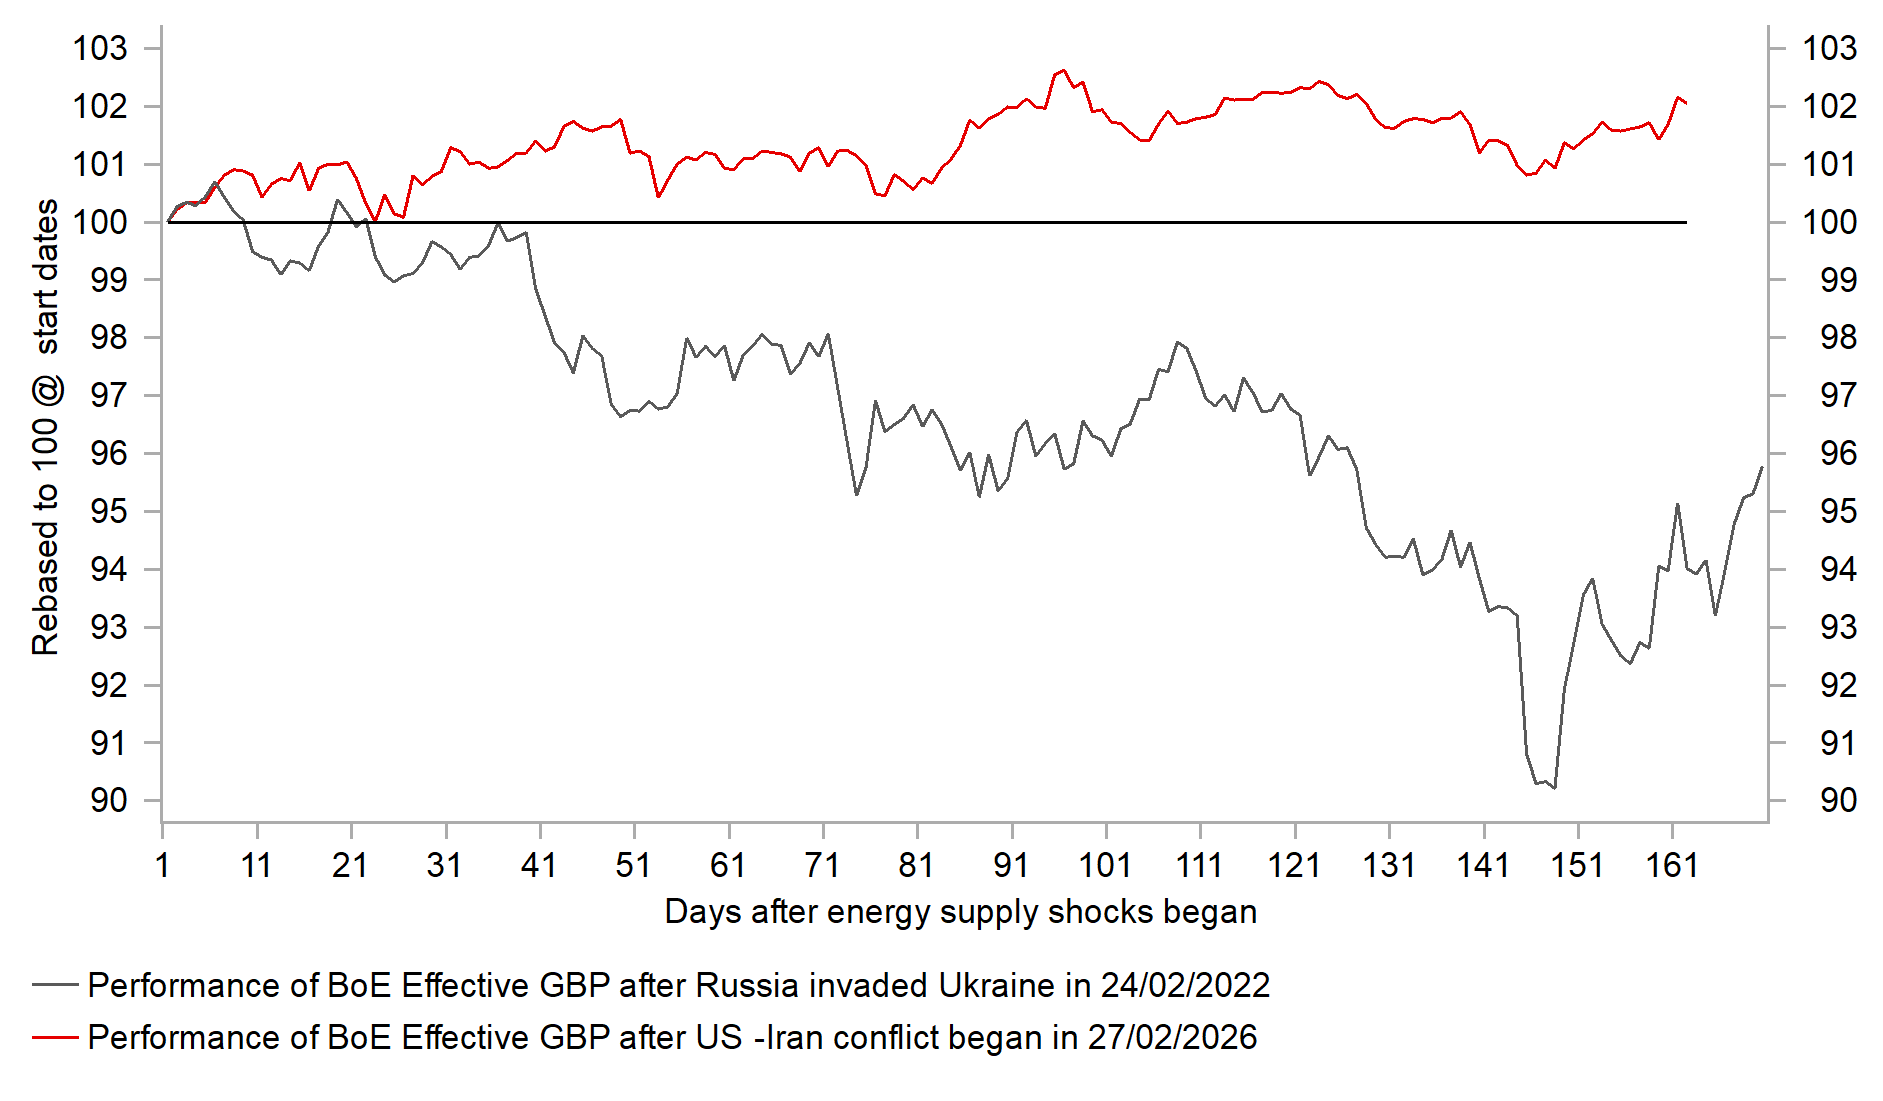
GBP CONTINUES TO PROVE RESILIENT DURING ENERGY SHOCK
Source: MUFG Research, Macrobond, Bloomberg
JPY: Higher rates helping to offset impact from negative terms of trade shock
The yen has continued to trade in narrow range against the US dollar at just above the 158.00-level. For most of this month the pair has traded within a 2 big figure range between 157.00 and 159.00. The heightened risk of further intervention to support the yen is helping to prevent USD/JPY from moving higher in the near-term alongside the recent correction lower for the US dollar more broadly. As a result, USD/JPY volatility levels have fallen back towards year-to-date lows that were in place prior to joint intervention in late July.
The main developments overnight in Japan were comments from BoJ Deputy Governor Ryozo Himino who told Kyodo news that underlying inflation is very close to their 2.0% target and is expected to be consistent with their goal going forward. He added that delays in policy adjustment could hurt the economy. There was no clear signal that the BoJ is considering raising rates again as soon as this month which is consistent with our view that the next hike will be delivered in December. A view that is already well priced into the Japanese rate market. Bloomberg reported evidence yesterday that rising yields in Japan are helping to attract more domestic demand for government bonds. The report (click here) highlighted that Japanese investor net purchases of domestic government bonds totalled JPY18.8trillion in the six months to September which was the highest since 2009 for the first half of the fiscal year. An encouraging development for the JGB market which could also help to ease JPY selling pressure if stronger domestic is sustained going forward.
At the same time, it was revealed overnight that Japan recorded a bigger than expected trade deficit in September totalling GBP536.6billion. The value of crude oil imports jumped by 51.1% driven by higher prices while volumes increased by 3.3%. The wider trade deficit for Japan due to the negative terms of trade shock from higher energy prices remains a headwind for yen performance.
KEY RELEASES AND EVENTS
Country | BST | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
GB | 14:00 | BoE Gov Bailey Speaks | - | - | - | !!! |
EU | 17:00 | ECB President Lagarde Speaks | - | - | - | !! |
NZ | 22:45 | CPI (YoY) | (Q3) | - | 4.1% | !! |
Source: Bloomberg & Investing.com