
Decline in crude oil fails to weaken the US dollar
USD: Optimism builds as crude oil price declines
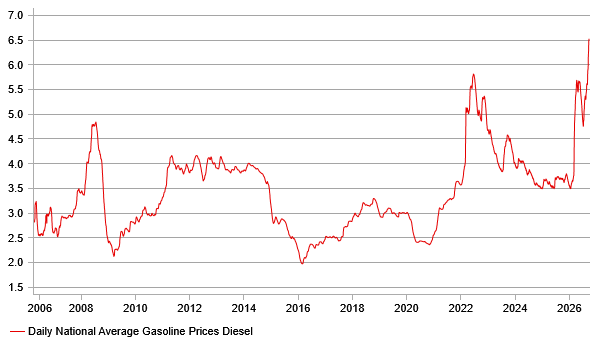
The US dollar has strengthened modestly further today with the focus back on the Middle East following the United Nations General Assembly where US officials met with Iranian officials to discuss a potential deal to halt the conflict. Optimism had been low for any progress after President Trump’s speech but the meeting later in the day was described as “very good”. Indirect negotiations took place for three hours and were described as “very productive”. The timing for another push by the US to strike a deal makes sense given the approaching mid-term elections and the continued rise in energy prices. Retail gasoline prices in the US are up 10% so far in September and are approaching the highs set in May. The price of a gallon of diesel has surged 15% in September and has broken above the 2022 highs to set a new record in the data series going back to 2005. The news of successful talks comes after reports yesterday that Iran was willing to reopen the Strait of Hormuz in the coming days if certain conditions were agreed.
The reaction in energy markets was clear with Brent crude oil down around 4% from intra-day high yesterday. Brent crude oil is down today for the sixth consecutive day, which, if maintained, would be the longest period of decline in crude oil since August 2025.
As of yet that scale of move is not translating to broader moves in FX and rates. US yields remain elevated and yesterday hit an intra-day high of 4.79%, the highest level since July 2024 with inflation risks still elevated given the high retail price. There is likely also an understandable level of scepticism that this time will be any different to previous moments when a deal was reportedly close. But the continued rise of gasoline and diesel could well see this time proving more productive. Prediction markets in recent days have seen a notable shift toward the Democrats winning both the House and the Senate in November. The House was always likely to turn blue but recent days has seen a shift in the Senate as well. The ‘Race to the WH’ polling company now estimates the Democrats have a 70% chance of winning the Senate, winning 52.4 seats to the Republicans’ 47.6. Pressure will continue to build on President Trump with his popularity at record lows.
For now FX and rates markets are being influenced by the communications from Fed officials. Fed Presidents Goolsbee and Musalem (both non-voters but Goolsbee will vote in 2027) were hawkish this week signalling support for further tightening. Richmond Fed President Barkin spoke yesterday and argued that it will take time to bring inflation back to target and that there was a risk of current elevated inflation impacting inflation expectations. He seems in the camp of being supportive of further action. Momentum remains with the US dollar even with crude oil declining and that’s unlikely to change over the very short-term.
US RETAIL DIESEL PRICE SURGES TO NEW RECORD HIGH
Source: MUFG Research, Macrobond, Bloomberg
EUR: Downside risks building
We mentioned in the FX Weekly last Friday that the near-term risks for EUR/USD were certainly skewed to the downside (here). The German election result over the weekend, which confirmed another solid win for AfD has certainly helped to reinforce those risks although the result itself wasn’t a huge surprise. We also cited terms of trade risks and French political risks and yesterday the OAT/Bund spread re-widened back close to the closing high last week while energy prices remained elevated. In addition the risk of a US rates overshoot is high and yesterday we saw the 2-year UST bond yield hit a new intra-day high following numerous hawkish comments from Fed officials – see above.
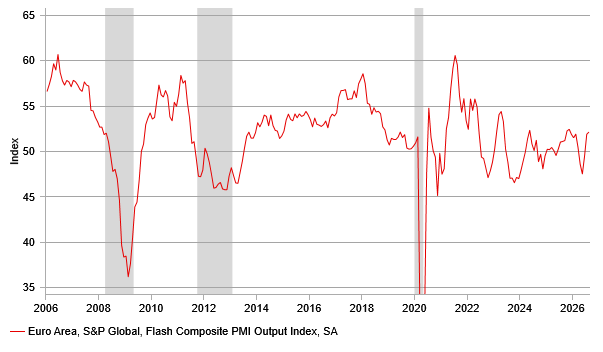
Technically, the backdrop for EUR/USD also does not look good. The trendline support from the intra-day low in February 2025 (when Trump first started to announce his tariff policies) and the intra-day low on 28th July has been under threat in recent trading days but yesterday broke more substantially below that trendline and signals an extension of the move lower over the coming days. EUR/USD 25d risk-reversals all dropped sharply yesterday indicating a shift in sentiment as EUR/USD breaks key levels. While the move is still more of a US dollar story, the macro backdrop in the euro-zone could start to weaken if the negative energy terms of trade shock starts to undermine business confidence. In that context the advance PMIs today from Europe will provide some key information on whether the latest leg higher in energy prices is having an impact.
There was at least good news from Germany with confirmation of backing for Chancellor Merz from other party members in a meeting of the party’s parliamentary caucus. Parliamentary leaders stated that Chancellor Merz will have their support for backing the passing of the planned reform agenda. That’s unlikely to provide a boost for support and the AfD risk will not go away. But the so-called ‘firewall’ to block the AfD from power is holding for now. That’s unlikely to hold indefinitely given the scale of victory in state elections that is reflective of growing electoral support. So the EUR/USD move for now looks more technically driven and USD-led but there are other specific risks to Europe that could reinforce the move, especially if today’s advance PMIs disappoint.
SURPRISE RESILIENCE IN EURO-ZONE PMI – WILL THAT CONTINUE IN SEPT?
Source: MUFG Research, Macrobond, Bloomberg
KEY RELEASES AND EVENTS
Country | BST | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
FR | 08:15 | French Manufacturing PMI | (Sep) | 50.9 | 51.1 | !!! |
FR | 08:15 | French Services PMI | (Sep) | 48.3 | 48.0 | !!! |
DE | 08:30 | German Manufacturing PMI | (Sep) | 54.1 | 54.3 | !!! |
DE | 08:30 | German Services PMI | (Sep) | 49.9 | 49.7 | !!! |
EZ | 09:00 | Services PMI | (Sep) | 51.4 | 51.6 | !!! |
EZ | 09:00 | Manufacturing PMI | (Sep) | 52.6 | 52.7 | !!! |
EZ | 09:00 | S&P Global Composite PMI | (Sep) | 51.7 | 52.0 | !!! |
UK | 09:30 | Services PMI | (Sep) | 52.0 | 52.5 | !!! |
UK | 09:30 | Manufacturing PMI | (Sep) | 51.5 | 51.7 | !!! |
UK | 09:30 | Composite PMI | (Sep) | 52.0 | 52.5 | !!! |
US | 14:45 | Manufacturing PMI | (Sep) | 53.6 | 53.9 | !!! |
US | 14:45 | Services PMI | (Sep) | 55.8 | 56.5 | !!! |
EZ | 17:30 | ECB's Lane Speaks | - | - | - | !! |
Source: Bloomberg & Investing.com