
USD’s upward momentum dampened by Fed rhetoric
USD: NY Fed President Williams pushes back against an October rate hike
The US dollar has continued to strengthen this week resulting in the dollar index hitting a high yesterday of 101.61, and moving closer to the year-to-date high from June at 101.80. However, the US dollar’s upward momentum has since been dampened by comments from New York Fed President Williams who pushed back strongly against building market expectations for the Fed to hike rates again as soon as next month just before the US mid-term elections. He stated clearly that “with the policy action we took at our September meeting, there is no need for urgency, and we have time to gather more information”. He believes that “if the economy evolves in a manner broadly consistent with my forecast, one further upward adjustment of the federal funds target range may be appropriate late this year to support a timelier return of inflation to target”. In response the US rate market has pared back expectations for an October rate hike. There are currently around 12bps of hikes priced in compared to around 18bps prior to the comments from New York Fed President Williams. It still leaves room for US yields to correct lower in the near-term if the Fed leaves rates on hold in October. At the same time, he also displayed more confidence in the US economy which is proving more resilient than expected. He now expected “somewhat larger and long-lasting effects from energy prices”, while adding that “the inflationary impact of the AI-related demand shock is increasingly salient”. He sees inflation of 3.5% this year and does not expect it to fall back to the Fed’s goal until 2028. The comments will keep alive market expectations for at least more rate hikes in the current tightening cycle, although we still believe that market pricing for almost four more hikes in the year ahead is excessive.
New York Fed President Williams has not been the only central banker to attempt to dampen rate hike speculation this week. Earlier this week President Lagarde pushed back against expectations for the ECB to deliver another back-to-back hike next month. She highlighted that “while growth has been resilient, since our last meeting long-term interest rates have risen notably, which will slow growth and reduce pass-through by more than projected in our September exercise”. Furthermore, with second-round effects so far absent, it means that the ECB should continue to adopt a “measured response as appropriate to keep inflation in check”. She indicated that “interest rates do not move in lockstep with energy prices”. The comments have dampened expectations for another ECB hike as soon as next month. There are currently around 7bps of hikes priced in for October compared to 10bps at the end of last week. Inflation in the euro-zone would need to surprise meaningfully to the upside in September to refuel October rate hike speculation. Headline inflation picked up more than expected yesterday in Spain hitting 4.9% highlighting that an October hike can’t yet be completely ruled out. The paring back of ECB rate hike expectations has contributed to euro weakness this week.
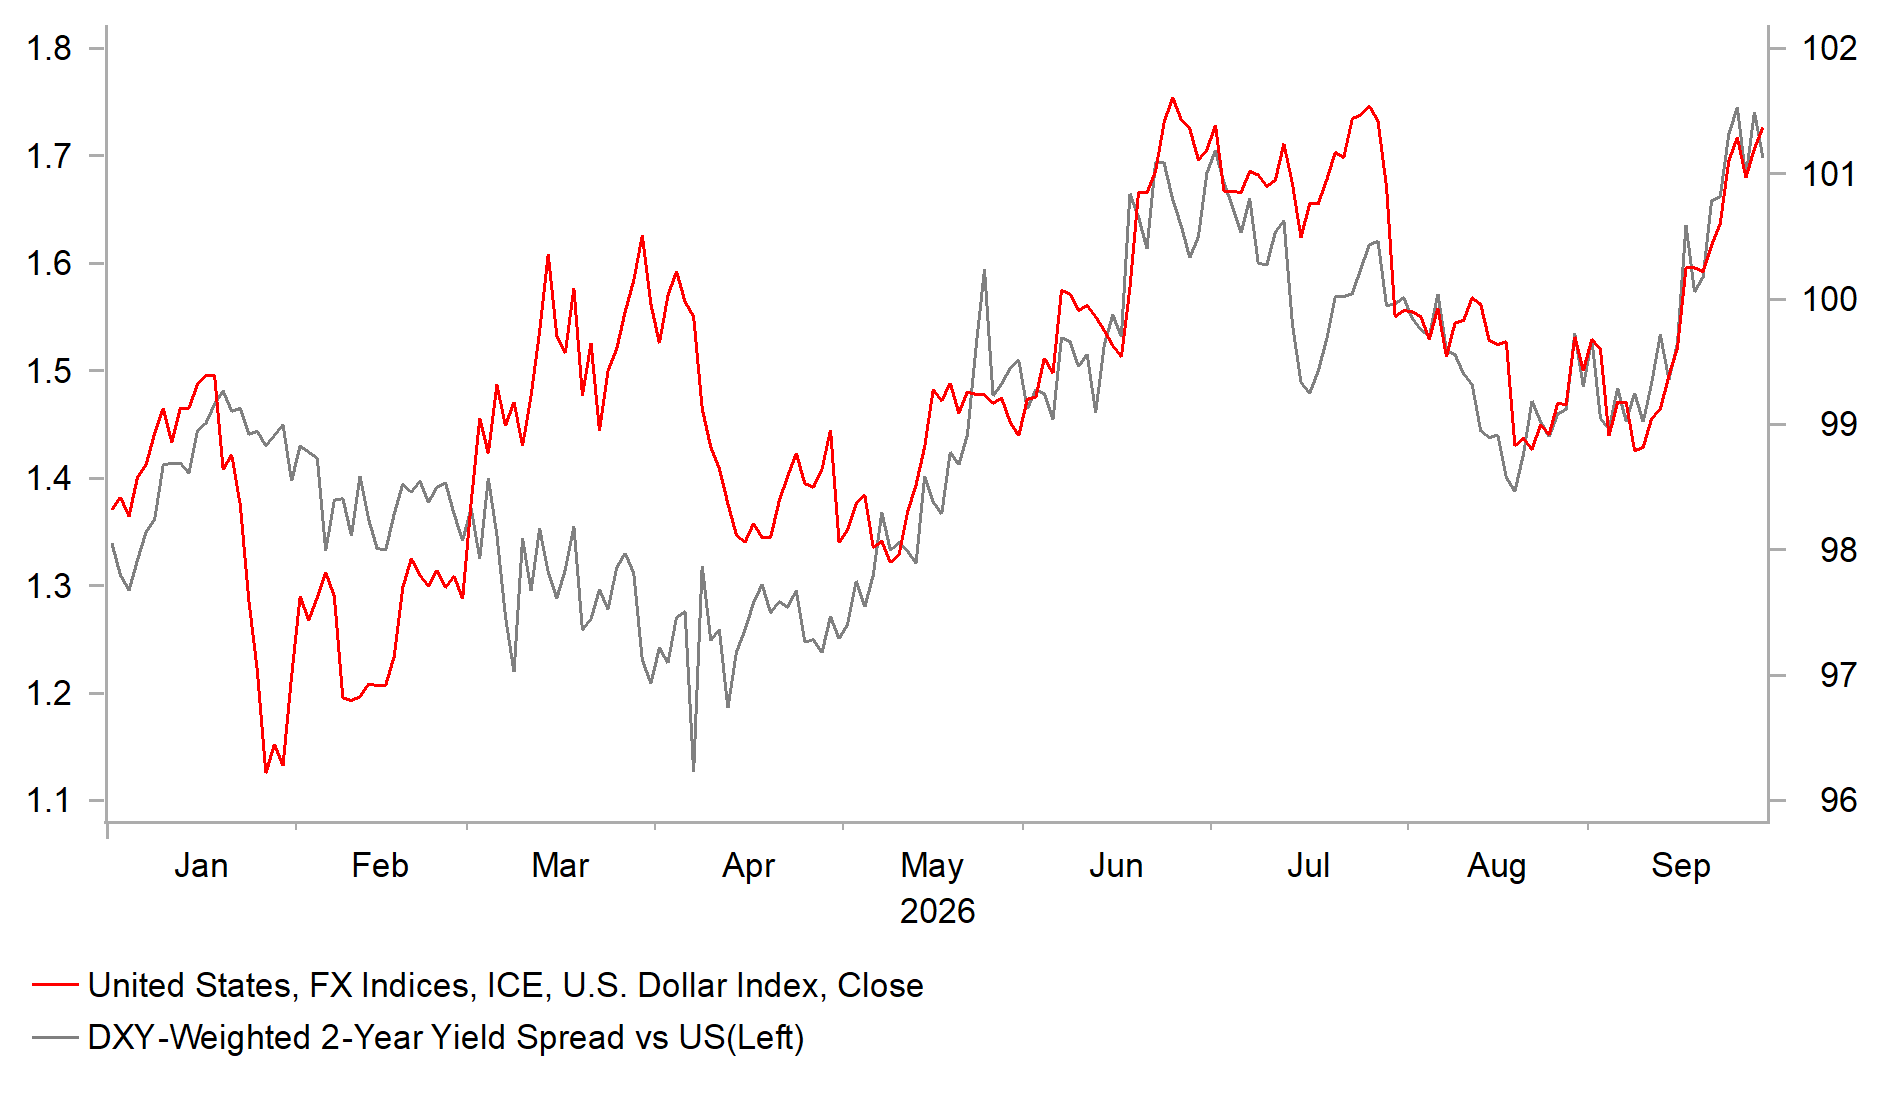
USD IS CLOSELY TRACKING SHORT-TERM YIELD SPREADS
Source: MUFG Research, Macrobond, Bloomberg
GBP: Stronger UK growth & PM Burnham opens door to UK rejoining EU
The pound has been consolidating at close to year-to-date lows against the US dollar this week at just above the 1.3200-level. The pound has been supported this year by the resilient performance of the UK economy. There was further good news this morning when it was revealed that economic growth revised up by 0.1ppt to 0.5% in Q2. It continues the strong start to the year for the UK economy which expanded by 0.6% in Q1. The BoE’s latest policy update also highlighted that the Bank’s staff are more optimistic now that stronger growth momentum has continued over the summer. They have raised their forecast for growth in Q3 to 0.4% up from their previous projection of 0.1% set back in July. Stronger growth will encourage the BoE to tighten policy soon if higher energy prices conte to prove more persistent. That was the clear message from BoE Governor Bailey last week who stated that “it’s getting harder to avoid rate hikes”. A view shared this week by Deputy Governor Ramsden who stated that “were upside pressures on the inflation outlook to continue to build, there could be a case for increasing the bank rate”. He judges that risks to the inflation outlook are “more titled to the upside”. The comments are consistent with our forecast for the Boe to begin hiking rates in November.
The other main development yesterday in the UK was the keynote address from Prime Minister Andy Burnham at Labour’s annual conference. He announced plans to make major policy changes including: i) breaking the pensions triple lock link to earnings from 2030, ii) creating a national care service, iii) indicating a greater willingness to re-open the debate over the UK’s relationship with the EU, and iv) pursuing electoral reform to move away from a first past the post system in favour of proportional representation. He outlined three options he would discuss at the UK-EU summit scheduled for later this year: i) rejoining the EU, ii) rejoining the single market and iii) entering a customs union. It opens up the possibility for a potential reverse-Brexit trade for the pound in the future. Plans for significant policy changes have also refuelled speculation that he could seek to hold an early election. Market focus will now shift to the upcoming Budget on 28th October which is an important event risk for the pound heading into year-end.
KEY RELEASES AND EVENTS
Country | BST | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
DE | 08:55 | German Unemployment Change | (Sep) | 1K | 4K | !! |
GB | 10:30 | BoE FPC Meeting Minutes | - | - | - | ! |
DE | 13:00 | German CPI (YoY) | (Sep) | 3.1% | 2.9% | !! |
US | 13:30 | Core PCE Price Index (MoM) | (Aug) | 0.3% | 0.2% | !!! |
US | 13:30 | GDP (QoQ) | (Q2) | 1.5% | 2.1% | !!! |
US | 13:30 | PCE price index (MoM) | (Aug) | 0.4% | 0.2% | !! |
US | 13:30 | Goods Trade Balance | (Aug) | -116.30B | -118.80B | !! |
Source: Bloomberg & Investing.com