
To read the full report, please download PDF.
Bond selling contagion risks spreading to FX
FX View:
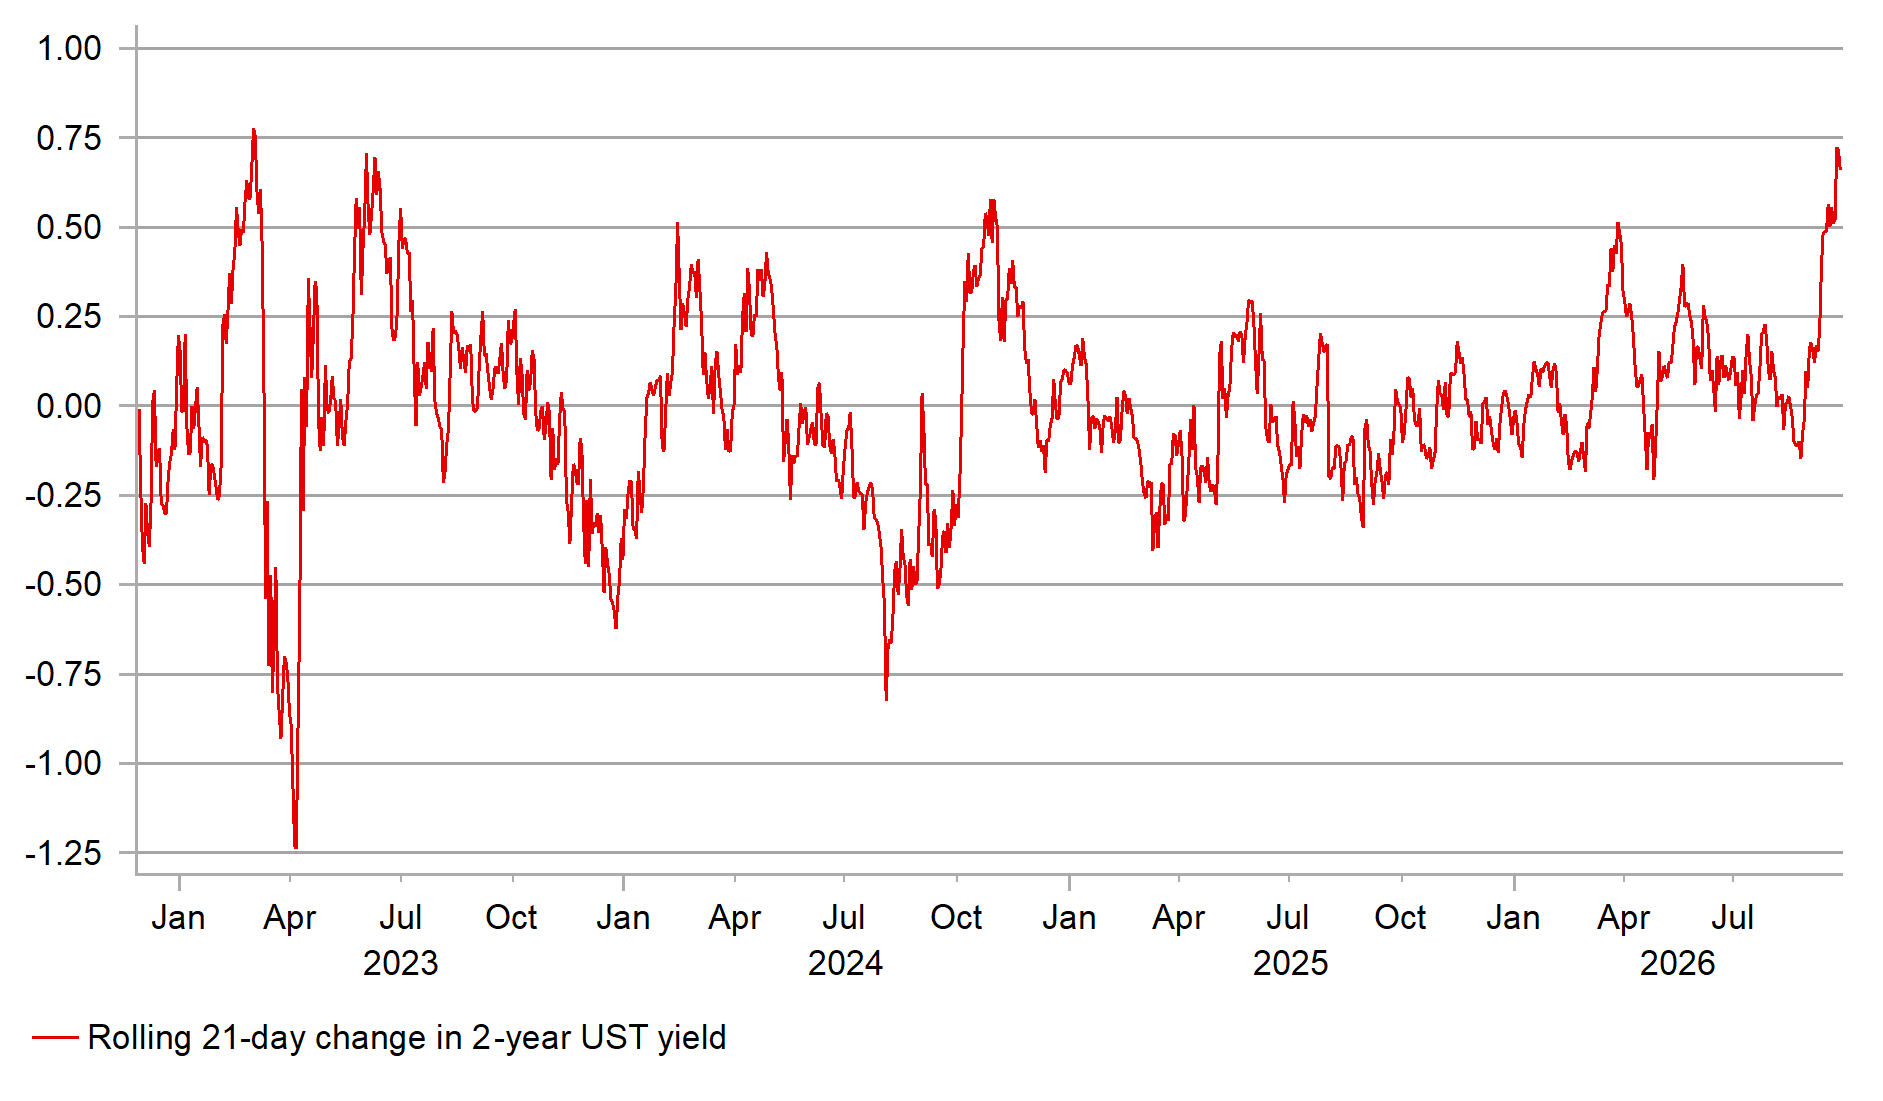
The heavy selling in fixed income has eased and with that the US dollar has modestly retraced recent gains. The fixed income selling has been significant and the 2-year UST bond yield jumped 72bps from Jackson Hole through to yesterday – that was the largest 21-day jump in yields since just prior to the US regional banking crisis in 2023. The scale of losses that have likely been realised by market participants raises the risk of contagion to other areas of the financial markets. Profitable positions could be cut leaving AI-related equity gains vulnerable to selling. IN FX, carry has been a profitable trading strategy and with volatility on the rise there are increased risks of an FX carry liquidation. EM FX volatility has risen as has JPY volatility. The yen is the top performing G10 currency today following further rhetoric from Tokyo that signals continued opposition to yen depreciation. If bond yields rise or further or even just remain at these elevated levels there is an increasing risk of broader risk reduction. The current divergence between equity and bond market volatility looks unsustainable.
BROAD-BASED USD GAINS ACROSS G10 AS GLOBAL YIELDS RISE
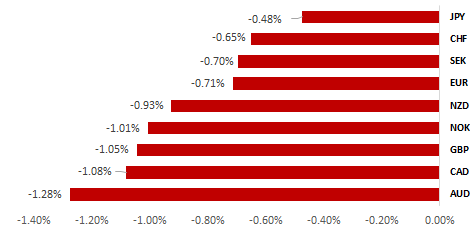
Source: Bloomberg, as of 25th September 14:20 BST (Weekly % Change vs. USD)
Trade Ideas:
We are maintaining our long USD/SEK trade idea.
JPY Flows:
This week we analyse the monthly Balance of Payments data for July. The current account surplus rebounded reflecting the jump back in the investment income surplus.
What Does the US Bond Market Rout Mean for FX?
The recent UST sell-off has been driven primarily by higher real yields and weak duration demand rather than inflation compensation.
FX Views
USD: The building risk of fixed income selling spreading
The US dollar has today retraced some of the gains recorded this week following some respite in fixed income markets with yields lower on some optimism that progress has been made toward the reopening of the Strait of Hormuz. The retracement is modest reflecting an understandable level of scepticism – we have been here before. For this to extend we will need to hear some positive noises from Washington. The respite is welcome after what has been a brutal move in global bond markets, led by the US Treasury market. In our view this move has raised the danger level and risks of broader financial market instability is increased. That could have significant implication for FX market conditions as well.
The recent US yield move is very significant and has caught a lot of the ‘fast money’ market participants off guard, resulting in notable losses and forced selling which has reinforced the move higher. Taking the period since the start of Jackson Hole in August (which culminated with Fed Chair Warsh’s hawkish speech), the 2-year UST bond yield has surged 72bps to yesterday’s close. That’s a move that took place over 21 days and is the largest 2yr yield jump over that same length of time since 3rd March 2023. On that occasion it was a big enough yield move to cause turmoil by bringing to the fore issues in the US regional banking sector. News of the collapse of Silicon Valley Bank (SVB) broke a few days later followed by Signature Bank and the news prompted a huge turnaround in the rates market as investors positioned for the Fed having to cut rates. The 2-year yield plunged 89bps in two days following the news. The US dollar had advanced over 4% in the month ahead of SVB collapse as US yields jumped and the dollar had fully retraced the move a month after the banking collapse. We are not suggesting further banking trouble now but the 2023 events do highlight the scale of the recent move has consequences for risk takers and the likely losses that have been suffered raise the risks of consequences going forward. There is now an increased incentive amongst market participants to cover those losses which raises the risk of profitable trades being liquidated to lock in profits.
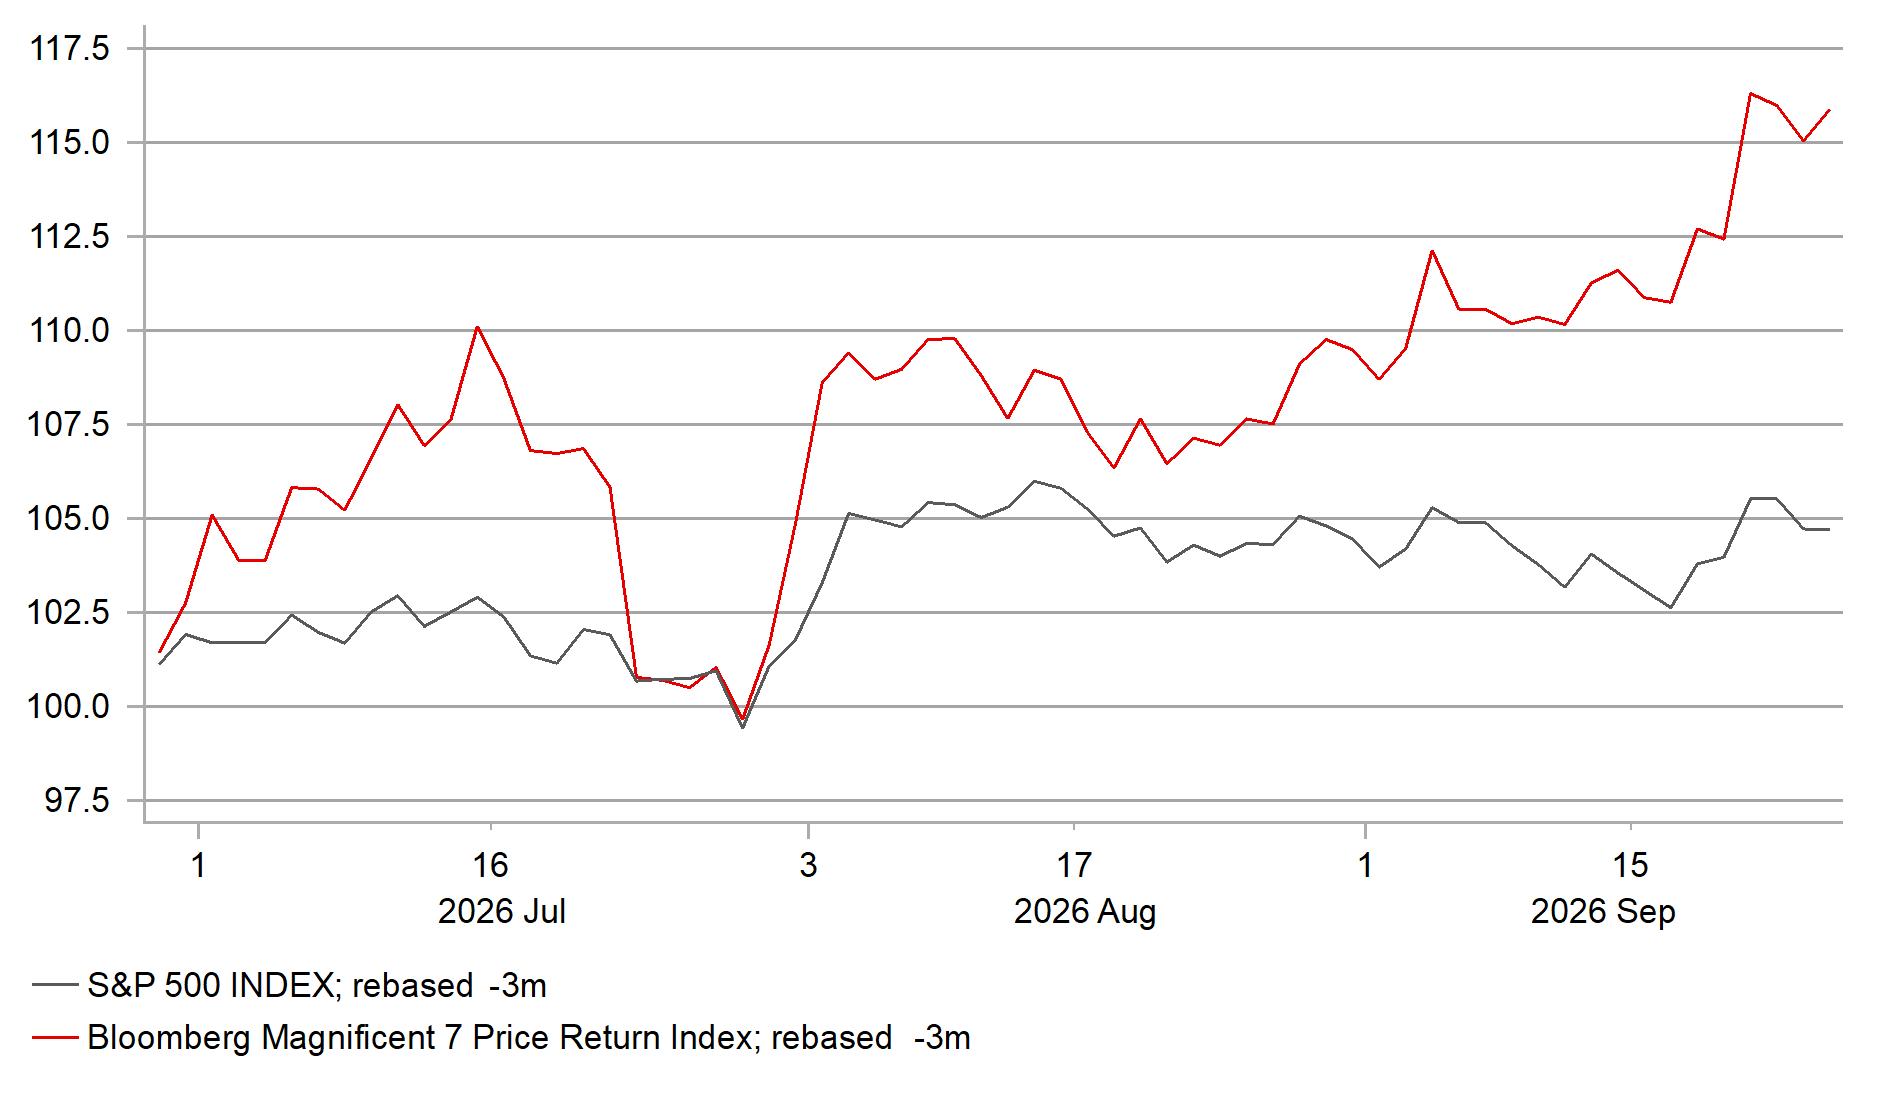
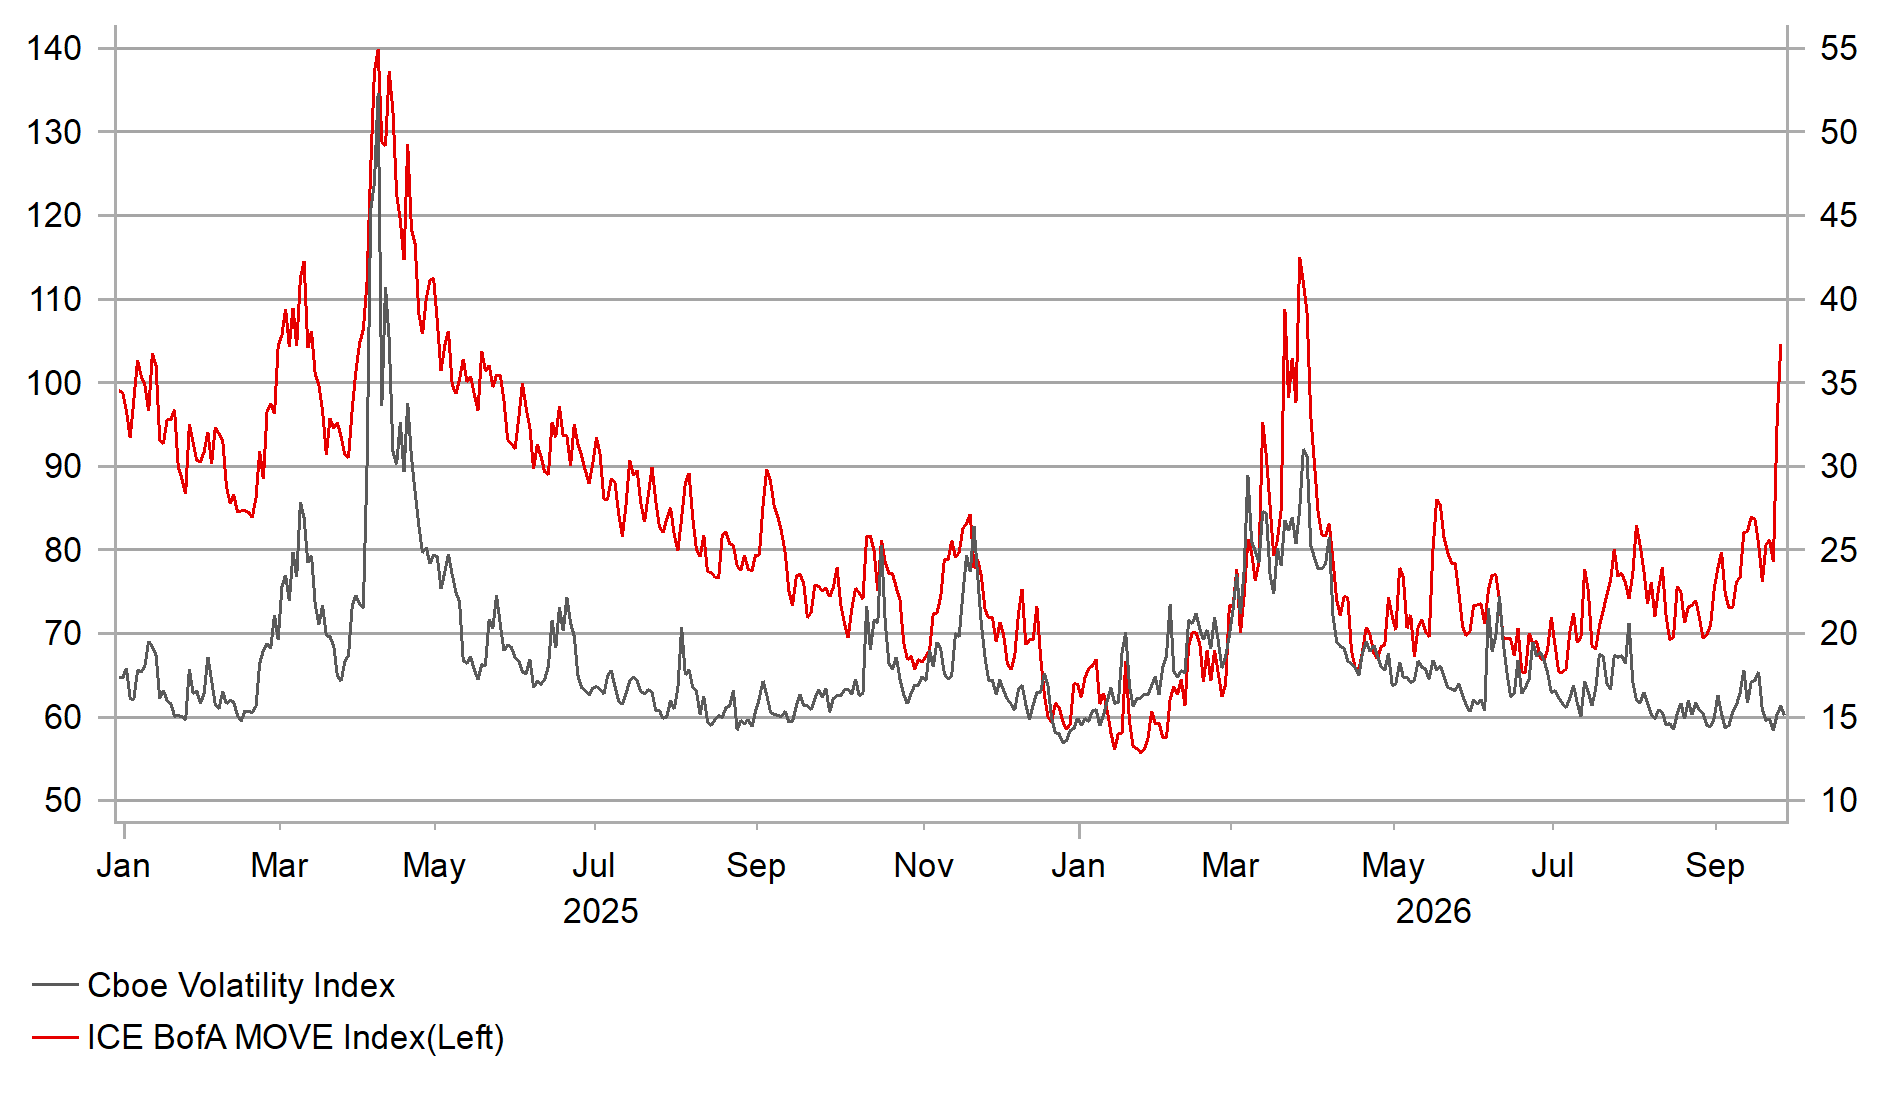
Strong risk appetite has been a consistent feature of financial market conditions, despite the geopolitical risks and the surge in energy prices. AI-related equities is an obvious area that could be vulnerable to a correction if yields remain elevated or extend further. The Nasdaq Composite did hit a new high this week but only just breaking above the June high before correcting lower. The Nasdaq is still basically flat relative to the close at the end of May. Possible signs that yields are starting to bear down on risk. There are substantial profit cushions there if there was a move to lock in profits to cover fixed income losses. Mag 7 is up 19% over the last three months versus 5% for the S&P 500. Meta has advanced by 36.5% in one month on the launch of its Muse AI agent. But conditions are getting more challenging as yields advance higher. Oracle closed yesterday at the lowest level since the end of July with the markets spooked by the news that Oracle sent a force majeure notice on a major New Mexico data centre project that suggests hyperscalers are becoming more concerned with potential delays to projects due to the growing opposition to data centres in the US. Calls for a slowdown in AI development are getting louder. This backdrop and a continued rise in US yields could be the catalyst for a larger AI-related sell-off. What really stands out this week is the divergence that has taken place between bond market and equity market volatility. The VIX remains around the 15-level while at the same time bond market volatility (MOVE) has surged. This divergence is rare and is unlikely to last.
21-DAY CHANGE IN 2-YR UST YIELD BIGGEST SINCE 2023
Source: Bloomberg, Macrobond & MUFG GMR
3MTH RETURNS GAP– S&P 500 VERSUS MAG 7
Source: Bloomberg, Macrobond & MUFG GMR
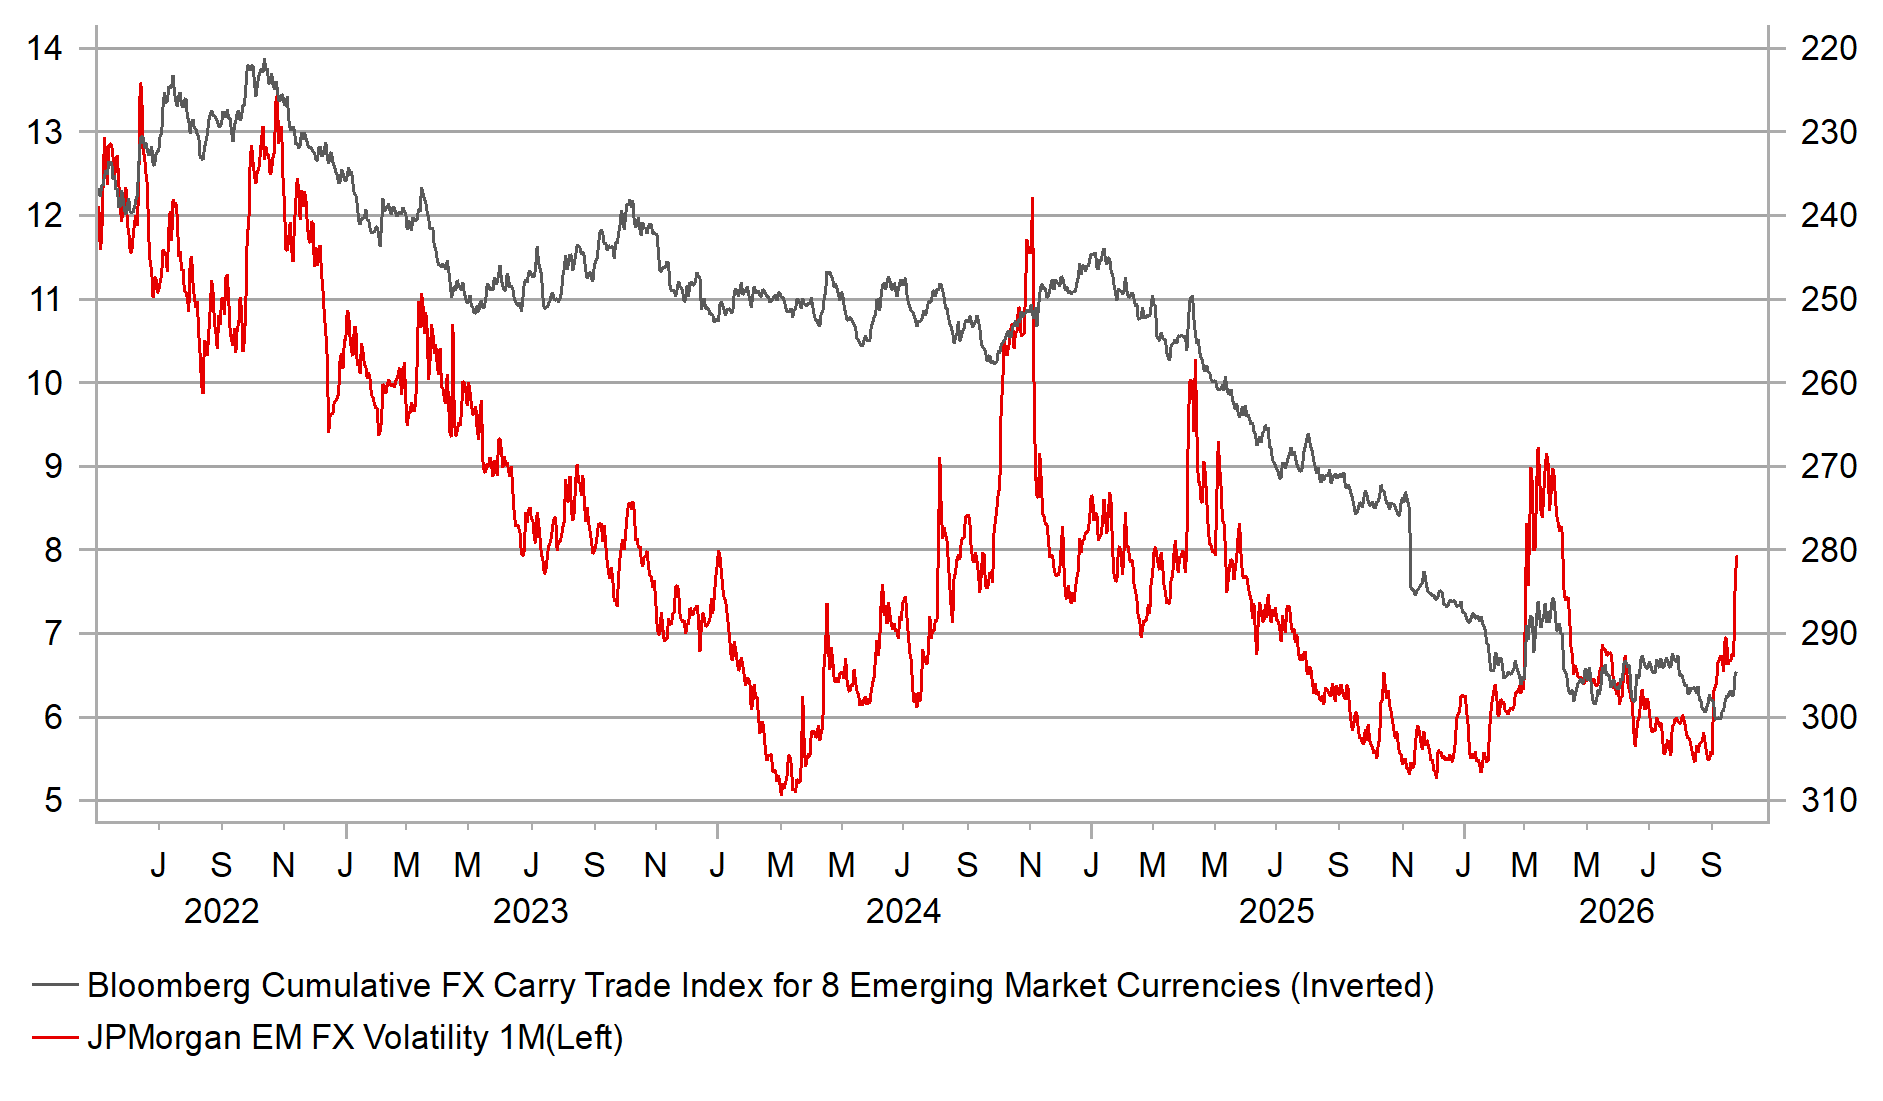
In the FX space, it’s obvious where the profitable trades are – FX carry. A popular strategy that has seen significant returns with FX volatility at remarkably low levels. EM FX volatility has recently jumped leaving EM FX carry more vulnerable to a larger clear-out of positions. 1mth implied volatility has jumped to levels not seen since the initial period of the conflict in the Middle East. But there is plenty of scope for a move still higher in vol with EM vol still below the peaks from earlier this year and following Liberation Day in 2025 and following Trump’s election win in 2024.
The yen is outperforming again today and there are signs that rhetoric from Tokyo is having an increasing impact on the yen. The comments from FM Katayama that President Trump expressed concerns to PM Takaichi over yen weakness and additional comments this afternoon opposing yen weakness and adding that PM Takaichi “is not a reflationist” point to Tokyo’s continued opposition to yen weakness. Growth Strategy Minister Miura was also very explicit is stating the “era of ‘Abenomics-style’ reflationary policies” is over. What is telling is not necessarily the comments but the reaction. The advance of the yen today we believe highlights signs of a changing dynamic in the USD/JPY market. The joint intervention, the checking of rates in USD/JPY and now these comments all point to higher hurdle for USD/JPY to retrace back higher. A key change is the level of yields. The BoJ has upped the pace of tightening and we believe that pace will be maintained with another hike in December. The yen therefore could well be best positioned to advance on any broadening out of investor selling from fixed income to risk assets. FX carry has been a consistent profitable trading strategy and an FX vol spike would change the risks. USD/JPY vol is now much less stable with 1mth implied swinging from a low of 6.0 through to 10.0 on first intervention and then BOJ rate hike speculation. Given the SNB policy meeting this week that signalled little risk of any monetary tightening the franc may not see as much safe-haven demand. Rates remain at zero and the SNB is opposed to franc appreciation. The MoF in Japan would welcome some further yen strength.
EM CARRY RETURNS AT RISK FROM VOL SPIKE
Source: Bloomberg, Macrobond & MUFG GMR
RATES / EQUITY VOL DIVERGENCE IS WIDE
Source: Bloomberg & MUFG GMR, as of 12:15 BST 18th Sept
Weekly Calendar
Ccy | Date | GMT | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
JPY | 28/09/2026 | 00:50 | BoJ Monetary Policy Meeting Minutes | -- | -- | !!! | |
GBP | 28/09/2026 | 11:00 | BoE MPC Member Ramsden Speaks | -- | -- | !! | |
AUD | 29/09/2026 | 05:30 | RBA Cash Rate Target | -- | 4.35% | !!! | |
CAD | 29/09/2026 | 13:30 | GDP MoM | Jul | 0.00% | 0.30% | !!! |
USD | 29/09/2026 | 15:00 | CB Consumer Confidence | Sep | -- | 89.4 | !! |
USD | 29/09/2026 | 15:00 | JOLTS Job Openings | Aug | -- | 7.271m | !!! |
GBP | 29/09/2026 | 16:00 | BoE MPC Member Mann Speaks | -- | -- | !! | |
JPY | 30/09/2026 | 00:50 | Industrial Production MoM | Aug | -- | -0.20% | !! |
AUD | 30/09/2026 | 02:30 | Monthly CPI Indicator YoY | Aug | -- | 3.50% | !!! |
CNY | 30/09/2026 | 02:30 | Official Manufacturing and Non-Manufacturing PMIs | Sep | -- | 49.8 / 49.0 | !!! |
CNY | 30/09/2026 | 02:45 | RatingDog Manufacturing and Services PMIs | Sep | -- | 51.5 / 51.4 | !! |
GBP | 30/09/2026 | 07:00 | GDP QoQ | 2Q | 0.40% | 0.60% | !!! |
EUR | 30/09/2026 | 08:55 | Germany Unemployment Change | Sep | -- | 4k | !! |
GBP | 30/09/2026 | 10:30 | BoE FPC Meeting Minutes | -- | -- | !! | |
EUR | 30/09/2026 | 13:00 | Germany CPI YoY | Sep | -- | 2.90% | !!! |
USD | 30/09/2026 | 13:15 | ADP Nonfarm Employment Change | Sep | -- | 38k | !! |
USD | 30/09/2026 | 13:30 | Core PCE Price Index MoM | Aug | -- | 0.20% | !!! |
JPY | 01/10/2026 | 00:50 | Tankan Large Manufacturers Index | 3Q | -- | 22 | !!! |
JPY | 01/10/2026 | 00:50 | BoJ Summary of Opinions | -- | -- | !!! | |
CHF | 01/10/2026 | 07:30 | CPI YoY | Sep | -- | 0.80% | !! |
GBP | 01/10/2026 | 09:00 | BoE Governor Bailey Speaks | -- | -- | !!! | |
EUR | 01/10/2026 | 14:30 | ECB President Lagarde Speaks | -- | -- | !!! | |
USD | 01/10/2026 | 15:00 | ISM Manufacturing PMI | Sep | -- | 54.6 | !!! |
USD | 02/10/2026 | 13:30 | Nonfarm Payrolls | Sep | -- | 162k | !!! |
USD | 02/10/2026 | 13:30 | Unemployment Rate | Sep | -- | 4.10% | !!! |
USD | 02/10/2026 | 13:30 | Average Hourly Earnings MoM | Sep | -- | 0.30% | !!! |
Source: Bloomberg & MUFG GMR
Key Events:
A busy month for G10 central banks (every G10 central bank met in September) comes to an end with the RBA meeting on Tuesday. The OIS market is pricing a 90% probability of a 25bp hike and we expect the RBA to deliver. A hawkish speech by Governor Bullock last Friday suggests a hike is a done deal and indeed if energy prices remain elevated, another hike again is a risk. That’s not our core view but a risk. The jobs data this week did show a rise in the unemployment rate despite a near 40k increase in employment. Some added labour market slack might help limit further rate hikes beyond next week.
The schedule of economic data releases is heavy next week and will culminate with the US jobs report for September on Friday. Data ahead of that will help shape expectations (JOLTS; ADP ISM) but the current 100k consensus would be a positive outcome following the stronger than expected 162k increase in August. A 100k increase would also be double the current 12mth average, above the 3mth average (71k) and close to the 6mth average (107k). A consensus print and a slight uptick in the annual wage growth rate (3.2% from 3.1%) would likely keep UST bond yields elevated as it would unlikely prompt a rethink of future Fed rate hike expectations. Inflation remains the more important indicator for determining near-term Fed policy expectations.
The schedule next week also includes key inflation data for Europe with national CPI data followed by the flash estimate for euro-zone CPI. The headline rate is expected to jump to 3.5% and would be consistent with further monetary tightening by the ECB, especially if crude oil prices do not soon start to retrace lower.