
ChinaPulse: Weak Demand, Policy Execution Ahead
Download the full PDF report using the link above.
Key Points:
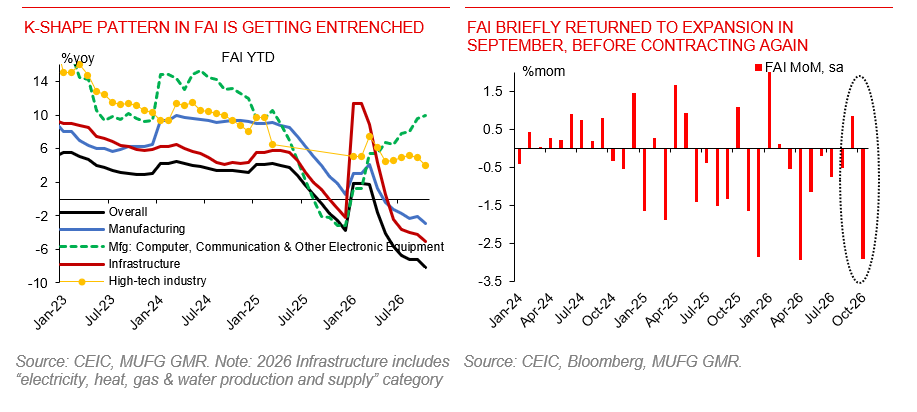
Domestic demand remained the key weak link in October, despite resilient external and high-tech activity. China started Q4 on a soft note, with October retail sales growth slowing to 0.4%yoy, partly due to the Mid-Autumn Festival timing shift, while FAI and property investment fell 8.1% and 21.6%yoy YTD, respectively.
Policy focus is shifting towards execution rather than major stimulus packages. We expect project implementation to accelerate in November-December, providing some support to investment and activity. However, the underlying K-shaped recovery is unlikely to change materially in near term.
USD/CNY: China’s external balance remains the strongest support for CNY, we maintain our forecast of 6.65 by the end of 2026. PBOC’s recent raising FX RRR from 4% to 6% indicates its resistance to rapid, one-sided CNY strengthening, although not necessarily an attempt to reverse the appreciation trend. This could mean that 6.65 may become sticky as USD/CNY approaches it.