
To read the full report, please download the PDF above.
Middle East Daily
EDWARD BELL
Head of Research
DIFC Branch – Dubai
T: +971 (4)387 5033
E: edward.bell@ae.mufg.jp
SOOJIN KIM
Research Analyst
DIFC Branch – Dubai
T: +971 (4)387 5031
E: soojin.kim@ae.mufg.jp
MUFG Bank, Ltd. and MUFG Securities plc
A member of MUFG, a global financial group
Middle East Daily
COMMODITIES / ENERGY
Geopolitical risk premium remains wide in oil markets. Oil futures are holding onto gains with December Brent futures up 0.4% at USD 106.13/b while WTI is adding closer to 0.4% to USD 94.51/b. A missile attack on the Saudi Aramco HQ along with a steady series of attacks against shipping in the Strait of Hormuz are helping to keep the geopolitical risk premium in oil markets wide at present. US Central Command has asserted than 19m bbl of oil passed through the Strait of Hormuz, helping to keep flows of Middle East energy exports intact though they are getting out to markets at elevated freight costs. China released September commodity import volumes which show oil imports continuing to remain low year on year: total imports fell 21% y/y and remain down 15% year-to-date. Refined products imports also remain low, down more than 53% y/y in September and down 22% ytd. OPEC revised its oil demand growth forecast for 2026 to just 200k b/d while for 2027 it expects a strong recovery of 2.6m b/d thanks to a surge in demand from emerging economies.
Gold holds range ahead of CPI release. Gold prices continue to tread water ahead of the release of the US September CPI report due out later today. Spot gold closed lower by 0.3% at USD 4,161/oz and is trading near unchanged today. New York Fed president John Williams said he expected one additional hike to rates this year but that the Fed wouldn’t need to do more in 2027. That has helped to lift Treasury markets and push yields lower. Among the rest of the precious complex only palladium is showing meaningful moves in trade today, up 0.8% to USD 1,135/oz.
MIDDLE EAST - CREDIT TRADING
End of day comment – 13 October 2026. The price action in GCC bonds remains better than the macro environment would suggest. Today we had a very strong morning, especially in duration bonds on the back of the UST bounce. That faded into the close, but price action and requests remained fairly two ways in any macro risk off move. Spreads are broadly 1/2bp tighter which cancels the 1/2bp widening from Monday holidays out. QATAR showed some activity today where new 36s closed +0.375pt/-2bp and 48s had buyers closing +0.5pt/-2bp. Against this the ADGB curve had a quieter day, 54s are going out +0.375pt/-1bp. One area of weaker price action remains financial bonds in general and AT1s specifically. Some of the AT1 still are in repricing mode against senior bonds, EBIUH 6.25 perps (31s) closed -0.25pt/+7bp. EIB priced a new 5y bond at 6.126% yield (reoffer 100, T+ 115bp). That's the first 6%+ coupon we have seen on a senior fin bond in a while and with some yield buyers back in the market should do better than recent new issues. Macro stability provided. (Source: Dominik Roth, Credit Trader)
MIDDLE EAST - MACRO / MARKETS
Asian crude imports recover as Middle East shipping activity picks up. Asian refiners are gradually restoring direct crude purchases from the Middle East as elevated freight costs and improving regional supply encourage a return to loading operations closer to the Persian Gulf. Japanese-controlled tankers have resumed collecting cargoes from Oman and Fujairah, although they continue to avoid transiting the Strait of Hormuz due to persistent security risks. Ship-to-ship transfers involving Japanese vessels reached nearly 3.7mb in early October, approaching September’s full-month volume of 4mb. Meanwhile, Chinese refiners are increasing spot purchases of Middle Eastern crude as regional exports recover, potentially slowing inventory drawdowns after an estimated 147mb were depleted since the conflict began. Around 96 super-tankers are scheduled to arrive in China over the next three months, reflecting stronger import demand and efforts to rebuild supply buffers. Recovering Middle East shipments should ease pressure on Asian refiners and reduce reliance on strategic inventories, although renewed tanker attacks, elevated freight costs and logistical bottlenecks continue to threaten supply normalisation.
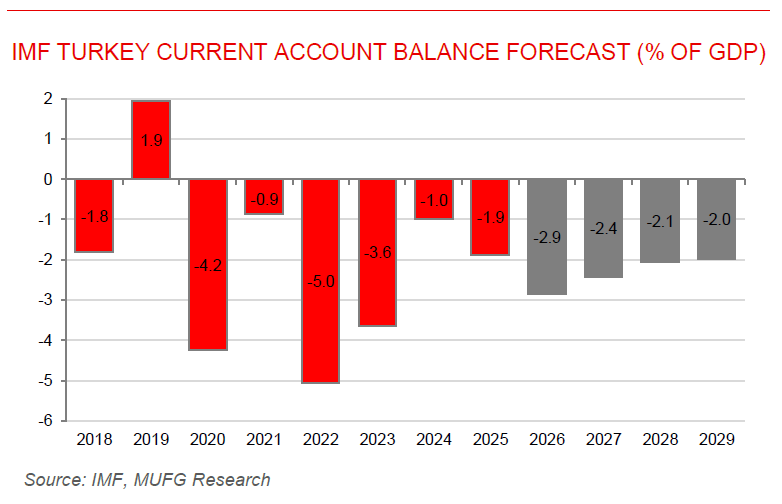
Turkey’s current account returns to surplus, CBRT remains cautious. Turkey recorded a USD 4.05bn current account surplus in August, driven by strong seasonal tourism revenues and a narrower trade deficit as lower energy prices reduced import costs. Despite tourist arrivals remaining slightly weaker than last year, higher spending per visitor helped support services exports. On the financial account, net FDI stayed positive but fell to USD 141m, while portfolio flows turned negative with a USD 1bn outflow. The improved external position contributed to a build-up in FX reserves during July-August, although the central bank has since sold USD 10.8bn in reserves since September to support TRY liquidity. Looking ahead, the CBRT is expected to remain cautious despite inflation easing to 29.7% y/y in September, with elevated energy prices and declining reserves likely delaying the resumption of its rate-cutting cycle.